Individual Economists

Remembering The False Gloom And Doom Of The 1992 Elections... And The Upcoming Midterms

Zero Hedge -

Remembering The False Gloom And Doom Of The 1992 Elections... And The Upcoming Midterms

Authored by Victor Davis Hanson via American Greatness,

Republicans risk repeating 1992 by failing to counter economic pessimism with the facts about strong growth, falling inflation, rising incomes, and a recovering economy.

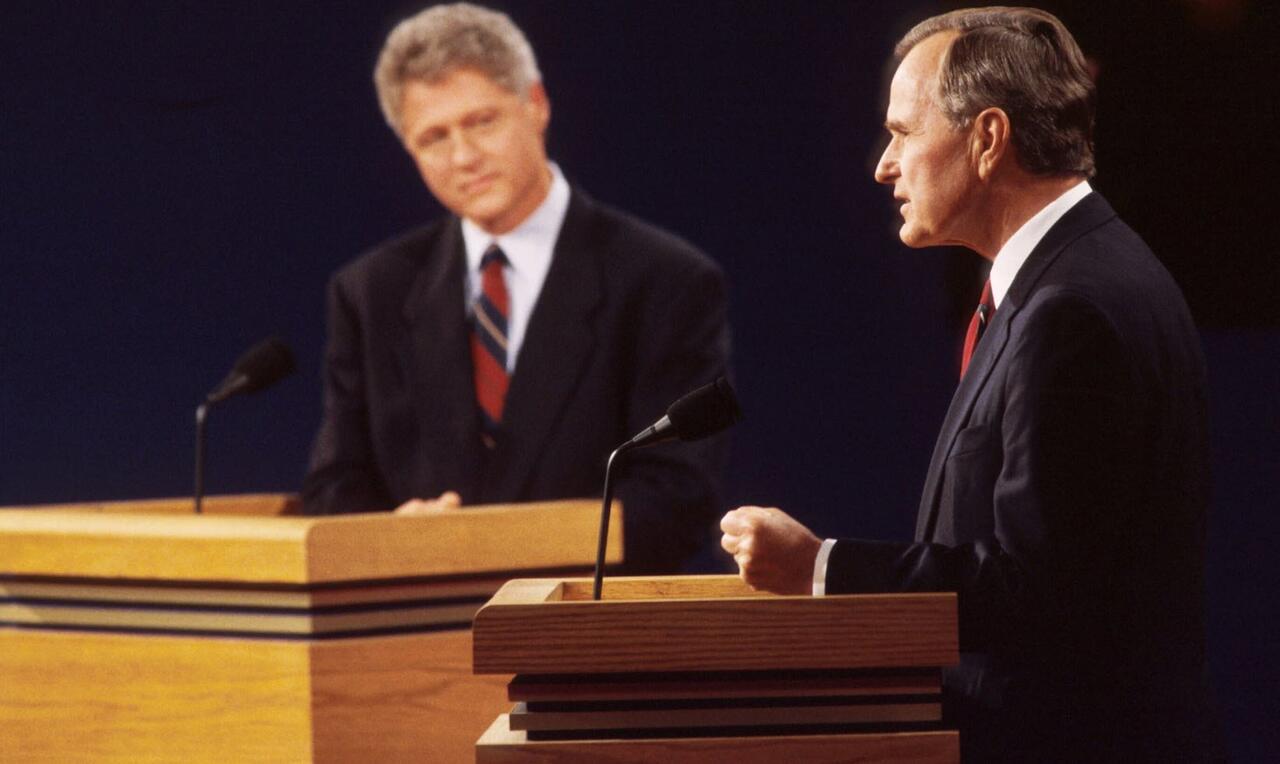
In 1992, Bill Clinton won the presidential election partly on the basis of his campaign's false accusation that George H. W. Bush had overseen "the worst economic performance since the Great Depression." Or so claimed Clinton's running mate Al Gore.

James Carville, chief campaign adviser to Clinton/Gore, amplified that message with the constant refrain: "It's the economy, stupid."
That strategy worked for three reasons.

First, third-party candidate Ross Perot siphoned off nearly 19 percent of the vote. Most of his supporters would otherwise likely have gone to Bush. Perot allowed Clinton to win with a mere 43 percent of the popular vote, in part by echoing the false narrative of a crushing Bush recession.

Second, the brilliant Bush campaign strategist Lee Atwater, who had virtually destroyed the Dukakis campaign in 1988 - remember the tank ad, the Boston Harbor ad, and the Willie Horton ad? - had died in 1991 at the age of 40 from a brain tumor.

Atwater's canny but hardball 1988 tactics had turned off establishment Republicans. So in 1992, Republicans reverted to the notion of losing nobly rather than winning ugly and resumed unilaterally playing by the Marquess of Queensberry rules. The result of Democratic demagoguery was that the sober and competent elder Bush was branded a heartless elitist who had wrecked the economy and defended Kuwait only for "blood for oil." And without Atwater, the Bush team utterly failed to refute such caricatures and counterattack.

Third, and most important, the anemic Bush reelection campaign never refuted the Clinton-Gore economic hysteria. That "recession" deception had drowned out the historic foreign policy achievements of Bush's four years, from the successful policies that followed the fall of the Berlin Wall in 1989 to the decisive 1991 Gulf War.

Despite overwrought claims about a recession or even a new Great Depression, in truth, the recession had ended in March 1991. In fact, final GDP growth for 1992 was a robust 3.52 percent. That was hardly a recessionary indicator. Indeed, the election-year growth proved even stronger than in Clinton's first year of governance in 1993.

While unemployment was still high at 7.5 percent, the 1992 stock market nonetheless grew by 7.6 percent. And the 1992 inflation rate had stayed moderate at 2.9 percent.

In other words, the economy had already begun to recover from the 1990-91 recession, which - to reiterate - had officially ended 20 months before the 1992 election.

One cause - eerily now familiar - of the earlier 1990-91 downturn was that oil prices had initially doubled after the 1990 Iraqi invasion of Kuwait and the U.S. military response. But prices collapsed as soon as Operation Desert Storm began, despite the later torching of the Kuwaiti oil fields and continued uncertainty in the Gulf. Yet by the November 1992 election, oil prices had long been back to pre-invasion levels.

In short, the Democrats' charge that 1992 saw the worst recession in 60 years was absurd. (The 1973-75 and 1981-82 recessions were far worse than the 1990-91 recession.)

Fast forward to the present. The economy today is far better than in 1992. But Democrats' successful 1992 demagoguery should remind Republicans that the perception of the economy peddled by campaign rhetoric can often decide elections more than the reality does.

Take the just-released 2025 poverty rate. It hit an all-time low of 10.2 percent. Child poverty also fell to a historic low. Such amazing news refutes wild leftist charges that uncovering vast welfare fraud, deporting thousands of illegal aliens, and cutting 400,000 federal jobs would spike poverty. In fact, those actions more likely contributed to reducing poverty, as did an astounding lowest violent crime rate in some 70 years.

Median household income also hit a record high of $87,460. That is the highest median household income in the world, dwarfing all other large industrial nations that are not petro-states or tax havens. The same holds true for our GDP per capita - which, incidentally, was already over $34,000 higher than in Canada.

New business reports show that this past August manufacturing achieved its largest monthly increase since 2022. And service-sector growth jumped to its highest level since 2021. New orders for metals, machinery, computers, appliances, communications - in truth, almost everything - continue to rise every month, especially and most recently in August.

Despite the Iran war and its global petroleum interruptions, the Atlanta Federal Reserve now predicts that third-quarter GDP growth will finish at a blistering 5 percent. The Dow and the S&P have grown by a strong 8.1 percent and a staggering 13.5 percent, respectively, in 2026.

Take away the climb in gas prices from a January 2026 average of $2.81 a gallon to $4.50, and the inflation rate was only 2.5 percent - below the 2025 yearly average of 2.7 percent - and Wall Street estimates put the annual rate at around 2.2 percent once the Iran war ends and a huge influx of oil hits the global market. The United States is now the greatest producer of oil and the greatest producer and exporter of natural gas in history - and is still increasing output.

August unemployment was a low 4.1 percent, while 162,000 new jobs were created in that month alone. Consumer spending remains strong.

The U.S. economy is entering a boom cycle. Its growth ensures that it remains the largest in the world and continues to outpace all competitors.

Many of the dire predictions at the millennium about the supposedly superior collectivist paradigm of the European Union - or the inevitable rise of a China of 1.4 billion people - surpassing the United States simply did not come true.

The EU has about 100 million more people than the United States. China's population is four times larger than America's. Yet both have fallen further behind the United States in terms of economic production.

Indeed, the U.S. economy is roughly $10 trillion larger than either China's or the EU's. Far from some predictions of a decade ago that within 10 years China would overtake the United States, the opposite has occurred. America's nominal GDP of $18.8 trillion in 2016 soared to $32.4 trillion in 2026 - as the American share of global GDP increased to 26 percent. In contrast, the EU's share of global GDP actually shrank, and China's still stayed well behind the United States.

In key categories such as digital media, software, AI, bioengineering, and space technology, American companies remain the world's largest and most successful. They usually dominate global top-ten rankings, with eight or nine U.S. corporations among the top slots.

If the Republicans broadcast this positive news about the economy, it will in turn complement Trump's unambiguous foreign policy successes, which are largely underappreciated, if not unknown, among the public.

But they remain impressive: the rebooting of NATO by getting its members to rearm and take up their fair share of collective defense; the acquisition of new treaties ensuring an American military presence in the Greenland to monitor the contested Arctic; the radical transformation of much of the Western Hemisphere from leftist and anti-American nations into pro-American, tough-on-crime, free-market countries; the expulsion of the Chinese bad actors from the Panama Canal and the extradition of the anti-American communist Maduro from Venezuela; the restoration of Pentagon recruitment; and the change in Pentagon procurement to emphasize quantity of weaponry along with quality.

The verdict on the unpopular war against the Iranian theocracy is still out. But the idea that the last seven months of on-again, off-again strikes and negotiations amount, in terms of human and material costs, to a "forever war" is absurd and a lie.

While all our soldiers' deaths are tragic, the conduct of the war against the terrorist powerhouse of the Middle East had deliberately been waged to limit the loss of American lives. Indeed, the average daily fatality rate due to accidents in all branches of the military during the seven months of the Iran conflict is some eleven times greater than the number of those killed fighting Iran.

The roughly $40 billion cost of the war so far, while substantial, amounts to about 25% of the conservative estimates of recently discovered welfare corruption and fraud in California alone - involving theft of Medi-Cal, unemployment insurance, in-home services, and hospice funding.

The war will be judged by historians, fairly or not, on whether it delays for years or, if not, ends Iran's quest for nuclear weapons altogether, and on whether it so weakens the theocracy that it permanently loses its terrorist leverage over the Middle East - if not eventually implodes from popular resistance. If such a regime collapse should follow the conflict, the Middle East miasma of the last 70 years would largely end, marking the most profound American achievement abroad since the fall of the Berlin Wall.

So much is at stake.

Nevertheless, the Republicans have not yet developed a strategy to inform the public that the economy is sound and improving - and will likely soon take off, after the Iran conflict is over, oil becomes plentiful again, and tax cuts, foreign investment, deregulation, and productivity gains from AI take their full effect.

Most importantly, Republicans have still not articulated why the "affordability" issue persists. Under Joe Biden, average prices were nearly 21 percent higher than when he took office, with a yearly average increase of more than 5 percent.

The Trump administration nearly halved that annual rate in 2025. It will reduce Biden's yearly inflation rate substantially again in 2026.

But neither Trump nor any other president could or would wish by design to engineer radical deflation to restore prices to the pre-Biden levels of 2020 during Trump's last year in office.

Trump's first-term total four-year inflation rate was under 8 percent, averaging about 2 percent per year - far less than half the yearly inflation average of the subsequent Biden years.

In 2025, wages still climbed higher than the rate of inflation. But it would require a damaging recession to undo Biden's 20 percent rise in prices. And worse still, the cost of staples such as food, shelter, vehicles, fuel, and insurance rose nearly 30 percent over Biden's four years.

Nor have Republicans made the easy case that the midterms are no longer merely a matter of liberal versus conservative, Democrat versus Republican, or even progressives versus MAGA.

Rather, November 3 represents normality and common sense pitted against an unrecognizable "Democratic" revolutionary party that is driven by Islamist-sympathizing socialist zealots who are not fond of the United States as it has existed for 250 years. They are not shy about planning to remake America along the lines of, at best, radical European socialism and, at worst, something resembling Cuba.

Needless to say, if they get their way, even the most lurid false liberal claims about our current alleged economic problems will pale by comparison.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.
Tyler Durden Thu, 10/01/2026 - 16:20

"Showings Have Stopped": Housing Market Freezes As Mortgage Rates Soar To 7.28%, Highest In 3 Years

Zero Hedge -

"Showings Have Stopped": Housing Market Freezes As Mortgage Rates Soar To 7.28%, Highest In 3 Years

The American dream has never been more out of reach.

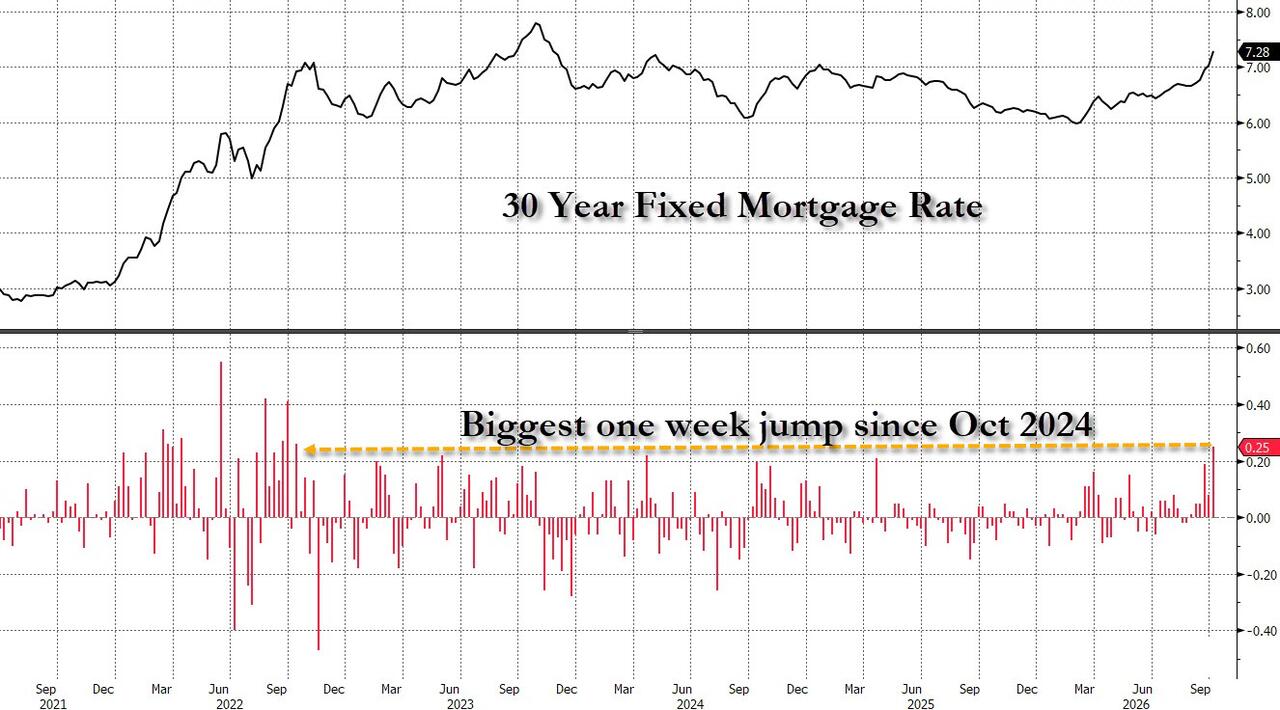
Mortgage rates posted their largest increase in four years this week, one of the clearest signs of how the recent bond-market selloff is spilling into the broader economy - if not memory and chip stocks which continue to trade entirely on the highly efficient circular financing and junk bond markets.

30-year fixed-rate mortgages rates surged 25bps in one week, to 7.28% from 7.03%, the biggest jump since October of 2022, according to Freddie Mac.

Mortgage rates have risen to the highest since November 2023 as inflation, a surge in government debt and heavy corporate borrowing for the build-out of AI (not to mention the latest European sovereign debt crisis) push up bond yields. The recent sharp selloff in the bond-market has risen borrowing costs for home buyers and dealt a blow after blow to a limping housing market.

“Showings have stopped basically,” said Don Wessel, a real-estate agent in Greenville, S.C, quoted by the WSJ. "I’ve got good listings in downtown Greenville, which is one of the hottest areas, and nobody’s looking at them."

In 2022, rates surged as part of postpandemic inflation that ended years of below 5% mortgage rates and ground the housing market to a halt. Home sales still haven’t recovered from that rapid freeze four years ago. With rates now at their highest point since 2023, buyers are likely to stay planted on the sidelines, while sellers may take their homes off the market.

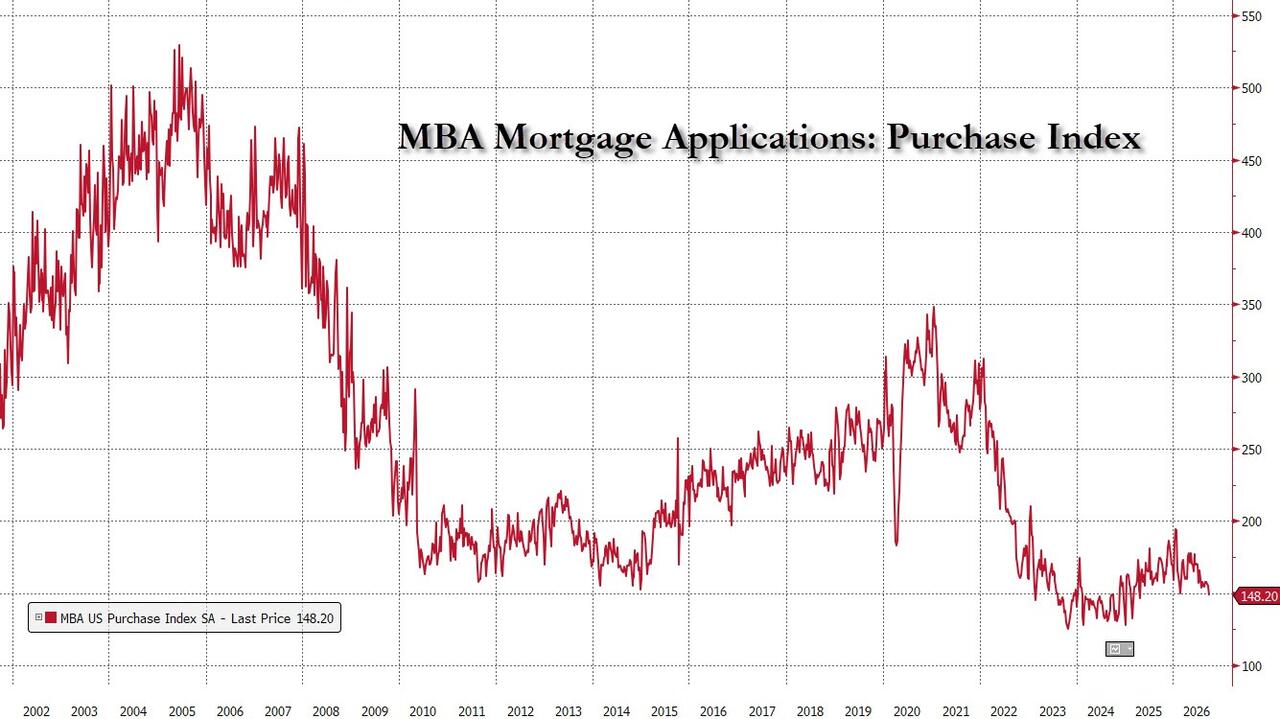
The market may not be completely frozen - yet - but it's getting these: for the week ending Sept. 25, mortgage applications plunged 6%, the fourth consecutive week of declines, according to the Mortgage Bankers Association. 

At the start of the year, mortgage rates touched below 6%, but the beginning of the war in Iran caused them to jump. As the conflict has drawn on, fears of sticky inflation have driven rates higher and higher. Rates began September at 6.71% before a historic bond selloff sent them surging more than 50bps higher. 

With the 10Y TSY today hitting the highest yield in 24 years, Americans have been feeling the pain of the bond selloff most directly and rapidly through the housing market, where mortgage rates closely follow 10Y Treasury yields. 

As the WSJ reports, the recent run-up in mortgage rates has brought sales activity in the housing market to a standstill, as buyers have already been coping with record home prices and stretching to afford down payments. Plus, with sky-high homeowners association fees and property taxes, the math has become impossible for first-time buyers to work out.

Now, the end of 2026, a year that was expected to launch the market’s recovery, is likely to be a slog.

“I still see it declining and you’re coming into the slow part with the holidays,” Wessel said. “I think there’s a short window now for sellers to sell and then buyers get out of the market.”

That said, buyers in the upper end of the market, many of whom transact in all cash and don't need mortgages and are generally less constrained by affordability, are continuing to show interest, said Anthony Rael, an agent in Denver. “They seem to be flush with cash, bringing 20%, 30% down payments into the mix,” he said. “Whereas the lower market, let’s just say closer to a half a million and below, is really struggling where we’re getting lots of showings and no activity, no offers.” 

Higher mortgage rates could also halt progress the market has made in freeing up inventory. For years, homeowners have been wary of selling their homes to preserve their low mortgage rates from years ago. That sent inventory plummeting, which has allowed home prices to continue hitting new records, despite weak demand.

While there were a few scattered signs that the lock-in effect was starting to ease as sellers lost patience and gave up their low rates to move for family reasons or new jobs, as inventory approached prepandemic levels in August, but now, rates well above 7% are sure to drive sellers away.

In July, Adam Wharton and his wife bought a new house in Georgia but haven’t been able to sell their old house, which they listed at the beginning of September. There initially was a flurry of interest, and they accepted an offer, before the buyer backed out.

“We were getting multiple showings a day. Within four days, we had a full-ask offer on it,” he said.

But then after rates jumped, the buyers disappeared. Their last showing was two weeks ago. “Since that, it’s been nothing, no scheduled showings, no offers, no nothing from people who have looked at it before,” he said.

The mortgage they have on the house, with a rate of 3.35% and a monthly payment under $1,000, is extremely cheap, and so Wharton isn’t in any rush to sell. Now, they are considering taking it off the market and renting it out if they don’t get any offers, waiting for the market to loosen up before listing it again.

“Everybody has in their minds these two and three and four percent mortgages,” he said, but he will have to wait until the next recession - or depression - before those come back again. 

With mortgage rates breaking through 7%, some home buyers are considering the familiar strategies for lowering their monthly payments: putting more money down, using adjustable-rate mortgages and even buying in cash.

While increasing the size of the down payment would help offset the monthly bill that comes with a higher mortgage rate, home prices are up more than 50% since 2019, and many buyers are struggling to find the cash to boost their deposits above the typical 10% to 15% down.

That has scrambled the usual buyer playbook for adjusting to higher borrowing costs. Typically, when mortgage rates rise, sellers have to cut prices to keep buyers in the market. But for years, supply has lagged behind as many homeowners have opted to stay put to preserve the 3% to 4% mortgage rates that they secured in the wake of the pandemic. 

This lock-in effect—homeowners refusing to sell and give up a low mortgage rate they locked in years ago—has allowed prices to continue rising, even as demand has sagged. The national median existing-home price in August rose 1.6% from a year earlier, to $429,100, an August record. That is despite sales falling to their lowest level and interest rates pushing to their highest point in more than a year.

Median down payments have increased a bit this year as the rise in mortgage rates has encouraged buyers to spend more money upfront to lower their monthly payments. The median down payment in January of this year was $23,053, according to Realtor.com. In August, it was up to $27,166. Over the same period, the median down-payment percentage has risen to 13.8% from 12.8%.

But Christina Beitler, who runs a mortgage brokerage firm in Austin, Texas, said the recent rise in rates has ground the market to a halt.

“We’ve all hit a wall. We’ve pretty much seen a very large stalling of activity,” she said. “I do think right now, buyers are taking a step back, taking a moment of pause.”

As the WSJ notes, even in the wake of the 2008 housing crash, when home sales sank, buyers with good credit could take advantage of lower mortgage rates than today and a fall in home prices. Supply benefited from lenders looking to unload millions of foreclosed homes. Beitler said she recently quoted someone a mortgage rate on a Monday, and by the time they went under contract on a Thursday, the rate had increased over half a percentage point. “They literally just said, ‘I can’t do this,’” she said, adding that the person terminated the contract.

As older homeowners often point out, before 2001, mortgage rates were just about always above 7%, and in the 1980s, they reached as high as 18.63%, according to Freddie Mac. As a result, housing affordability was even worse back then, but low home prices allowed buyers to put down larger-percentage down payments to help mitigate the higher rate. 

In 1980, the median home value was $47,200, while median household income was $17,710, according to the Census Bureau. Now, home values are up to $368,700, according to Zillow, outpacing income, which in 2025 was up to $87,460. That means that for many buyers, down payments have become far more of a financial burden.

Continued growth in down payments could be modest, mostly because many buyers are already putting down as much as they can and simply can’t afford to contribute any more, said First American Chief Economist Mark Fleming.

“For a lot of the affordability-constrained borrowers, they don’t have the option,” he said.

Tyler Durden Thu, 10/01/2026 - 15:46

Supertanker Ablaze After Iran Attack In Hormuz As US Deploys 10K More Troops & Third Carrier To Mideast

Zero Hedge -

Supertanker Ablaze After Iran Attack In Hormuz As US Deploys 10K More Troops & Third Carrier To Mideast

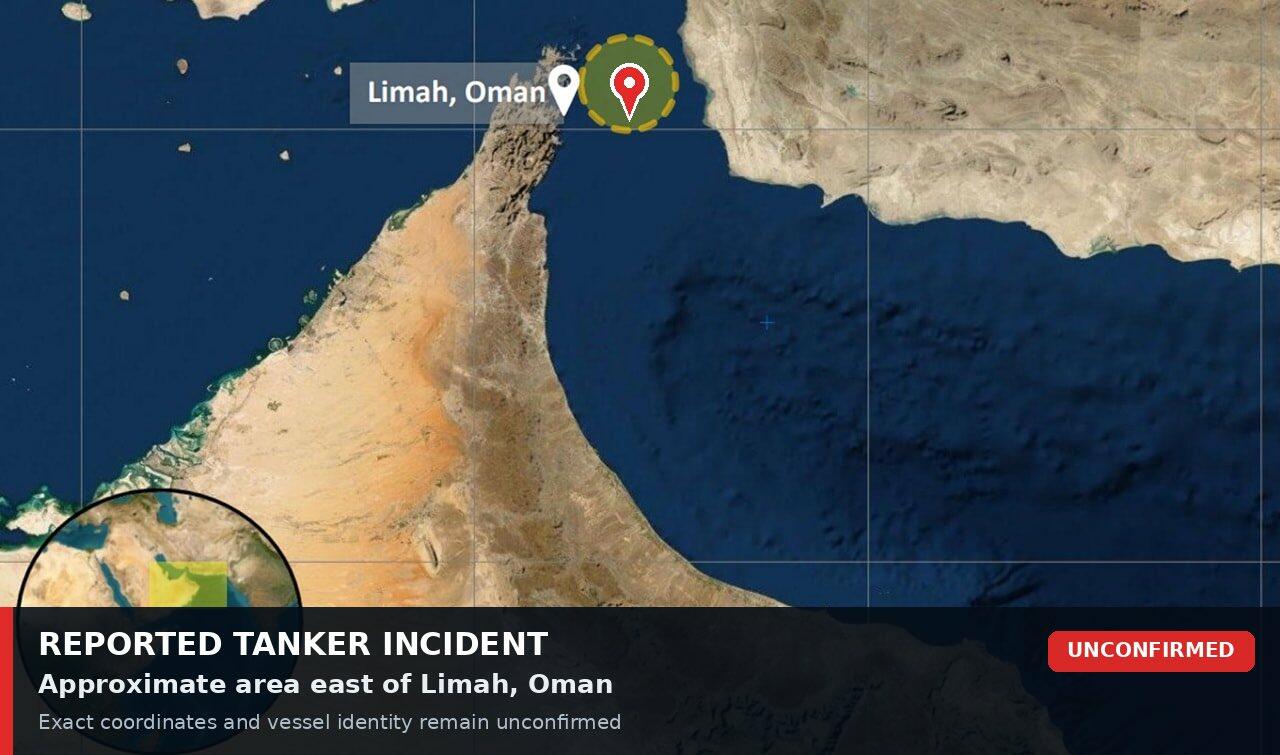
Update(1530ET): Iranians are apparently going back on the offensive, after it's been widely reported that US-protected oil transit through the Strait of Hormuz has been fast gaining steam. Iran state media says a supertanker is burning off the coast of Oman after coming under Iranian attack:

Local sources reported that a 2.5 million barrel capacity supertanker that was traveling through the Strait of Hormuz illegally was hit 8 kilometers off the coast of Oman and is burning, reports Fars

Earlier we reported that starting in mid-August (on Aug. 16), Iran’s Supreme National Security Council set October 1 as a deadline. It warned at the time that if Washington failed to lift its naval blockade of Iranian ports within 45 days, Tehran could resume attacks against US forces, and by implication step up attacks on foreign shipping.

Iran’s 45-day deadline for the United States has now expired. That deadline has now passed, potentially adding another layer of uncertainty to an already tense confrontation where Tehran may decide it must act 'preemptively' while facing more bombs by Trump (likely after the midterms).

*  *  *

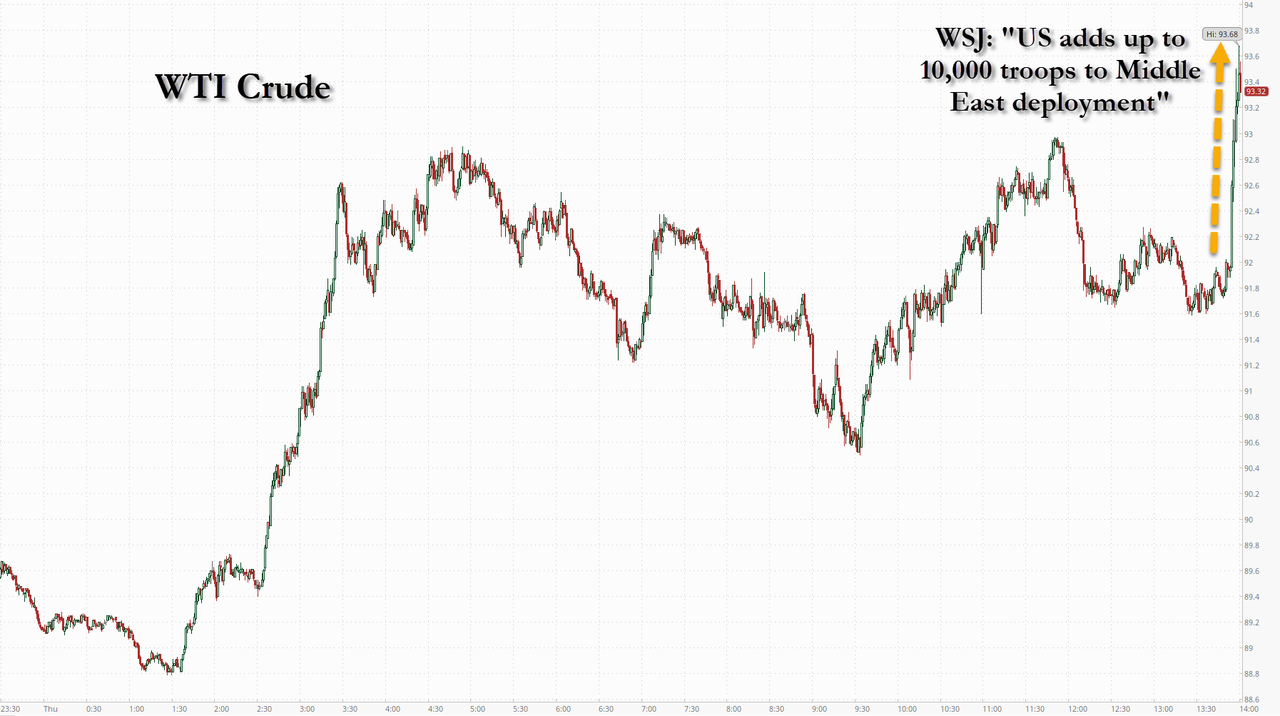
Signs of potential major escalation, or the next round at least (which Trump has hinted will come after the midterm elections), just hit The Wall Street Journal, and sent oil prices soaring. A quick summary:

  • The Pentagon is sending a third aircraft-carrier strike group and additional Marine Corps ships to the Middle East, adding 9,000 to 10,000 more troops to the region.
  • The ships, jet fighters, Marines and sailors will arrive in the region by the end of November, as President Trump considers renewing strikes on Iran after the midterm elections.
  • The additional servicemembers will add to the more than 50,000 troops already in the region, with the deployments coming after Trump rejected Iran's latest proposal for a seven-day ceasefire.

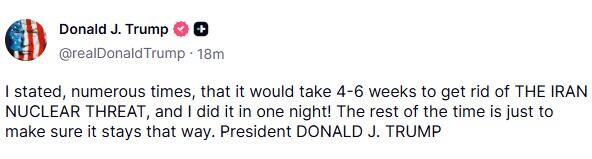
The Trump administration is deploying a third aircraft carrier to the Middle East along with additional Marines, an American official also told Israeli media on Thursday. And later, in the afternoon, Trump posted a new Truth Social message as follows:

The USS Theodore Roosevelt is en route to US Central Command's (CENTCOM) area of operations after having just left San Diego this week. It is expected to relieve the Japan-based USS George Washington, which entered regional waters in mid-August.

But both carriers could also stay on extended deployments. The WSJ writes further:

The additional moves will further strain the U.S. Navy, however, which has experienced supply shortages and faced near-record deployments during the conflict. Iran has in recent weeks fired ballistic missiles at American warships. The crew of the Roosevelt is prepared for a longer-than-normal deployment as well, according to senior Navy officials.

Source: US Navy

Carriers which more frequently had Indo-Pacific deployments have been increasingly diverted to the Middle East in recent years, a trend which had only picked up steam amid tensions with Iran and the Houthis out of Yemen.

Also on Thursday Al Jazeera is newly reporting that three carriers will stay in regional waters, "By the end of November, three aircraft carriers and two landing groups will be deployed around Iran," a US official told the Qatar-based outlet.

And USNI News earlier detailed:

On September 28, USNI News reported that a U.S. defense official had confirmed the carrier’s departure from San Diego the previous day. Navy officials had also warned families that the deployment could exceed seven months, with eight months being used as the planning baseline.

Carrier Strike Group 9 includes Theodore Roosevelt, Carrier Air Wing 11, Destroyer Squadron 23, Information Warfare Squadron 9 and the Ticonderoga-class guided-missile cruiser USS Chosin (CG-65). Its embarked air wing brings together several combat and support aircraft. The strike component includes F-35C Lightning II fighters from VFA-86, F/A-18E Super Hornets from VFA-211 and VFA-25, and F/A-18F aircraft from VFA-154. VAQ-137 operates the EA-18G Growler for electronic warfare, while VAW-115 flies the E-2D Advanced Hawkeye for airborne surveillance and command and control.

Whether one of the carriers ends up leaving the theatre or not, the extra deployment does mean President Trump will have a wider range of options for more possible military actions against the Islamic Republic.

He has in a freshly published TIME interview this week reiterated that he may be escalating attacks on Iran after the November midterms if an acceptable deal can't be reached.

Tyler Durden Thu, 10/01/2026 - 15:30

Pages