Individual Economists

1% Of Companies Account For 80% Of OpenAI And Anthropic Spending - And It Just Stalled

Zero Hedge -

1% Of Companies Account For 80% Of OpenAI And Anthropic Spending - And It Just Stalled

Just 1% of companies account for 80% of all business spending on OpenAI and Anthropic, according to corporate card giant Ramp, which tracks payments across more than 70,000 U.S. businesses. Ramp lead economist Ara Kharazian, who flagged the figure in early September, noted that spending on the two AI labs is more concentrated than in any other software category the firm tracks.

Per capita, the biggest spenders are overwhelmingly venture-backed. According to Ramp's summer report, the median VC-backed startup spent $76 per employee per month on AI - more than ten times the $7 spent at private equity-backed firms.

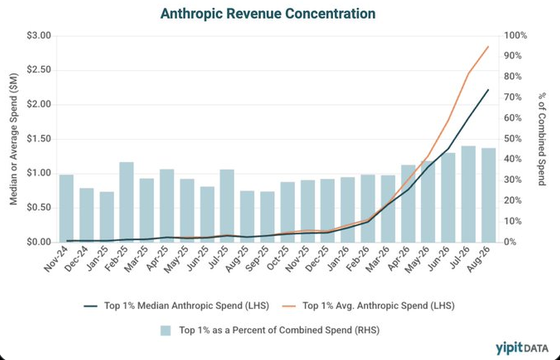
That top-heavy dynamic mirrors what YipitData uncovered at Anthropic specifically: the lab's top 1% of customers generated 46% of its revenue in August, nearly doubling from 25% a year earlier. How many of those whale customers, we asked at the time, are funded by the very same VCs backing Anthropic?

Anthropic's IPO prospectus - the updated version of which we dissected yesterday - confirms the concentration at the very top: just two unnamed customers generated nearly a quarter of its 2025 revenue, according to Reuters. Their identities aren't hard to guess. Last year, two AI coding tools - Cursor and Microsoft's GitHub Copilot - drove roughly $1.2 billion of Anthropic's $5 billion annualized revenue run-rate, as VentureBeat reported.

Follow the money. Cursor's parent company, Anysphere, raised $2.3 billion at a $29.3 billion valuation last November in a round co-led by Accel and Coatue, alongside Thrive Capital, Andreessen Horowitz, Nvidia, and Google. Three months later, Coatue and Singapore's GIC led Anthropic's massive $30 billion Series G, with Nvidia again participating. Coatue's cash flows into Cursor, Cursor spends it on Claude tokens, those tokens book as Anthropic revenue, and that revenue underwrites the markups on Coatue's Anthropic stake.

Even the scorekeeper is inside the loop. Ramp itself raised $1.85 billion at a $60 billion valuation last week in a round led by Dragoneer, Thrive, Founders Fund, Sands Capital, and Avenir Growth. Its cap table also features Coatue, D1, ICONIQ, GIC, Fidelity, T. Rowe Price, General Catalyst, and Lightspeed - every single one of which, alongside Dragoneer and Founders Fund, backed Anthropic's Series G.

Volumes Up, Dollars Flat

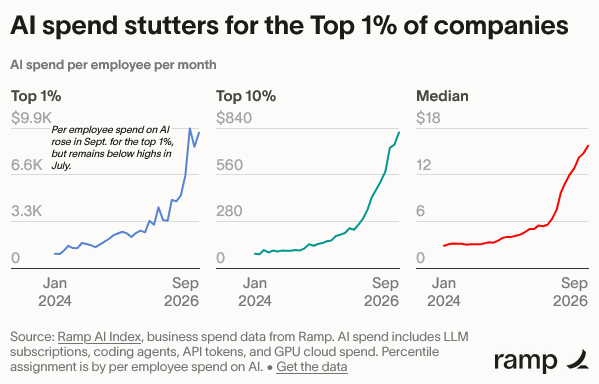
Yet it is Ramp's own economist who is documenting the cracks in the facade. In his October AI Index - pointedly titled "Cracks in the AI Thesis Part 3" - Kharazian reported that the top 1% of AI-spending firms shelled out $9,568 per employee in September. While that was up 11.7% from August, it remained 3.1% below July's peak of $9,873.

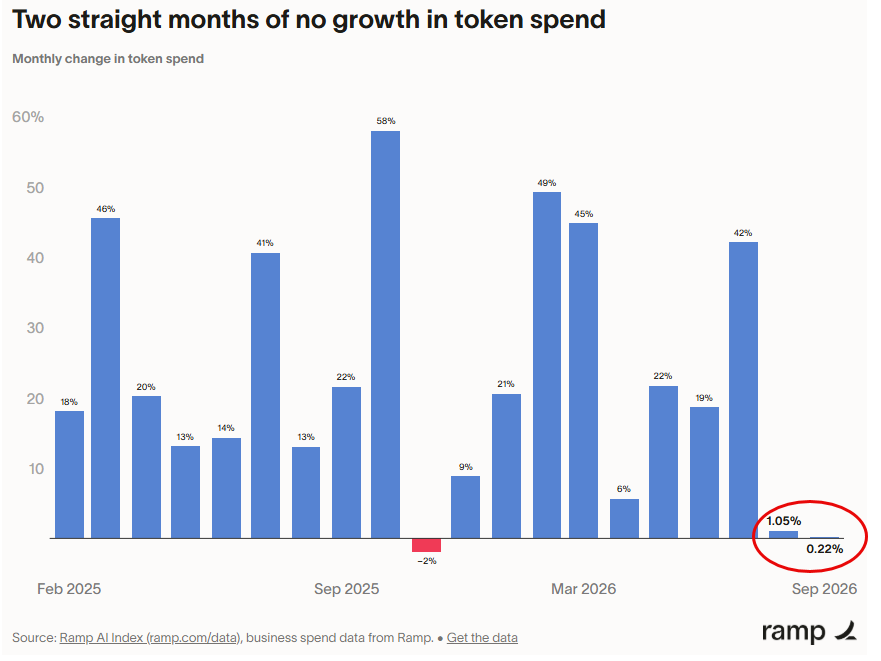
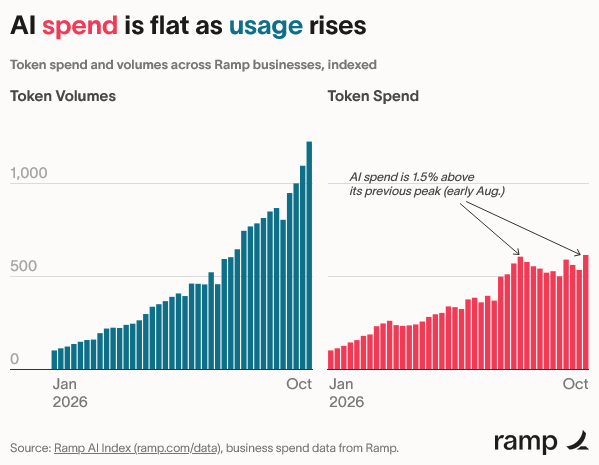
Across the broader cohort, the stall is even starker. In August and September, Ramp recorded "two straight months of virtually no growth in token spend," even as raw token volumes continued to climb.

Total dollar spend did eke out a new high in early October, but cleared its previous August peak by a paltry 1.5%.

Source: Ramp Rate

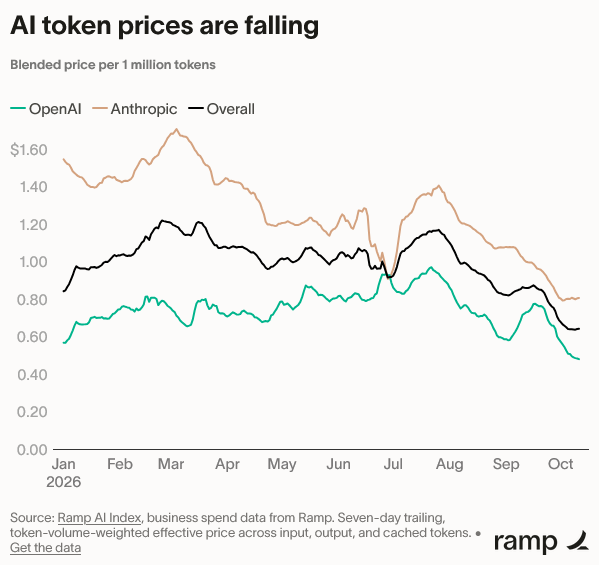
The culprit, according to Kharazian, is deflation: "the main driver is price declines at the frontier, in addition to efficiency and quality improvements for models across intelligence levels, that are driving the blended price per million tokens down."

Source: Ramp Rate

Nor have the AI labs been able to lock in their biggest customers. Asked whether OpenAI and Anthropic are using enterprise contracts to guarantee revenue, Kharazian noted that buyers hold all the leverage. Enterprise deals are rarely signed on the assumption of higher-than-normal spend, and when they are, "the labs are willing to provide concessions in the form of discounts on models from the sticker price." His takeaway: "These contracts could contribute to price cuts without driving additional volume."

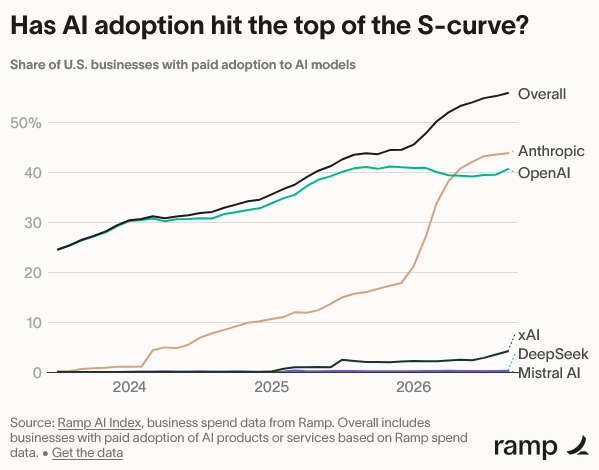
The customer base isn't widening much, either. Paid AI adoption across Ramp's corporate network nudged up just 0.62 percentage points to 55.9% in September. "It feels like we're at the top of the S-curve," Kharazian wrote, "where the growth in the market will have to come from more intense adoption rather than more customers."

Source: Ramp Rate

Anthropic Joins The Price War

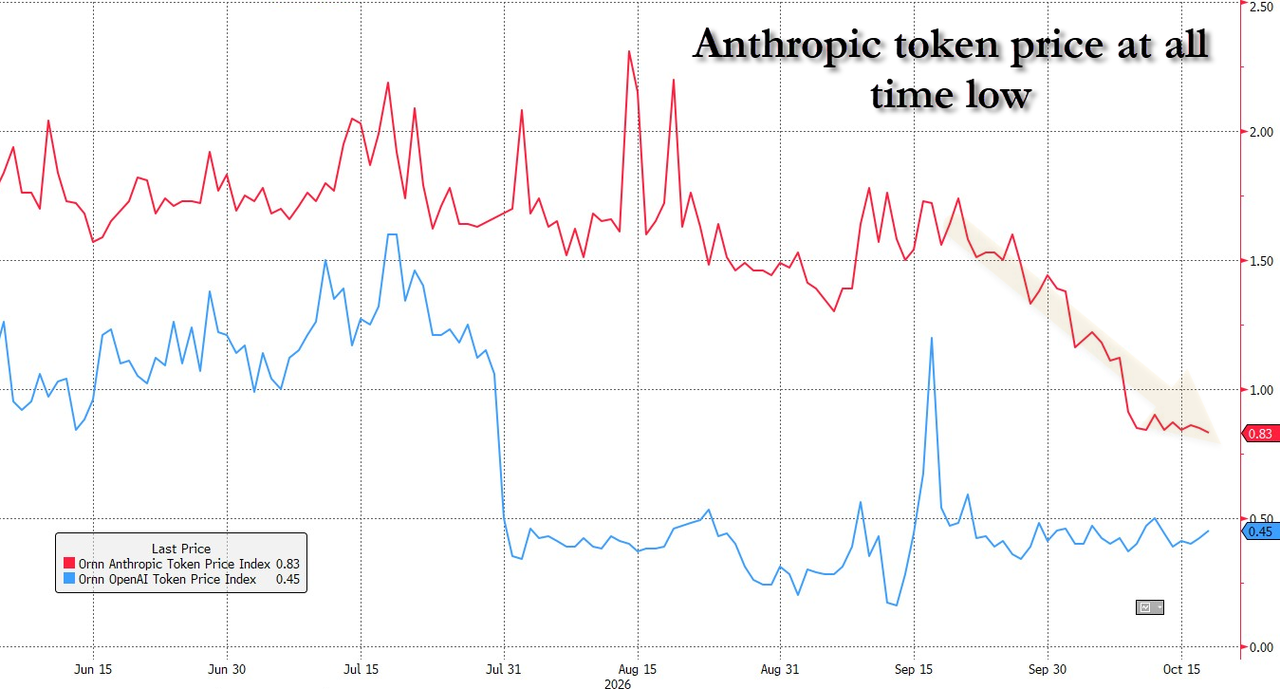
Meanwhile, Anthropic's realized token price has been cut in half in just a month. The Ornn Anthropic Token Price Index - which measures the actual dollars customers pay per token consumed - has cratered to $0.83 per million tokens from over $1.70 in mid-September, marking a record low since the benchmark launched in June.

Even after that plunge, Anthropic remains pricier than OpenAI, whose index sits at $0.45. OpenAI's realized pricing collapsed in late July after it slashed rates on its GPT-5.6 Luna and Terra models by up to 80% - just three days after Chinese lab Moonshot released the open weights for Kimi K3, the model blamed for sending chip stocks into a bear market earlier that month. OpenAI has since reportedly leaned toward delaying its IPO until 2027.

Jevons Isn't Riding To The Rescue

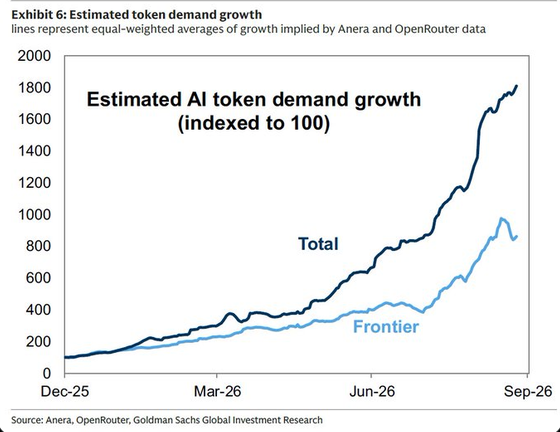
The bulls' reflex answer to relentless price cuts is Jevons paradox: make tokens cheap enough, and usage will explode so fast that total revenue rises anyway. The data isn't cooperating. In a Sept. 25 note, Goldman Sachs warned that "token demand growth will need to outpace declining token prices to support continued growth in investment spending," noting that while "frontier models are currently a key source of demand for hyperscaler compute," cheap open-source rivals are rapidly gaining ground. By Goldman's estimate - built on Anera and OpenRouter data - total token demand has surged roughly 18-fold since December, but demand for high-margin frontier models has grown only half as fast.

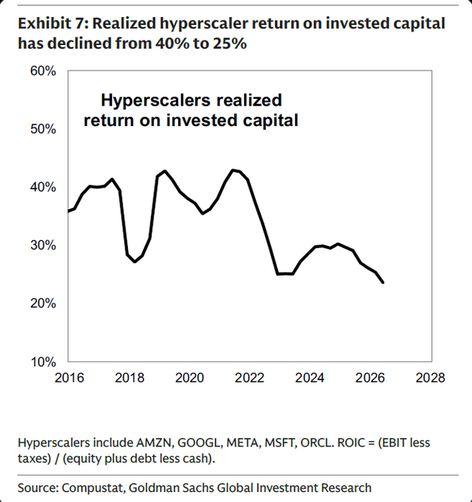
That margin squeeze is now flowing directly upstream to the companies building the data centers. Goldman calculates that realized return on invested capital (ROIC) across Amazon, Alphabet, Meta, Microsoft, and Oracle has fallen from 40% to 25% - the lowest reading in its dataset going back to 2016.

On Tuesday - the same day Citadel's Ken Griffin told Bloomberg that markets are "almost certainly" in an AI bubble - Apollo chief economist Torsten Slok diagnosed the underlying demand problem. "Silicon Valley operates on the premise that compute demand is unlimited, yet the recent slowdown in token spending growth suggests that this appetite may exist only when compute is effectively free," Slok wrote, citing Ramp's figures. Instead of inelastic hunger, compute faces "a flat, highly price-sensitive demand curve, where even modest changes in token prices can drive buyers to throttle usage or substitute cheap open-source alternatives."

"Ultimately, the number-one variable governing the viability of data center construction models is not physical capacity or power; it is the actual price users are willing to pay for the compute being built," Slok concluded. Corporate buyers will only pay a premium if they can translate tokens into "higher top-line growth, bigger profit margins or substantial cost savings, little of which is showing up at scale yet. Maybe that will come in the future. Maybe not."

Back in June, Ramp product director Adam Sommer boasted to a New York panel that "our largest AI spenders at Ramp are seeing their spend double month-over-month for the last several months." Three months later, the top 1% were spending less per employee than they had in July.

//-->


Tyler Durden Wed, 10/21/2026 - 14:30

Pollster Cited By NY Times, Other Outlets Admits It's Fake

Zero Hedge -

Pollster Cited By NY Times, Other Outlets Admits It's Fake

Authored by Zachary Stieber via The Epoch Times,

A purported company whose polls were listed by a slew of outlets, including The New York Times, has said that all but one of its surveys were not real.

Wedgewood Polling said in a statement on Oct. 20 that it was developed by people who previously worked in the poll sector and wondered how easy it would be for a fabricated polling firm to gain traction, be taken seriously, and "expose how little scrutinization exists in media and public commentary."

The entity said that its surveys often did not have any real data behind them, but they were nonetheless included in poll averages by the NY Times and some other outlets.

"Our fabricated numbers were given instant credibility across national media platforms - including being cited on air and in reporting by outlets such as MS Now," Wedgewood Polling said. "The ease with which unverified figures were absorbed into mainstream political narratives highlights a systemic breakdown in media vetting and data aggregation."

The surveys largely favored Democrats, including having Democrat candidate Abdul El-Sayed ahead of Republican candidate Mike Rogers in the race for a U.S. Senate seat in Michigan.

Wedgewood Polling conducted a single legitimate poll, in Nebraska, that served as a baseline to compare against fake data.

Wedgewood Polling said it did not intend to mislead the public or sway an election, and that the purpose was to spark changes in the polling and media industries.

Decision Desk HQ said on X on Wednesday that it removed 17 polls from Wedgewood Polling in light of the company's admission.

"As polling and averages are a component of our forecast model, we have rerun the model and all of our forecasts now reflect the removal of the fraudulent data," Decision Desk said. "The removal of these polls has not changed the projected seat totals or chamber control probabilities in the Senate or House."

Zachary Donnini, head of data science at VoteHub, another poll aggregator, said on X on Tuesday that he contacted Wedgewood Polling's head pollster after the company first appeared, and that the individual said he was a college student who had experience in the polling space. The conversation led to VoteHub including polls from the company on its website.

"A few years ago, I was a college student following politics as a hobby myself, so I try to give people in that position the benefit of the doubt," Donnini said. "It's disappointing to see how this has unfolded, because it's going to be a ... lot harder for the next college kid who's actually well-intentioned and super into politics to break into the space after this."

FiftyPlusOne, which had also included Wedgewood Polling surveys, said on Tuesday that it had sent questions about the polls to the company prior to the admission that most of its polls were fake. It said the questions prompted the disclosure.

Tyler Durden Wed, 10/21/2026 - 14:15

Are Bonds Pricing In A Fed Policy Mistake?

Zero Hedge -

Are Bonds Pricing In A Fed Policy Mistake?

Authored by Michael Lebowitz via RealInvestmentAdvice.com,

Imagine someone looking into their crystal ball and telling you at the beginning of October that the coming September CPI data would be higher than expected, and producer prices (PPI) would rise 1.3% for the month, well above the 0.5% forecast. On top of the bad inflation news, they also said more inflation pressure was brewing, with crude oil prices rising $10 through the first two weeks of the month. Based on that foresight, where would you guess the 10-year Treasury yield would be? To help you answer, the ten-year US Treasury yield was flirting with 5.25% on October 1. We bet most professional bond traders would have bet on 5.50% or even higher.

On October 14th, the 10-year Treasury yield surged after the CPI report, hitting 5.33% minutes after the release. A few days later, it was markedly lower at 5.03%. The 30-year yield fell by a similar amount. Bonds rallied into the teeth of the bad inflation data.

Mohamed El-Erian, ex CEO of PIMCO and renowned bond expert, asked the obvious question on X:

Why are US government bond yields falling despite hotter-than-expected CPI and PPI inflation prints?

He offered two valid rationalizations. In this article, we walk through his two AI-related explanations and add two of our own. Importantly, we emphasize one we think matters most: the bond market may be starting to price in the risk that the Fed is being pushed into a policy mistake.

Explanation One: A Flight To Quality Out Of Tech

El-Erian's first driver is a flight to quality "out of formerly high-flying tech stocks that are now coming under pressure."

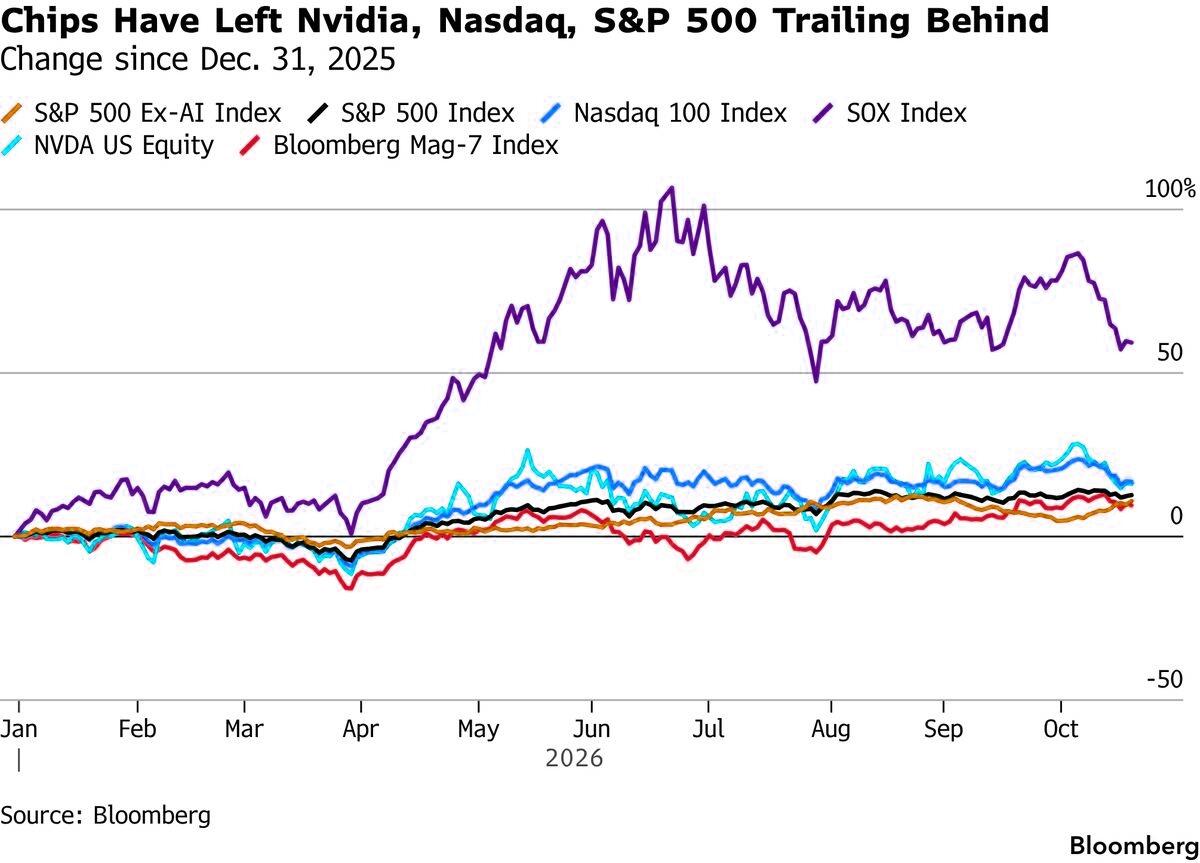
  • Many semiconductor stocks have been under pressure. The SOX semiconductor index fell almost 20% between October 1 and the PPI release on the 15th.
  • The Nasdaq, with a large semiconductor weighting, fell in sympathy. Foreign markets, including the tech-heavy Korea's KOSPI and Japan's Nikkei, were also down sharply.
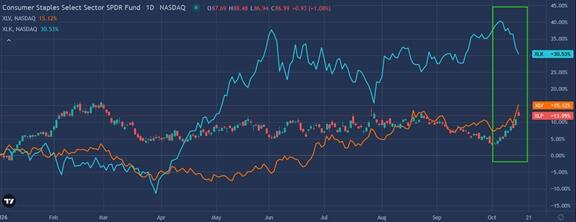
  • As we show below, healthcare (XLV), consumer staples (XLP) and other beaten-up value sectors have rallied since October 1, while technology (XLK) moved in the opposite direction. This rotation was primarily a flight to quality within the equity market, but El-Erian thinks it may have also sparked some bond buying.

Additionally, El-Erian notes there are "emerging pockets of credit stress in the most vulnerable segments." To his point, CoreWeave, a large data center provider, saw yields on its debt rise from 9% to 15%. Because investors are demanding such high yields for CoreWeave's debt and some of its competitors, there is a growing concern that CoreWeave might be the AI trade's canary in the coal mine.

Credit-related issues, such as those noted, often lead to a flight to quality from corporate bonds to US Treasuries.

Explanation Two: Is Tech Still A Growth Engine?

El-Erian's second driver carries broader macroeconomic implications. AI-related capital spending has been a primary engine of economic growth. If investors are less willing to fund the AI build-out, and if firms can't afford to fund it, does the economic growth outlook dim?

Saxo's Charu Chanana noted:

Investors are becoming less willing to finance AI infrastructure growth at any cost.

With 10-year yields above 5% and some AI-related credit spreads at junk bond levels, the cost of financing data centers has risen sharply. Less AI capex means less GDP growth, and lower expected growth argues for lower inflation, which results in lower long-term yields.

Explanation Three: Short Covering And Signs Of Significant Demand

Our first addition to El-Erian's list is short covering. The bond market entered October leaning heavily toward higher yields.

To wit, CFTC data showed asset managers added more than 100,000 contracts to their short 10-year Treasury futures exposure in the week ending September 22, one of the largest weekly additions since 2023, according to Bloomberg. Furthermore, open interest in 10-year futures rose in 13 of 14 sessions through late September, and in 5-year futures in 11 of 12 sessions. Those are consistent with new short positions being added as yields rose.

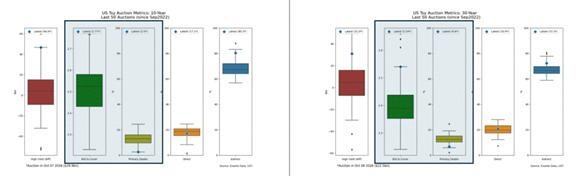
The 10- and 30-year Treasury auctions on October 7th and 8th appear to have foreshadowed the reversal. Many investors expected weak demand for the new supply of debt. They got the opposite. Per our Commentary Bond Auctions: You Never Hear About The Good Ones:

The 10-year note auction on Wednesday sold $39 billion at a 5.300% high yield. It stopped 1.7 basis points through the when-issued level, meaning it cleared much better than the market expected. Thursday's 30-year $22.5 billion bond auction was similar. The box plots below, courtesy of Exante Data, show how far outside normal both readings sit. The bid-to-cover measures the amount of dollars bid for every dollar sold. The 10-year came in at 2.77 compared to a twelve-month average of 2.51, higher than any of the last 50 auctions. The 30-year was 2.54 against a 2.40 median, at the upper edge of the last 50 auctions.

Primary dealer participation may be the most important auction statistic. The Treasury's primary dealers must bid and absorb whatever nobody else wants. When an auction has a high percentage dealer take, it means the auction struggled, and Wall Street got stuck with inventory. Dealers took a mere 2.5% of the 10-year, their lowest share on record for the tenor, and 6.8% of the 30-year. Indirect bidders, largely foreign central banks and domestic institutions, took 80.3% and 72.3%, both far above their averages.

When dealers are left buying little at Treasury auctions, as we saw, it means real money buyers are absorbing supply at these yields. While the bond market didn't rally on the strong auctions, it certainly put short sellers on notice that demand was robust at yields above 5%. The rising demand may have prompted Treasury-bond buying to cover short positions. Given how offside the market was, the buying created a circular effect, forcing more short sellers to cover.

Explanation Four: The Bond Market Smells A Policy Mistake

The bond market may be beginning to believe that this month's hot inflation data will force the Fed's hand toward more, not fewer, rate hikes, ultimately resulting in a policy error.

The yield curve's changing shape over the past two weeks supports our view. The 2yr-10yr yield curve was 57 basis points on October 7th. Following the CPI and PPI reports, it flattened to 32 basis points. That's a relatively large 25-basis-point decline in two weeks, with most of it occurring on the days of the inflation data.

When all yields decline, but long-end yields fall more than short-term yields, that is called a bull flattener. A market that expects the Fed to tighten into a weakening economy buys long bonds and flattens the curve. A market fearing runaway inflation should result in a bear steepener reaction.

The front end of the yield curve prices the odds of Fed rate hikes. The long end is pricing the consequences.

Reasons To Fret A Policy Mistake

There are a few reasons we think the bond market should worry about the Fed.

First, the recent increase in inflation is largely a supply shock. Gasoline and diesel prices are rising because of the conflict with Iran, not because consumers are overheating. The Fed can't produce oil, but it can reduce demand for everything else.

Second, the labor market is weak. September payrolls rose just 29,000 and prior months were revised down by 60,000. Furthermore, the unemployment rate ticked up to 4.2% and real earnings are flat to slightly negative, leaving little evidence of an inflationary wage-price spiral.

Third, consumers are being squeezed. The most recent retail sales beat estimates at 0.8%, but gasoline sales drove most of the gain. To wit, the Control Group, which the BEA uses in its GDP calculation, rose only 0.1. Essentially, higher gas prices are crowding out other spending.

Fourth, Fed policy is already restrictive by the Fed's own math. The September rate hike raised Fed Funds to 3.75% to 4.00%, above the Fed's own estimate of the longer-run neutral rate at 3.20%. The median dot plots in the latest Fed Economic Projections (SEP), along with commentary from some Fed members, suggest another rate hike or two is quite possible.

Lastly, financial conditions are tightening. The 10-year yield above 5%, 30-year mortgage rates near 7.50%, an 18-month high in the dollar, and widening credit spreads are all doing the Fed's work. Fed Funds rate hikes make financial conditions even more restrictive.

The Hawks Case

To be fair, Fed hawks have a rational case for raising rates further. The recent CPI report showed broader price increases across many goods and services, core PCE running near 3%, and, probably more importantly, inflation has been above the Fed's target for more than five years. The Fed is rightly concerned about inflation expectations becoming unanchored.

But the bond market is not voting on whether inflation is too high or what it has been. It is voting on where inflation will be and whether the Fed's inflation cure will not only heal the patient of its inflation problem but bring on recessionary side effects.

Summary

Falling bond yields amid hot inflation data are not a paradox. They reflect a flight to quality out of tech, doubts about AI as a growth engine, the unwinding of crowded short positions, and strong demand.

Most importantly, in our view, they signal concern that the Fed is responding to an energy-driven inflation shock and that inflation has been too high for too long, tightening into a slowing economy. The shape of the yield curve and the direction of long-end yields offer a good roadmap for what may happen next.

Tyler Durden Wed, 10/21/2026 - 13:45

China 'Already Preparing' Trilateral Summit With US & Russia, Likely For November: Kremlin

Zero Hedge -

China 'Already Preparing' Trilateral Summit With US & Russia, Likely For November: Kremlin

There's lots of talk of big trilateral meetings in the middle of this week, as some major parallel diplomacy is currently happening in St. Petersburg.

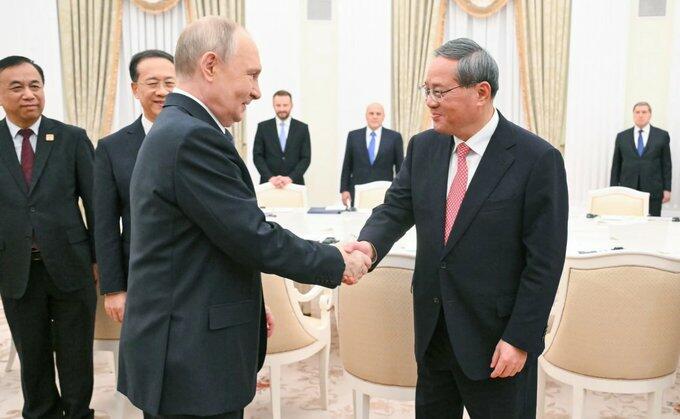
President Vladimir Putin's meeting with US special presidential envoy Steve Witkoff has wrapped up, but already China is also in the house. Significantly, Chinese Premier Li Qiang is second-highest-ranking official in the country's Communist Party (CCP) hierarchy, under President Xi Jinping. He's meeting with Putin just after the Witkoff summit

Putin aide Yury Ushakov has in comments to reporters revealed that China has already begun preparing a trilateral meeting among the leaders of Russia, the US and China.

He indicated that could happen on the sidelines of the Asia-Pacific Economic Cooperation (APEC) summit in Shenzhen "if circumstances are favorable." This would be in just under a month, scheduled for November 17-18, 2026.

Ushakov said: "Our Chinese friends, who are hosting the APEC summit, will deal or rather are already dealing with its [the trilateral meeting] preparation. And if circumstances are favourable, they, our Chinese friends, will of course include this meeting in the program of events in Shenzhen."

Some further details laid out in Ushakov's briefing, via Bloomberg:

  • Potential meeting has been worked on at expert level, Ushakov says
  • Meeting would require all three leaders to be in same place at same time
  • Experts have outlined key topics for potential trilateral meeting at APEC summit
  • A single meeting between Putin, Trump and Xi wouldn't be enough to resolve war in Ukraine, Ushakov says.
via Sputnik

One journalist and pundit described of Wednesday's remarkable events in Russia's second-largest city:

There’s an extraordinary diplomatic coincidence in St. Petersburg today. Trump’s envoy Steve Witkoff is arriving to discuss peace in Ukraine, just as Chinese Premier Li Qiang, second only to Xi Jinping in Beijing’s political hierarchy, visits the city.

Peter the Great built St. Petersburg as Russia’s window onto the rest of Europe. Three centuries later, it will see Russia, America and China can discuss Europe’s affairs without troubling the EU.

Ukraine's Zelensky has meanwhile tried to insist that his country's fate cannot be determined without him or Ukrainian representatives at the table.

On this, Trump said earlier this week: "I'm supporting stopping the war between Russia and Ukraine... Frankly, Zelensky is not helping matters much. I think he doesn't want to stop it. I want to see people not die."

President Trump has meanwhile suggested that any future trilateral meeting would also focus on nuclear proliferation issues. Secretary of State Rubio has further hinted at this...

We detailed Sunday that Putin reportedly first floated the idea of a trilateral meeting in an Oct. 9 phone call with Trump. That conversation also produced a deal for the US to buy Russian diesel fuel and facilitate its sale on the global market. Kremlin spokesman Dmitry Peskov confirmed that discussions were taking place over a potential meeting. 

A potential three-way dialogue on Chinese soil would mark a big step for Xi in his efforts to elevate China’s role as a diplomatic power broker, said analysts who study China. Russian officials proposed the idea to Beijing through diplomatic channels and the Chinese side has indicated it wouldn’t object if Trump is on board. 

Russian media captures some of Wednesday's high level dialogue:

In the wake of prior late Sunday reports, Trump declared that he is indeed open to participating in a trilateral meeting with Chinese President Xi Jinping and Russian President Vladimir Putin (but without Zelensky's involvement). Trump also offered that could be focused on denuclearization.

"I would do it" - Trump stated multiple times in Monday comments, stipulating that he'd like to see it happen if President Xi were on board, and saying it would likely be in China (since Xi just recently visited the US).

Tyler Durden Wed, 10/21/2026 - 13:30

Clinton-Nominated Judge Says DOGE Illegally Accessed Data On Government Workers

Zero Hedge -

Clinton-Nominated Judge Says DOGE Illegally Accessed Data On Government Workers

Authored by Zachary Stieber via The Epoch Times,

A federal judge ruled on Oct. 20 that a department aimed at making the government more efficient should not have been granted access to sensitive federal employee data.

Granting Department of Governmental Efficiency (DOGE) personnel access to government employee data contained in Office of Personnel Management systems violated the Privacy Act, which bars certain record disclosures and requires safeguards when disclosing other records, U.S. District Judge Denise Cote said in a 39-page ruling that granted plaintiffs final judgment.

"The defendants barely defend its legality, relying instead on what has happened since to argue that the case is moot and that prospective relief is unnecessary," wrote Cote, a judge for the U.S. District Court for the Southern District of New York.

Department of Justice lawyers had argued in court filings that DOGE agents needed access to the records as part of an effort to modernize government systems. The government did not explain why the modernization efforts required access to the sensitive records containing personally identifiable information, according to Cote.

Lawyers had also said that the agents were granted access in case they needed the data later, but the government has never linked the access to any of the agents' duties, the ruling stated.

The Department of Justice did not respond to a request for comment by publication time.

President Donald Trump established DOGE shortly after taking office in 2025, and DOGE employees worked with various agencies to streamline operations.

Cote in June 2025 entered a preliminary injunction blocking the department from accessing federal employee records as the case proceeded, finding violations of the Privacy Act.

Professional groups, including the Association of Administrative Law Judges, brought the case and said DOGE's disclosure of employee personal data was illegal.

Twenty DOGE employees received access to Office of Personnel Management (OPM) systems from Jan. 20, 2025, to March 6, 2025, according to court documents. Some worked for OPM, but others received paychecks from other agencies.

Certain DOGE personnel had access to the systems through September 2025.

Only one of the agents remains at the office, according to the government, and he does not have access to systems containing personal employee data. DOGE itself shut down in July 2026.

The Office of Personnel Management has updated its disclosure policies, including specifying that only office employees and contractors, not detailees, can access those systems.

Cote said the updates were admirable but seemed to track with deadlines in the litigation. She also said the case was about misconduct stemming from "the failure of particular individuals," not deficient procedures.

Cote said it's unclear whether any relief is necessary at this juncture, given the developments surrounding DOGE and the office. She said she would be asking the parties to offer views on what relief, if any, is appropriate.

"In the meantime, the parties are encouraged to confer and explore whether they can reach an agreement on an appropriate resolution," she said.

Tyler Durden Wed, 10/21/2026 - 13:15

Undercover Video Throws El-Sayed's Senate Campaign Into Chaos

Zero Hedge -

Undercover Video Throws El-Sayed's Senate Campaign Into Chaos

Authored by Matt Margolis via PJ Media,

Abdul El-Sayed's Senate campaign is in full-blown panic mode after an undercover O'Keefe Media Group video caught one of its field organizers claiming the candidate takes overseas donations.

The video dropped on Monday. By the end of the day, the Michigan Democrat Party had confirmed that the organizer who spilled the beans about the campaign's illegal donations, Abdoul Beckwith, has been fired. No investigation, no review, no waiting to see how the story played out. Party officials cut him loose almost immediately, and the El-Sayed campaign rushed out a statement calling his comments "untrue," "wildly misinformed," and "not reflective of the campaign" while insisting it fully complies with Federal Election Commission rules.

Right. Sure. They would say that, wouldn't they?

So, what did Beckwith say?

Talking with an undercover journalist who posed as a volunteer at the campaign's Detroit operation, he dropped a true bombshell. El-Sayed "has people from overseas that donate to him," Beckwith said. Asked whether that was allowed, he acknowledged it wasn't.

He then described how the money supposedly moves, with family members or other intermediaries acting as conduits. "Everybody does it," Beckwith said.

But that isn't even the worst thing Beckwith revealed. When the undercover journalist raised the subject of Hamas, he explained why El-Sayed has to tread carefully around terrorist groups.

"He can't just say, you know, 'No, I don't support Hamas, you know, I reject all of them,' because he's going to lose the people that brought him up in the first place," Beckwith said. He made a similar point about the Muslim Brotherhood and worried that white and Jewish advisers could sway El-Sayed or "hijack" his positions.

Have you noticed this is a common theme among Democrat campaigns? Radicals at heart, they get nominated by primary voters and then spend the general election campaign trying to convince the broader electorate they aren't who they really are.

Now the El-Sayed campaign is struggling to clean up this mess. And believe me, the panic has spread beyond the campaign itself. Left-wing influencer Brian Krassenstein immediately rushed to run cover.

"This is the biggest nothing burger in the history of nothing burgers," Krassenstein claimed in a post on X.

If it's nothing, why did they fire Beckwith?

Krassenstein kept going. "Some random field organizer says that Abdul Al-Sayed is getting money from overseas," he wrote, adding, "First of all a field organizer has no inside knowledge of a campaigns finances, meaning his likely making it up, nor is getting money from overseas illegal if they are American citizens."

Why would Beckwith make it up? He thought he was chatting with a fellow volunteer, not a reporter, and he had no reason to invent a scheme that could sink his own candidate. Notice, too, how Krassenstein hedges. If he truly believed El-Sayed takes no overseas money, why bother arguing that overseas money from Americans is perfectly fine? People build fallback positions when they suspect the first defense won't hold.

The El-Sayed campaign now has a huge problem on its hands, and it knows it. The campaign could end this by opening its donor records to an independent audit. It won't do that.

Tyler Durden Wed, 10/21/2026 - 12:45

Undocumented Student Enrollment In California Schools Takes A Nosedive

Zero Hedge -

Undocumented Student Enrollment In California Schools Takes A Nosedive

Authored by Bryan Hyde via American Greatness,

New immigrant and undocumented student enrollment has dropped sharply in California schools and public universities, driven by decreased border crossings and increased federal immigration enforcement.

Breitbart reports that the major drop in the number of kids of illegal migrants enrolled in California's schools is saving the state millions in education budget dollars.

The number of "newcomer" students born outside the U.S. who have been enrolled for 3 years or fewer has dropped from a record high of 236,958 in 2024-25 to 228,780 in 2025-26, with further declines anticipated.

From 2017 to 2024, the Oakland Unified School District took in an average of 1,300 extra so-called "newcomer" students each year.

However, in 2025 the district only saw 498 "newcomers" enter the schools, and this year that number fell to 212, forcing the district to close almost two-thirds of its newcomer programs, according to EdSource.

L.A. schools recorded a drop of 46.5 percent in "newcomer" students, and San Juan Unified lost 13.6 percent of their "newcomer" students.

The decline has also impacted higher education within the University of California system as undocumented student enrollment backed by state financial aid dropped by 51 percent, falling from 1,181 to 579 students, according to Georgetown University.

California State University reports undocumented student enrollment receiving state aid fell by 48 percent, dropping from 2,219 to 1,148 students, influenced by restrictions on DACA and labor market exclusions.

Lower rates of cross-border migration have directly reduced the pipeline of newly arriving school-age children and the amount of education dollars directed at "newcomers" will necessarily see huge cuts in funding over the next few years.

Due to declining enrollment numbers, the infrastructure and administrators for these programs will also become unnecessary and the taxpayers will not have to direct as much money into school budgets.

Sam Finn, executive director of the California Newcomer Network told EdSource, "We're about to reach a cliff where we'll have had a couple years without significant entries."

Other contributing factors to the decline include federal policy changes and heightened immigration operations which have led families to avoid public spaces or relocate, compounding pre-existing statewide trends like falling birth rates and high housing costs.

Tyler Durden Wed, 10/21/2026 - 12:15

Federal Agents Arrest 131 People With Alleged Gang Ties

Zero Hedge -

Federal Agents Arrest 131 People With Alleged Gang Ties

Authored by Kimberly Hayek via The Epoch Times,

More than 100 gang members were arrested in less than a week, including members of MS-13 and Tren de Aragua, federal officials announced on Monday.

From Oct. 4 to Oct. 10, agents took 131 alleged gang-affiliated individuals into custody, according to the Department of Homeland Security (DHS). Of those, 22 were associated with MS-13 affiliates, and 13 were tied to Tren de Aragua, the department said.

Immigration and Customs Enforcement (ICE) Enforcement and Removal Operations (ERO) made 129 of the arrests, while Homeland Security Investigations (HSI) handled the remaining two.

"The best that America has to offer are on the frontlines every day to ensure that the worst of humanity cannot threaten or harm innocent Americans," DHS Secretary Markwayne Mullin said in a statement about the gang member arrests.

"Under President Trump's leadership, we are smashing the gangs and cartels, making it impossible for them to do business in America, and removing their members from our country. Arresting and deporting illegal aliens, especially gang members, is how we make America safe again."

Among those arrested is Gustavo Adolfo Flores-Ramirez, an alleged MS-13 member from El Salvador. Flores-Ramirez is wanted in El Salvador for aggravated homicide, aggravated femicide, rape of a minor or incapacitated person, illegal handling of firearms, illicit grouping, and crimes involving public peace. He was arrested by ICE in Las Vegas on Oct. 14. Flores-Ramirez had been arrested by Border Patrol in 2021, deported to Mexico, and then re-entered illegally.

Jose Luis Perez-Arrias, an alleged Venezuelan Tren de Aragua member described as a suspected hitman, was arrested in Tallahassee, Florida, on Oct. 14. He entered through Texas in October 2023, and the Biden administration released him, according to DHS.

Emerson Jossiel Calderon-Hernandez, an alleged MS-13 member from El Salvador, was taken into custody in Washington on Oct. 13. His criminal history includes a conviction for second-degree assault and arrests for attempted first-degree murder, attempted second-degree murder, armed robbery, first-degree assault, reckless endangerment, and false imprisonment, DHS said. He entered through Texas in August 2012 and was released under the Obama administration.

On Oct. 13, agents in Denver arrested a 14-year-old Venezuelan associated with Los Piratas, a Tren de Aragua faction. He unlawfully possessed a Glock 48 pistol and faces charges of first-degree murder, criminal attempt with extreme indifference, first-degree assault with extreme indifference, first-degree kidnapping, aggravated criminal extortion, illegal discharge of a weapon, and conspiracy, according to DHS.

Gang Arrest Totals

Since Jan. 20, 2025, ICE has arrested 1,965 MS-13 affiliates and 1,553 Tren de Aragua affiliates.

In June, DHS said ICE had arrested more than 10,000 gang members so far during President Donald Trump's second term.

"These 10,000 criminals committed heinous crimes, including murder, assault with a deadly weapon, drug trafficking, racketeering conspiracy, robbery, and extortion," DHS stated.

Mullin said many of the 10,000 arrested gang members were released into the United States under the Biden administration.

Earlier, DHS reported that ICE arrested about 7,000 gang members during the first year of the term.

Tyler Durden Wed, 10/21/2026 - 11:45

China Imposes Export Curbs On Drones, Heavy Machinery

Zero Hedge -

China Imposes Export Curbs On Drones, Heavy Machinery

Authored by Dorothy Li via The Epoch Times,

China said on Monday it would expand curbs on drone exports and restrict the sales of some heavy machinery to "sensitive countries" with which the communist regime has disputes.

Exporters will need a license to ship certain types of drones, such as those capable of traveling more than 300 km (186 miles) or flying beyond the natural line of sight, China's Ministry of Commerce said in an Oct. 19 statement, citing national security grounds. The drones' engines, operating systems, and technologies used for manufacturing will also be subjected to controls.

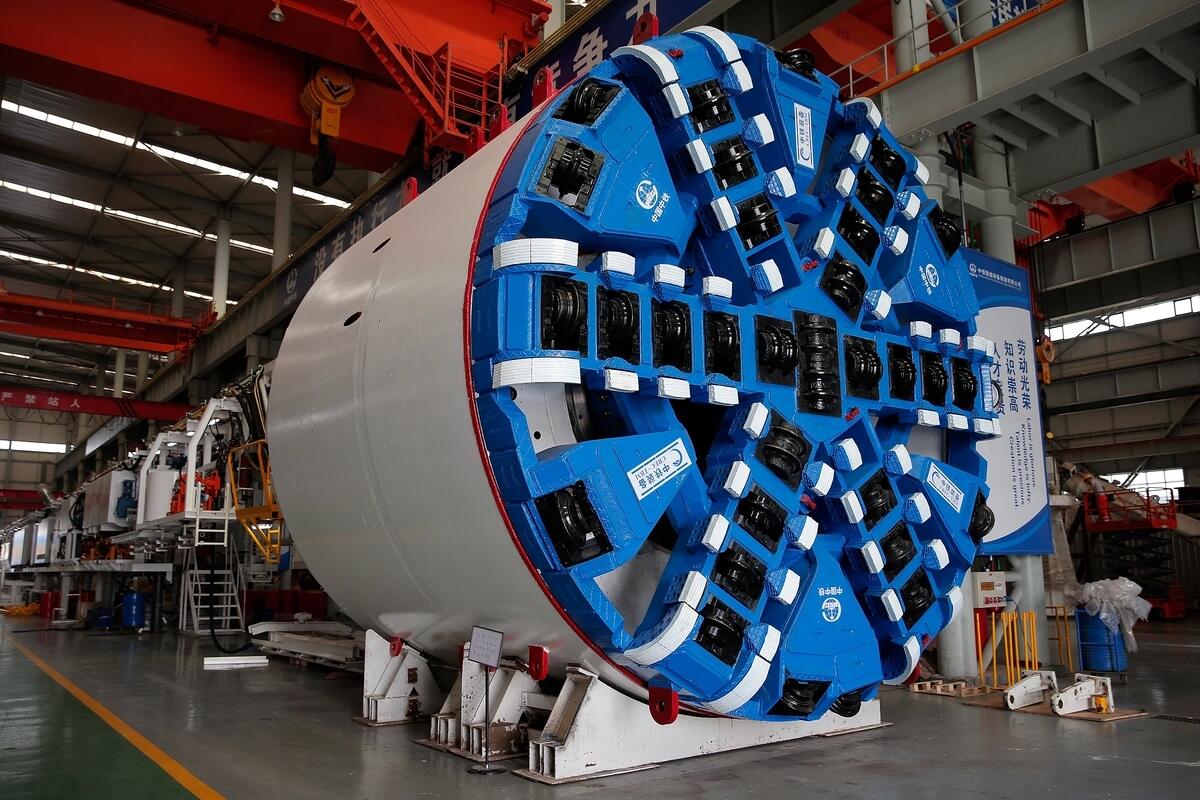
Other affected products include some tunnel-boring machines, walking excavators, and high-altitude concrete-spraying machines - all sophisticated machinery for building railway and road tunnels through mountains, according to a separate press release.

Decades of investment have helped China become the world's major supplier of tunnel-boring machines. Chinese media have long touted that the country makes 70 percent of such machines around the globe. Among the leading manufacturers are state-owned China Railway Engineering Equipment Group, whose website said its machines are delivered to overseas projects in 36 countries, including Italy, Australia, and Peru.

Separately, the regime's commerce ministry announced export restrictions on key components of dredgers, including heavy-duty pumps used to scoop up mud and sand from the seabed.

Overseas companies and individuals will be barred from transferring China-sourced dredger-related items to "sensitive countries and regions that have disputes with China," the ministry said.

Beijing didn't name any specific country. But some analysts, including Brookings Institution fellow Kyle Chan, said India could be a likely focus. The two neighbors have longstanding border disputes that escalated into war in the 1960s.

China has invested heavily in developing its dredger industry, with state-owned CCCC Dredging being the country's leading producer and contractor.

All three new export restrictions will be enforced beginning Nov. 18.

A ministry spokesperson said these newly added products have "clear dual-use characteristics," meaning they can be used for both military and civilian purposes. Chinese officials had already notified trading partners through export-control dialogue mechanisms ahead of the announcement, the spokesperson added.

The ministry also signaled tightened checks on dual-use products. Customs officers will detain goods and question export operators if they suspect a shipment includes controlled items. Exporters will have seven working days to respond and submit required documents such as contracts and receipts. The rules take effect immediately and also apply to cross-border e-commerce, mail, and travelers' luggage.

The expanded export controls came amid global concerns over reliance on China for raw materials and industrial products.

China restricted shipment of rare earths - a sector in which it accounts for about 70 percent of global supply - in late 2025 ahead of trade negotiations with the United States, and again earlier this year amid tensions with Japan. The sweeping restrictions have prompted the United States and other major economies to diversify the source of the supply chain critical for products ranging from smartphones and medical imaging to military equipment.

Last week, the commerce ministry unveiled sweeping export controls on dozens of technologies related to artificial intelligence as Beijing tightens controls on the strategic industry amid rivalry with the United States. Also added to the export-control list were biotechnology and technologies used to make solar equipment.

Senior U.S. and Chinese officials are set to hold a talk by November under a mechanism established at a September summit between U.S. President Donald Trump and Chinese leader Xi Jinping in Washington.

Tyler Durden Wed, 10/21/2026 - 11:20

Stablecoins Move $400M An Hour, With 73% Of Volume Outside Banking Hours: Coinbase

Zero Hedge -

Stablecoins Move $400M An Hour, With 73% Of Volume Outside Banking Hours: Coinbase

Authored by Nate Kostar via CoinTelegraph.com,

Stablecoins moved more than $400 million an hour in adjusted transfer volume during the third quarter of 2026, as quarterly activity reached $891 billion, more than quadrupling since early 2023, according to a new report commissioned by Coinbase.

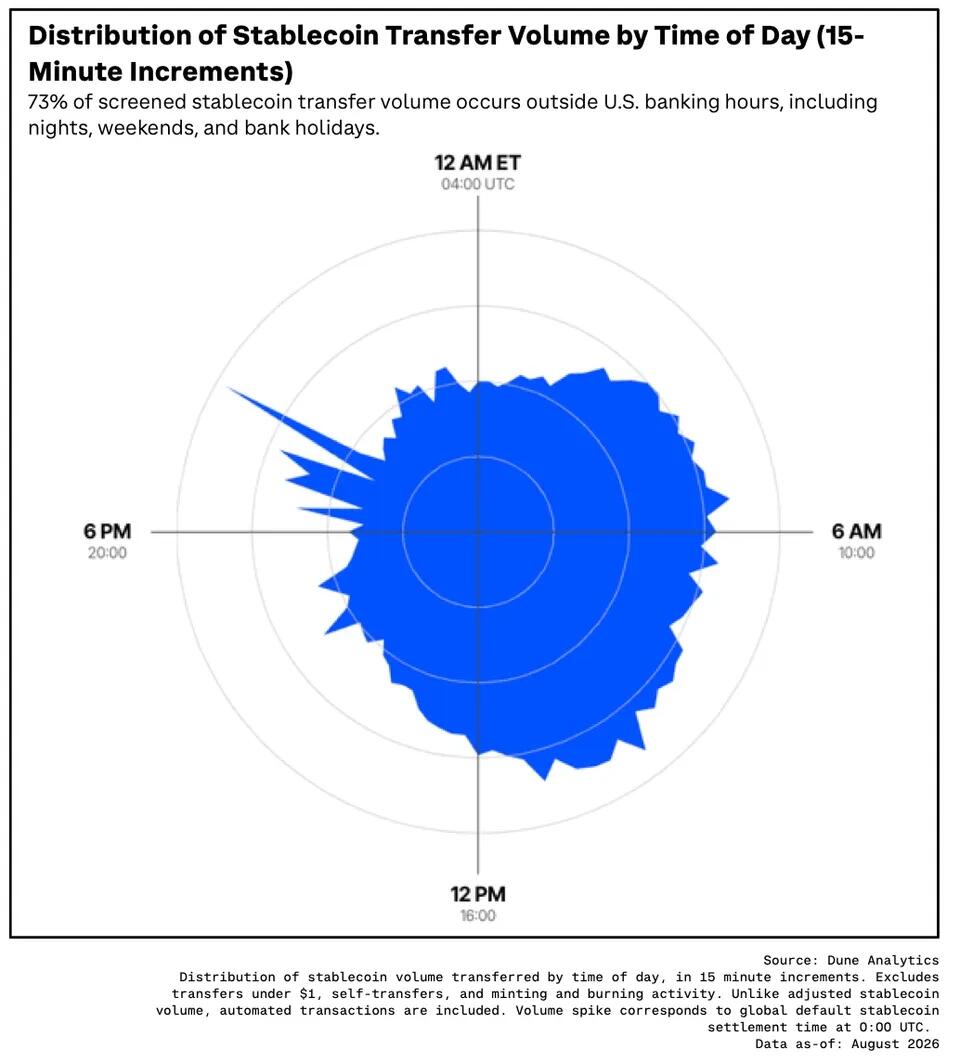
The report found that 73% of screened stablecoin transfer volume occurred outside US banking hours, including nights, weekends and holidays.

Distribution of stablecoin transfer volume by time of day. Source: Coinbase and The Block Research, via Dune Analytics

Seven of the 10 largest US banks have tested stablecoins or tokenized deposits for settlement, while 30% of mid-market companies conducting cross-border business are using or piloting stablecoins, up from 10% in 2024. Business-to-business payment volume also rose 36% year over year.

Conducted by The Block Research, the findings identified 293 million blockchain addresses holding stablecoins, exceeding the combined number of cards issued by American Express and Discover, though researchers cautioned that addresses do not necessarily represent individual users.

The report also estimated that moving 80% of international transactions onto stablecoin networks could add $155 billion to global GDP annually and free up roughly $3 trillion in liquidity currently held by banks to support cross-border payments.

Those projections are based on hypothetical adoption scenarios rather than observed economic gains. Researchers also acknowledged that widespread stablecoin adoption could reduce bank lending, potentially offsetting some of the benefits of faster and cheaper payments.

Survey finds growing demand for crypto services at US banks

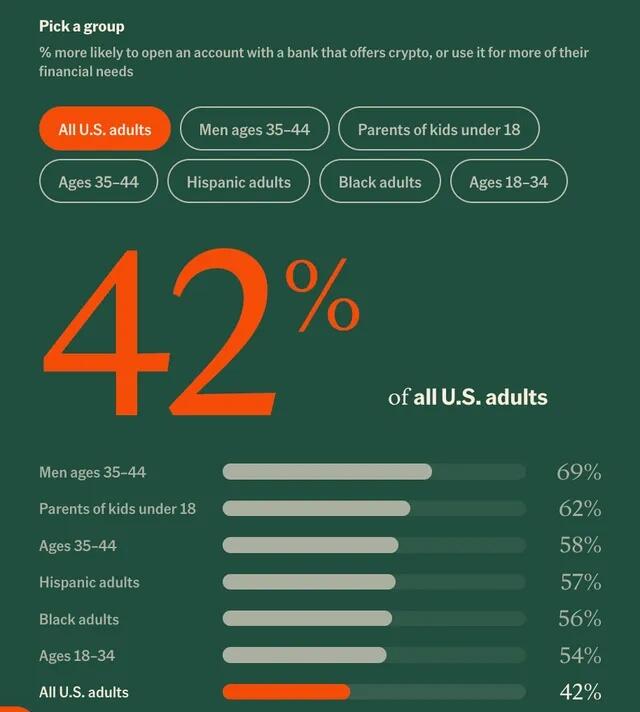
A separate survey released Monday by the National Cryptocurrency Association found that 42% of US adults, representing approximately 112 million people, would be more likely to open an account with a bank offering crypto services or use that institution for more of their financial needs.

The survey found that 18% of US adults would like to buy or use stablecoins through their primary bank or financial institution. However, 64% said their bank, credit union or financial advisor had never raised the topic of cryptocurrency, while 43% did not know whether their bank offered crypto services.

Americans' interest in crypto banking services by demographic group.
Source: National Cryptocurrency Association, 2026 Crypto at the Bank Report

Stablecoin market cap remains flat despite rising transaction volumes

Despite increasing transaction activity, the stablecoin market capitalization stood at $301.42 billion on Tuesday, a decline of about 0.6% from $303.14 billion on Oct. 20, 2025, according to DefiLlama data.

Last week, Standard Chartered pushed back its forecast for the stablecoin market to reach $2 trillion from 2028 to 2030, citing slower supply growth. Citi, meanwhile, has projected a $1.9 trillion market by 2030 in its base case, with a bullish scenario reaching $4 trillion.

Tyler Durden Wed, 10/21/2026 - 10:50

WTI Flat After Another Crude Draw, Distillates Stocks At Seasonal Record Lows

Zero Hedge -

WTI Flat After Another Crude Draw, Distillates Stocks At Seasonal Record Lows

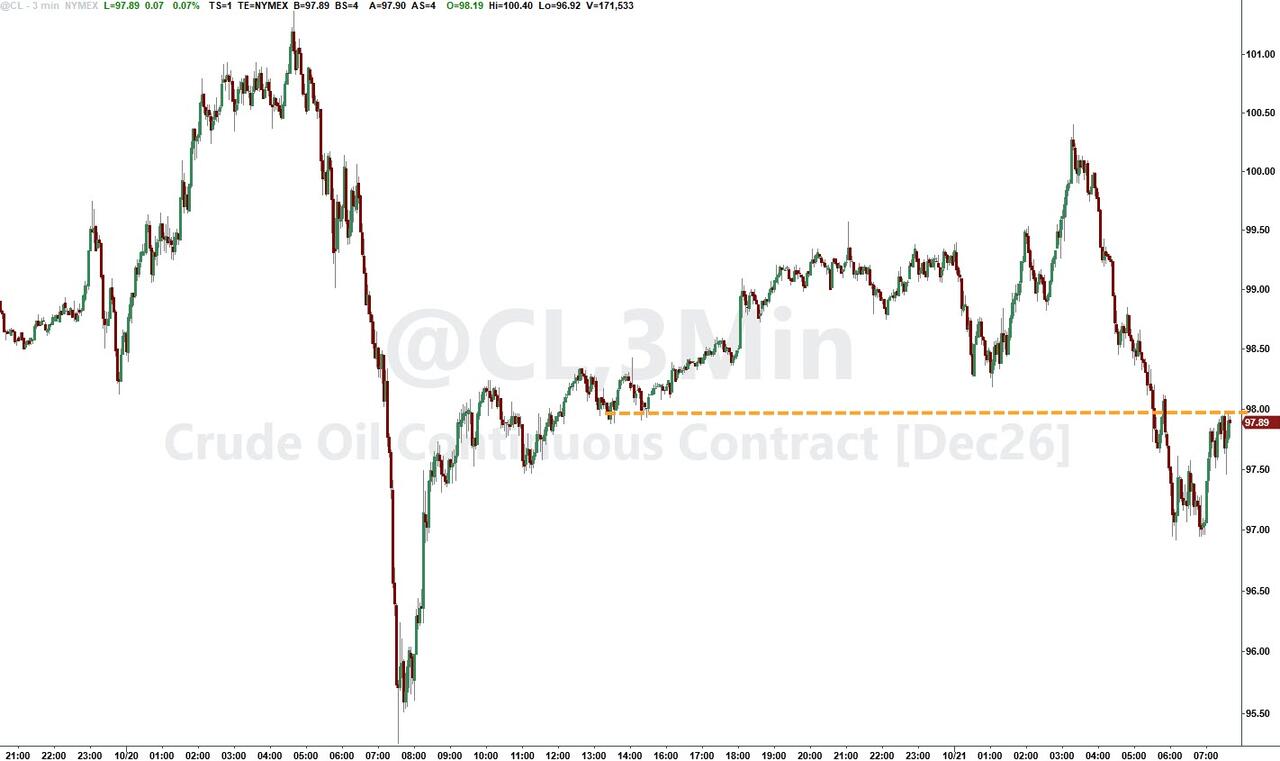
Oil prices are flat this morning, reversing earlier gains that pushed Brent crude above $110 a barrel - 5 month highs (and WTI back above $101), as traders weighed a recovery in Middle East oil exports against persistent threats to shipping through the Strait of Hormuz and attacks targeting Saudi Arabia..

Specifically, shipping risks remained elevated as Iran's IRGC said Tuesday that two oil tankers caught fire after striking mines south of the Strait of Hormuz.

“High exports do not necessarily mean lower risks,” said Arne Lohmann Rasmussen, chief analyst at A/S Global Risk Management. “Shipping remains exposed to attacks, while exceptionally high freight rates and insurance premiums make transporting oil expensive.”

Regional tensions also persisted.

The Saudi-led coalition said Wednesday that it intercepted drones launched toward the kingdom, including one targeting the Eastern Province, a major oil-producing region.

Diplomatic efforts to end the conflict are reportedly continuing. Qatar's Foreign Ministry said Tuesday that contacts, visits and exchanges of messages between Washington and Tehran remained ongoing, amid efforts to reopen the Strait of Hormuz and end the regional escalation.

With hurricane shut-in effects fading, API reported inventory draws across the board (except a small build at Cushing).

API

  • Crude -4.9mm

  • Cushing +936k

  • Gasoline -2.0mm

  • Distillates -2.6mm

DOE

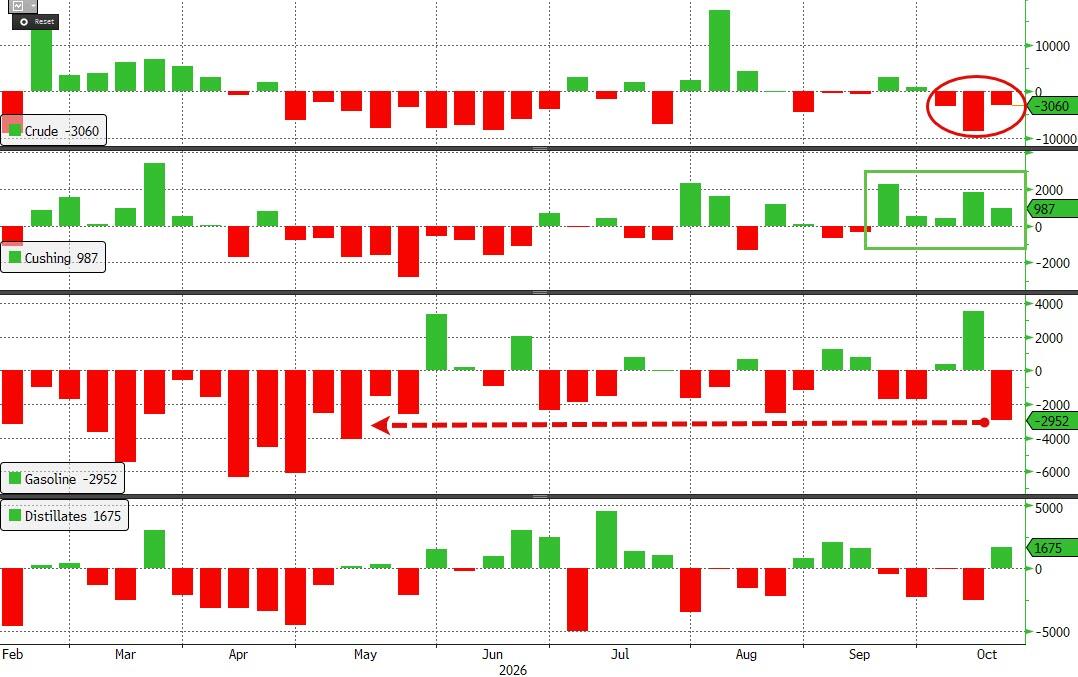
  • Crude -3.06mm (-340k exp)

  • Cushing +987k

  • Gasoline -2.95mm

  • Distillates +1.68mm

Official US crude stocks drewdown for the 3rd straight week (more than expected but less than API). Cushing stocks rose for the 5th straight week while Gasoline inventories saw their biggest drawdown since May...

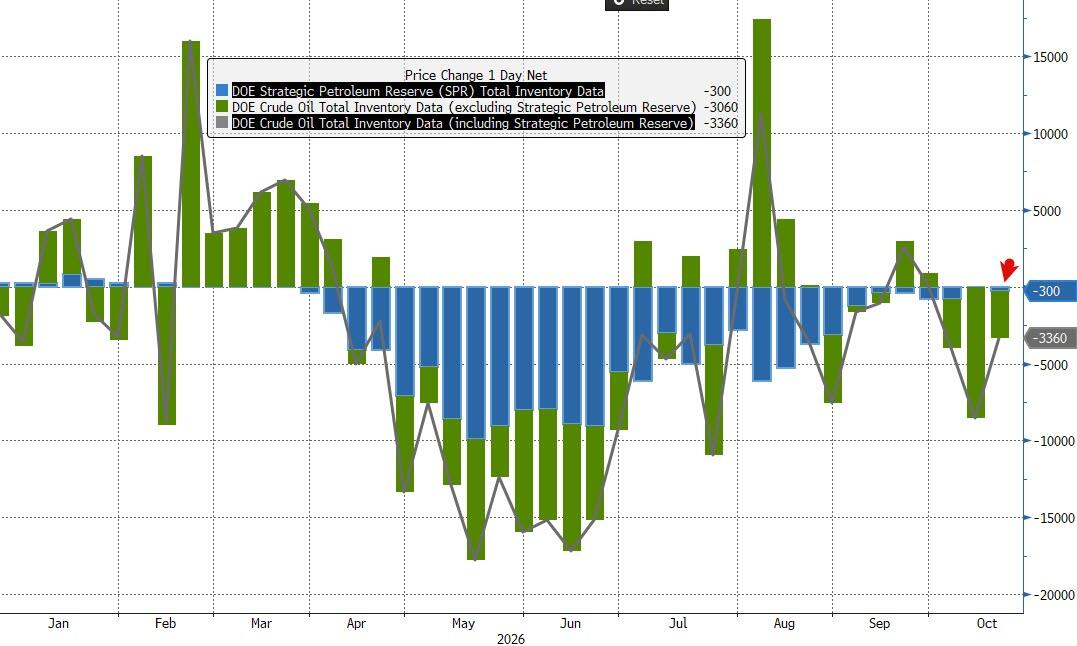
With IEA urging the world to release more barrels from reserves, the US Strategic Petroleum Reserve saw a small 300k barrel drain (after no change the prior week)...

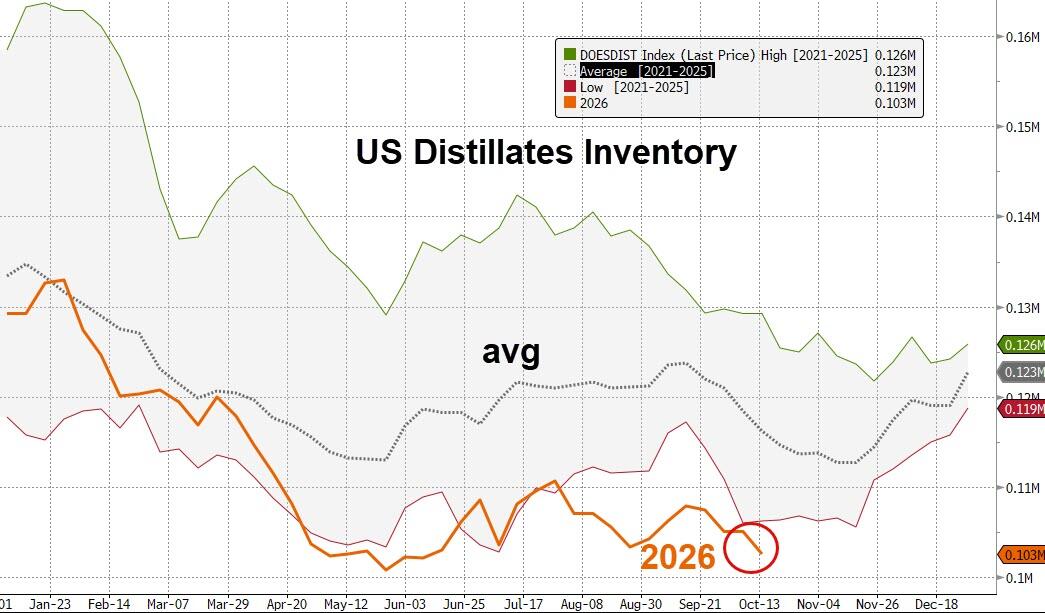
Despite the build this week, distillates stocks remain at record lows for this time of year...

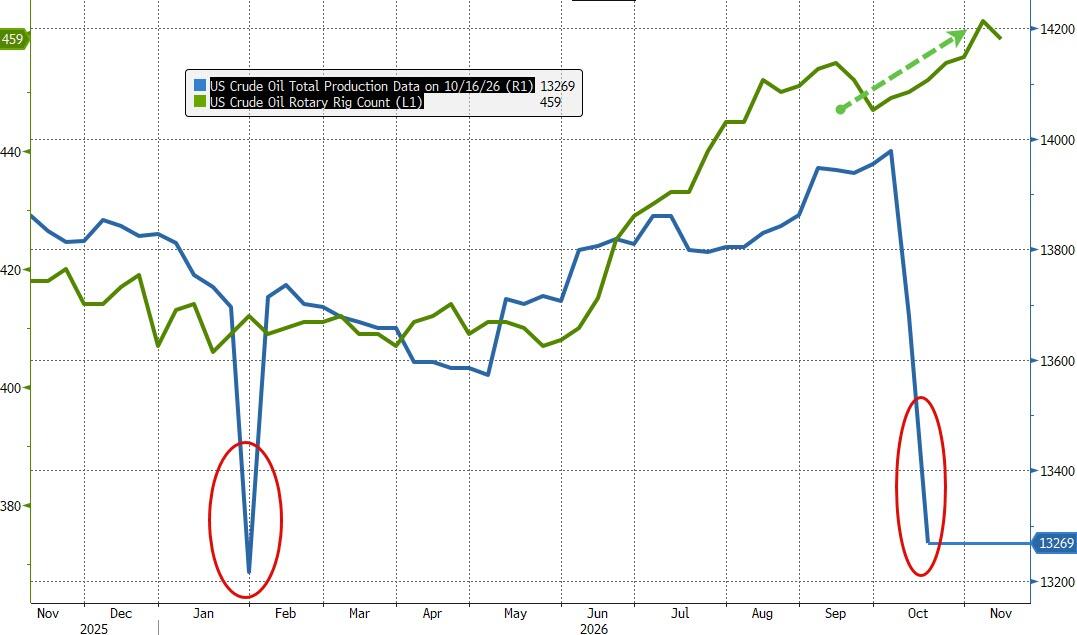
US Crude production fell once again (storm shut-ins)...

WTI was trading around $98 ahead of the official data and didn't move much on the print...

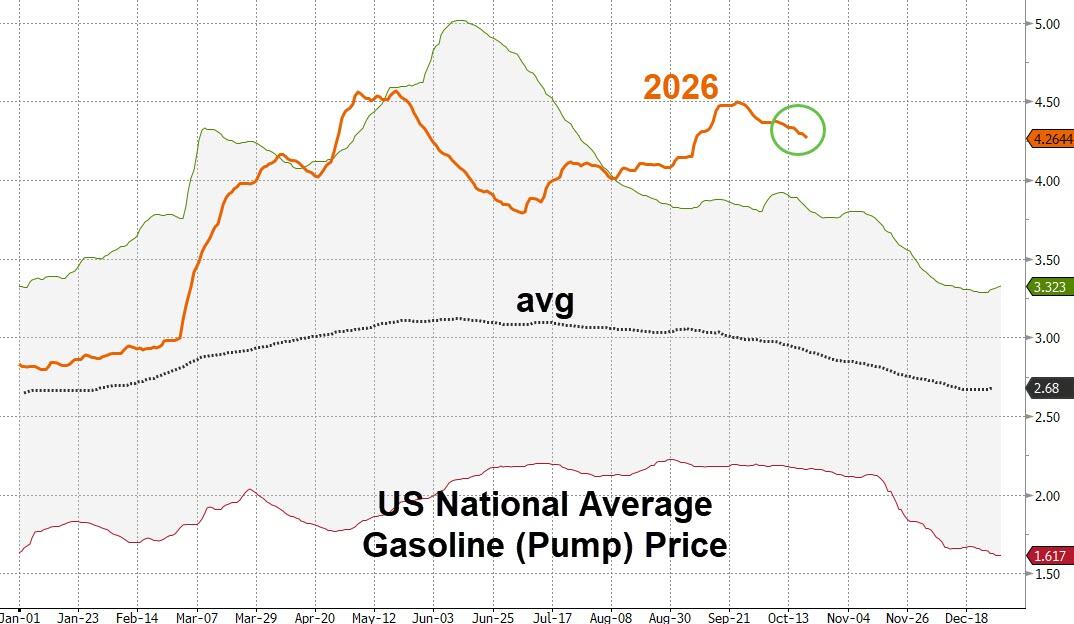
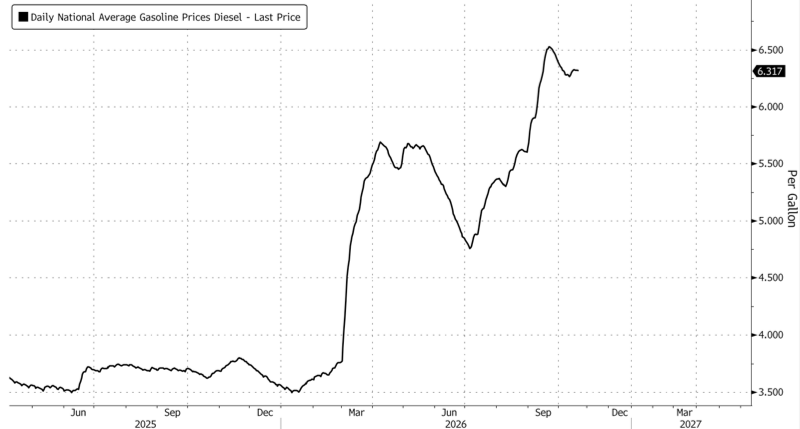
And much to Trump's chagrin, pump prices have never been higher at this time of year...

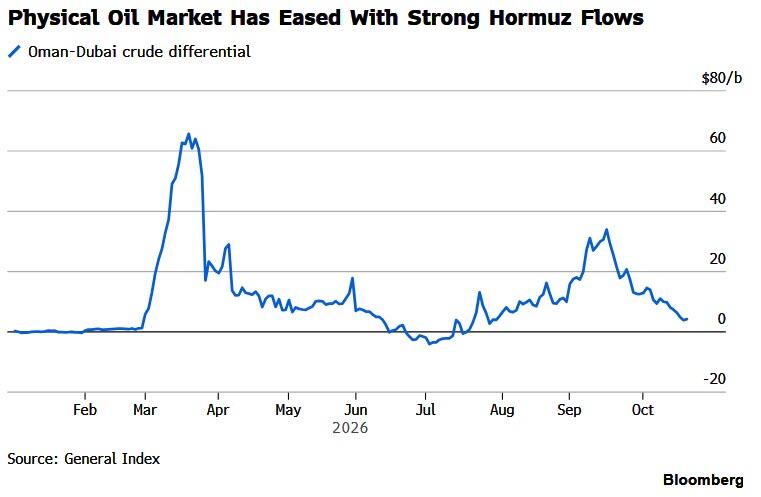
Finally, Bloomberg reports that there are signs that physical markets in some parts of the world are beginning to cool.

As flows through the Middle East rise, one key benchmark in the region has fallen to its weakest level in three months.

The “Gulf crude oil market has been pressured” by the availability of multiple cargoes at relatively short notice, said June Goh, oil analyst at Sparta Commodities SA.

At the same time, traders said high shipping costs mean American barrels aren’t traveling as far afield, pointing more supplies to Europe and pressuring the Dated Brent physical benchmark.

Tyler Durden Wed, 10/21/2026 - 10:40

Pipelines For Peacekeepers? Trump's Trade-Off That Could Freeze The Ukraine War

Zero Hedge -

Pipelines For Peacekeepers? Trump's Trade-Off That Could Freeze The Ukraine War

Authored by Andrew Korybko via Substack,

The conflict could freeze along the frontlines if the US coerces the EU and Ukraine into agreeing to the resumption of Russian energy imports through partially US-controlled pipelines while convincing Russia to agree to the deployment of European forces to Ukraine without the US' Article 5 protection.

Zelensky said that Trump's Special Envoy Steve Witkoff will share with Putin a proposal that amounts to Article 5-like security guarantees for Ukraine during their meeting in St. Petersburg. It was argued here that Putin might agree to that as part of a package deal since Article 5 doesn't obligate the dispatch of troops and its spirit of mutual aid (arms, funds, intelligence, etc.) to an ally under attack has been in effect since the start. Trump could also offer energy-related incentives to Putin to sweeten the deal.

This could involve creative energy diplomacy for getting the EU to release Russia's frozen funds through the sequence outlined here in exchange for the US receiving stakes in its pipelines as the "political safeguard" for Russia resuming exports to the EU. The global energy crisis sparked by the Third Gulf War could also serve as the pretext for the US curtailing energy exports to the EU in order to lower domestic prices and coerce the EU into replacing its lost US imports with Russian ones through this formula.

The complex economic interdependence that would be restored between Russia and the EU due to the US' creative energy diplomacy could assuage Russia's concerns about de facto EU leader Germany's rapid remilitarization that former President Dmitry Medvedev likened to the run-up to Operation Barbarossa. That's because the power that Russia would then have to pull the plug on the German economy could deter Germany from crossing Russia's red lines in the post-war European security architecture.

Likewise, Ukraine's resumption of Russian energy imports through partially US-controlled pipelines could do the same for stabilizing the emerging order in which the US will play a much lesser role in European affairs through the NATO 3.0 model, ergo this proposal's incorporation into Trump's reported peace plan. US stakes in Russian energy companies and resource deposits could deter Ukraine from striking them too in order to maximally reduce the risk of the ongoing conflict resuming sometime after it inevitably ends.

The US-supervised resumption of Russian energy exports to the German-led EU and Ukraine, other US-led Western sanctions relief for Russia (including the phased implementation thereof after a ceasefire), and a post-war resource-centric Russian-US Strategic Partnership would revolutionize European affairs. The benefits that this could bring to Russia might also convince Putin to allow the deployment of some European NATO (E-NATO) forces to Ukraine in exchange for the EU and Ukraine's aforesaid concessions.

Although he earlier said that they'd be a legitimate target, so long as the US doesn't extend Article 5 protection to them like Secretary of War Pete Hegseth confirmed in February 2025 that Trump 2.0 won't do, the risk of a post-war incident spiraling into a hot Russian-US war would remain low. They've been suspected of secretly operating there for years already, and Ukraine's forces are much more experienced than E-NATO's anyhow, so their post-war deployment would only be to psychologically reassure Ukraine.

This scenario is the most sensitive from Russia's perspective, but from E-NATO and Ukraine's perspective, the scenario of the US coercing them into restoring their complex economic interdependence with Russia is equally sensitive. Precisely for this reason, the US might lean on both sides to agree to such mutual concessions in the name of post-war stability, which could then lay the basis for jointly building the post-war European security architecture through new arms control talks and other related efforts.

Tyler Durden Wed, 10/21/2026 - 10:20

WNBA Officially Rejects Enes Freedom And Royce White For Being Men

Zero Hedge -

WNBA Officially Rejects Enes Freedom And Royce White For Being Men

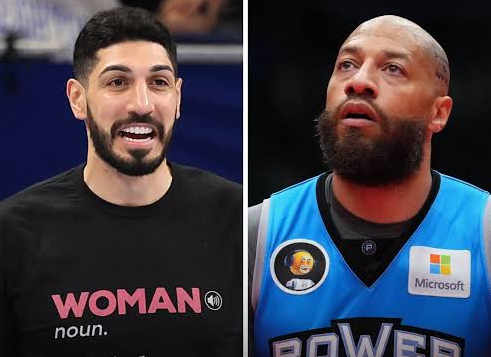
WNBA Commissioner Cathy Engelbert told House Republicans in a letter last week that Enes Kanter Freedom and Royce White cannot play in the league because they are men. Her letter did not include the definition of "women" that lawmakers had requested.

"With respect to your questions regarding eligibility, only women are eligible to play in the WNBA and the individuals you cite in your letter are both men," Engelbert wrote.

The America First Policy Institute, which represents Freedom, provided the letter to OutKick, which was released Tuesday.

Rep. Marlin Stutzman (R-Ind.) and four other House Republicans asked Engelbert about eligibility, player safety, and confrontations with fans after Freedom and White announced plans to enter the 2027 WNBA Draft while identifying as women. They asked how the league defines "women" under Article XIII, Section 1(a) of its 2026 collective bargaining agreement. That provision states, "Only players who are women are eligible to play in the WNBA," but contains no definition of the term.

"The WNBA has just taken the first step in defining what a woman is for the sports community," Stutzman told Outkick. "By clearly labeling Enes Kanter Freedom and Royce White as men, they have acknowledged that identifying as a woman does not change basic human biology."

Engelbert's letter announced no new eligibility rule, no broader policy on transgender athletes and no change to the bargaining agreement with the players' union.

Freedom called out Englebert for her hypocrisy.

"Cathy Engelbert cannot clearly define what a woman is, but she's absolutely certain that I'm a man," Freedom told OutKick. "I mean, how does that make sense? Who gets to decide? Who has the authority to determine whether someone is a woman?"

"So if the league is still working through these questions, how can its commissioner be so certain about my eligibility without explaining the standards that she's applying?" he said.

In August, the league's existing "anti-hate task force," made up of team presidents and general managers, discussed transgender participation and online abuse of players. The league said at the time that it faced no immediate eligibility issues and condemned the use of the subject to demean others.

"If the task force itself has not reached a clear definition, why is the commissioner making such a definitive statement?" Freedom asked.

Asked whether Engelbert had misgendered him, Freedom said, "Yes, 100%." He added, "I just want her to respect my identity because I am telling you that I identify as a woman."

Freedom said the goal of his bid is to push the league to limit play explicitly to biological females. "This is bigger than one basketball player," he said. "Who gets to determine someone's identity? The individual, the commissioner, the medical professional, or a committee or a task force?"

"And who gets to determine eligibility to compete in women's category? So those may be different decisions, but the WNBA needs to explain where it draws the line," Freedom said.

The issue extends beyond Freedom and White. Julie Tetart, a French transgender basketball player who is biologically male, told OutKick in August of an interest in playing in the WNBA. "If they contact me, I won't say no. But you have to be realistic: I'm old, and there are far better players than me!" Tetart said.

The WNBA has not said what position it would take if Tetart sought to join the league.

The eligibility debate grew this summer after Indiana Fever guard Sophie Cunningham voiced support for keeping transgender girls and women out of female sports. Her comments drew rallies during Fever road trips. Freedom has said Golden State Valkyries player Gabby Williams' support for transgender athletes inspired his effort.

Engelbert announced in September that she will retire at the end of 2026. Freedom said her successor could end his challenge with a single word added to the rules. "We are adding the word biological next to the word female, this whole thing will end the next day. I will walk to the sunset. They will not hear from me ever again," he said.

"I'm asking for consistency," Freedom said. "If they do not change the rules, they better select me in a WNBA draft in 2027."

"You cannot answer an eligibility question simply by declaring what somebody is," he said. "You need to explain the policy you are enforcing."

Tyler Durden Wed, 10/21/2026 - 10:05

First Russian Diesel Tanker To Sail For US Under Trump-Moscow Fuel Deal

Zero Hedge -

First Russian Diesel Tanker To Sail For US Under Trump-Moscow Fuel Deal

OSINT X accounts will soon cover the first Russian tanker carrying diesel for the US market, following President Trump's deal with Moscow to supply the US amid a global refining crisis sparked by Ukraine hitting Russian energy assets and ongoing disruptions in the Strait of Hormuz.

Reuters cites the Vedomosti news outlet, which quoted Deputy Prime Minister Alexander Novak as saying earlier today that the first Russian tanker carrying 40,000 metric tons of the industrial fuel will begin its transit to the US on Thursday.

"Additional shipments will follow, of course. There were agreements reached between the two leaders. We will meet the United States' needs, to the extent of our capabilities," Novak said. 

President Trump has stated that, as part of his fuel deal with Moscow, Russia will immediately export 300,000 metric tons, or 2.25 million barrels, followed by 500,000 tons in November and 1 million tons "immediately thereafter."

Earlier today, US special envoy Steve Witkoff joined Russian President Vladimir Putin for peace talks in St. Petersburg. Witkoff thanked Putin for lifting the export ban and agreeing to the US-Russia diesel export deal. 

"That's an example of us working together, I want to thank you for that," Witkoff said during the meeting.

Putin said, "We are preparing deliveries of several vessels, the tankers, right now. They will go one after another. The financial component should be provided." He added that Russia could also supply the US with "large quantities" of fertilizers. 

On Tuesday, oil markets traded near five-year highs as Brent crude futures peaked nearly at $112 a barrel and tensions in the Strait of Hormuz continued. 

UBS analyst Nana Antiedu pointed out, "The primary driver remains the ongoing threat to Strait of Hormuz flows; Iran's First Vice President stated the country has 'no choice' but to assert control over the waterway, keeping a risk premium firmly embedded in prices."

US Energy Secretary Chris Wright on Monday declared that pump prices have peaked ...

... but the International Energy Agency and Goldman Sachs energy experts have warned that there will be no quick relief, as the refining crisis will likely linger well into next year

Tyler Durden Wed, 10/21/2026 - 09:35

Russia Frees Last Wrongfully Detained American At Trump's Request

Zero Hedge -

Russia Frees Last Wrongfully Detained American At Trump's Request

Stephen Hubbard, an American who is accused of fighting as a mercenary for Ukraine forces when he was captured in 2022, has been freed in a Trump-Putin deal while US envoy Steve Witkoff is in St. Petersburg. Hubbard is at the Pulkovo Airport and will safely exit the country, the Russian president said.

ABC reported in the run-up, "the talks have centered on freeing Stephen Hubbard, a 72-year-old retired teacher who is the only American held in Russia officially designated as wrongfully detained by the State Department, as well as several other U.S. citizens held by Moscow on what the administration said it believes are dubious charges."

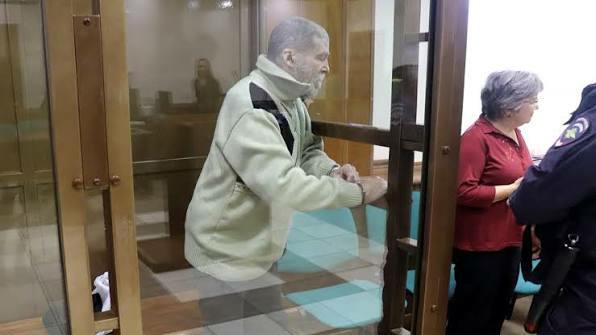
Stephen Hubbard in a Russian court

President Trump had initially on Monday referenced that he was "trying to get a hostage that the country has been after for a long time" - which appeared to refer to Hubbard. "Let's see what happens," Trump said. "That'll be soon."

The release of Hubbard - a Michigan native - was hailed by Witkoff, who addressed Putin saying, "You talk so much about my president, President Trump, being a humanitarian. You are a humanitarian also, sir."

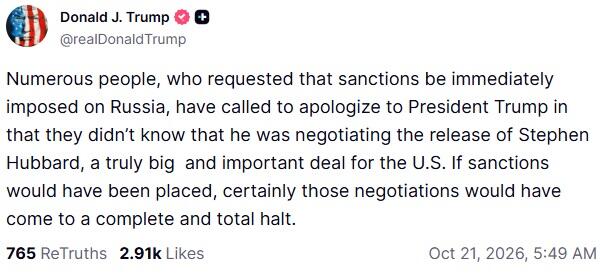
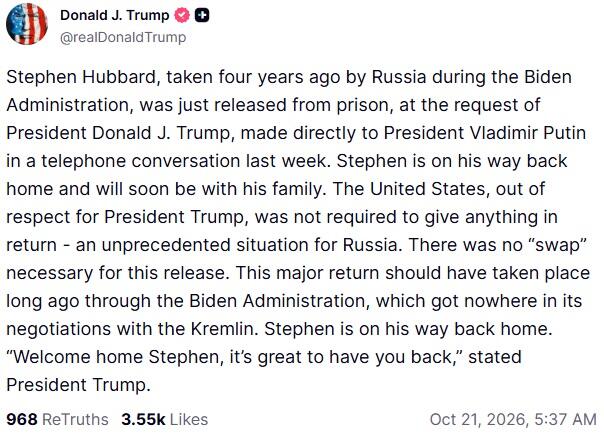
Trump celebrated the development on Truth Social, writing: "Stephen is on his way back home and will soon be with his family. The United States, out of respect for President Trump, was not required to give anything in return — an unprecedented situation for Russia."

It seems this is a Kremlin 'thank you' to Trump for doing the diesel deal, and for at the last minute waiving the sweeping Graham sanctions package, which outraged hawks and Democrats in Congress.

Trump issued at least two Truth Social posts connected with Hubbard's release, lambasting the prior Biden administration for not accomplishing it earlier.

NBC reports, "Trump said that he had directly asked Putin in a phone call last week to release Hubbard, who was being held on charges he denies of fighting as a mercenary in Ukraine. He was the last American designated as wrongfully detained in Russia by the State Department."

On Tuesday, Witkoff and Ukrainian President Volodymyr Zelensky met in Oslo as part of efforts to find an end to the Ukraine war. In a closing presser for the talks, Zelensky said the latest working proposal features security guarantees for Ukraine modelled on NATO's Article 5, which is the collective defense clause.

Wednesday saw Witkoff in St. Petersburg updating President Putin on the current status of negotiations. Some pundits believe the world could be closer than ever before to seeing some kind of significant Ukraine peace deal emerge. TASS subsequently described direct Witkoff-Putin dialogue as "productive". 

Meanwhile an overjoyed Hubbard family has thanked "President Trump and his team for opening the dialog with Russia which led to this joyful day. Our family can attest that there are wonderful blessings to be found along the hard road to peace."

Tyler Durden Wed, 10/21/2026 - 08:30

Futures Rise As SpaceX Blowout Revives AI Trade; Brent Back Above $110

Zero Hedge -

Futures Rise As SpaceX Blowout Revives AI Trade; Brent Back Above $110

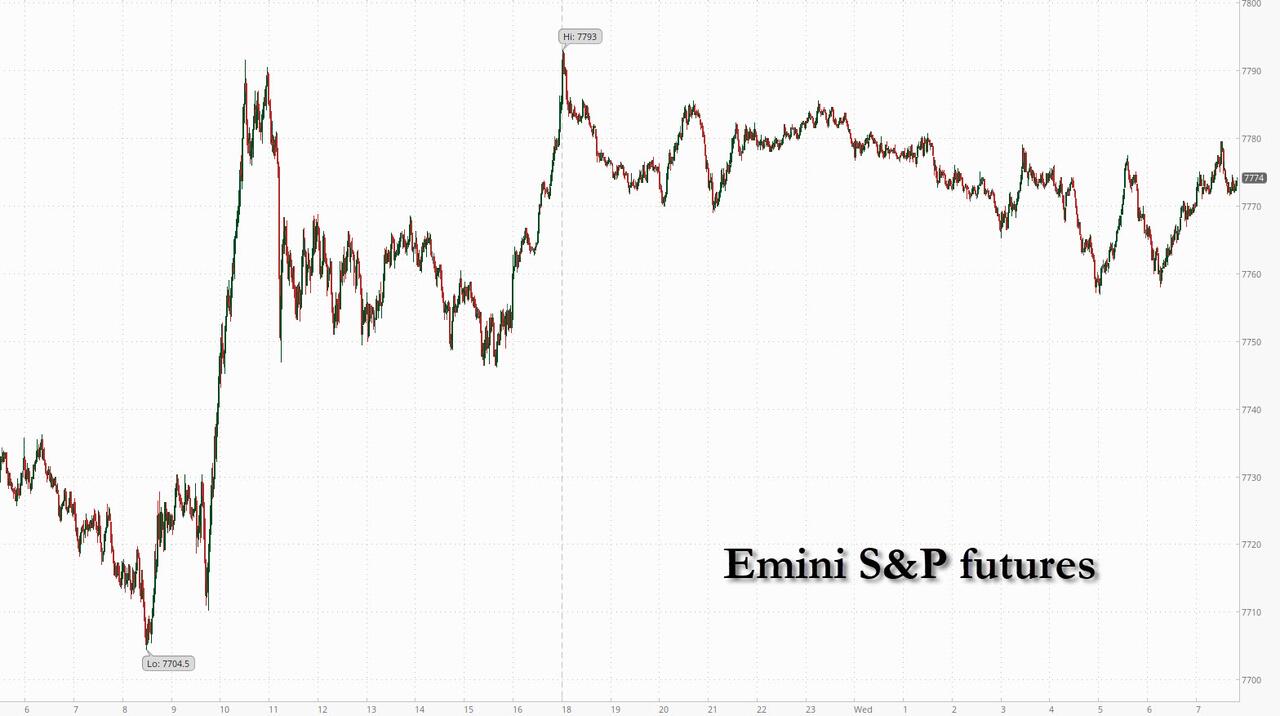
US futures are higher as blowout results from SpaceX and a monster preannouncement from Super Micro gave the battered AI trade a reason to bounce, while Elon Musk's open endorsement of a SpaceX-Tesla merger added to the buzz; but with more attacks on shipping around the Strait of Hormuz, oil is back on the rise and as a result Brent is again above $110 while French 10Y yields hit 5% for the first time since 2002. As of 8:00am ET, S&P futures are 0.3% higher while Nasdaq futures are up 0.6% and Dow futures are up 0.1%. That follows a session in which the S&P rose 0.3% to 7,712 with 403 advancers, the most since April, as the equal-weight index jumped 1.15% while the Nasdaq slipped 0.02% in yet another rotation day out of AI. In premarket trading, the AI complex is back in demand with SpaceX up 9.1% and Super Micro up 12.4%, confirming our post from last night, and Nvidia leads the Mag 7 with a 1.3% gain, while Netflix tumbles 6.2% on a soft Q4 guide and Intuitive Surgical slides 7.8%. The day's driver is AI (again), and this time it's the bulls' turn: SpaceX revenue of $14.6 billion crushed the $12.8 billion consensus and Super Micro guided fiscal Q1 sales to $18.5-19.5 billion vs its own prior $14.5-15.5 billion guide, reviving the AI trade one day after Korea's Elice IPO faceplant and Ken Griffin's warning that investors are "almost certainly" in an AI bubble. Treasuries are slightly cheaper across the curve, led by the front-end and belly, with the 10Y around 5.12% as stocks climb on better AI sentiment and a leg higher in oil adds to the upside pressure on yields ahead of today's $13 billion 20-year reopening; French bonds are the weak link in Europe, with the OAT-Bund spread widening to 158bps on fiscal worries and $110 crude, while gilts outperform even after UK CPI rose to an 11-month high of 3.5%, cementing a November BOE hike. The Bloomberg dollar index is little changed while the Aussie is the best G10 performer, rising 0.5% to 0.7036, the highest since Sept. 28, after hawkish RBA comments. In commodities, WTI rises 1.4% to about $99 and Brent 1.2% to $110, Dutch TTF gas jumps 4%, gold is flat near $4,120 and silver drops 1%. Bitcoin rises 0.8% to about $83,400. US economic data slate is empty after MBA mortgage applications fell 5.3% last week (7am); the Fed is in its external communications blackout ahead of next week's meeting. The Treasury will sell $75 billion of 17-week bills (11:30am) and $13 billion of 20-year bonds (1pm). Earnings from Meta, Tesla, IBM, Texas Instruments and Lam Research come after the close.
In premarket trading, Mag 7 stocks are mixed: Tesla (TSLA) climbs 1.3% after Elon Musk openly endorsed the prospect of combining SpaceX with the electric-car maker. Nvidia is also gaining amid a broad AI rally (Nvidia (NVDA) +2%, Amazon (AMZN) +0.2%, Alphabet (GOOGL) -1%, Meta Platforms (META) -0.5%, Apple (AAPL) -0.4%, Microsoft (MSFT) -0.5%). 

  • AT&T (T) falls 3% after the wireless carrier reported third-quarter wireless postpaid phone net additions that missed the average analyst estimate.
  • Capital One (COF) rises 2% after reporting third-quarter earnings that beat estimates as the largest US credit-card lender benefited from revenue climbing and kept its expenses in check.
  • DigitalOcean (DOCN) climbs 4% after Piper Sandler upgraded the software company to overweight from neutral, writing that it is seeing an acceleration in growth due to AI.
  • Fortinet (FTNT) slips 3% after Arete downgraded the security software company by two notches, to sell from buy, citing concerns about its growth and valuation.
  • Intuitive Surgical (ISRG) falls 5% after the robotic-surgery company reported US growth for its da Vinci surgical robots in the third quarter that fell short of investor expectations.
  • Netflix (NFLX) is down 6% after the streaming-video company gave a revenue forecast that was weaker than expected, compounding concerns about its growth.
  • Philip Morris International (PM) slips 2% after the tobacco maker cut its profit forecast for this fiscal year as rising energy costs stemming from conflict in the Middle East take a toll.
  • SpaceX (SPCX) is up 6% after Elon Musk’s satellite, rocket and artificial intelligence conglomerate reported third-quarter revenue that was better than the average analyst estimate. The beat was driven by substantial growth in its artificial intelligence and satellite internet businesses.
  • Super Micro Computer (SMCI) jumps 11% after the maker of servers reported preliminary first-quarter sales that were stronger than expected, citing AI-related demand.
  • Zoom Communications (ZM) rises 4% after Oppenheimer upgraded the software company to outperform, writing that its AI platform was working better than expected.

In other corporate news, Elon Musk, never one to think small, said SpaceX and Tesla are studying a possible merger, saying the idea has "a lot of merit": the potential $3.5 trillion combination would be the biggest-ever corporate merger, and both companies have formed special committees to consider it. Musk also said ASML and other key providers of chipmaking machines have expedited supplies for his Terafab semiconductor project. Anthropic could spend $750 billion on additional computing power in the coming years, the WSJ reported citing a draft IPO prospectus, while Reuters reports OpenAI is racing to raise about $30 billion at a valuation above $1.4 trillion before Anthropic's IPO. Nvidia is in talks to invest hundreds of millions of dollars in Australian AI cloud provider Firmus, per The Information, after the company abandoned plans for an IPO. Abbott said it will separate its global nutrition business into a public company. United Airlines forecast earnings below estimates as soaring jet fuel prices eat into profits. AT&T reported 3Q wireless postpaid phone net adds of 379,000, short of the 387,410 estimate. Optimum Communications is closing in on a restructuring agreement that will hand control to its lenders, and Getty Images is starting a prepackaged bankruptcy. EQT is in advanced talks to buy Qiagen with a binding offer above $50 a share, with KKR also bidding. Salesforce agreed to buy Braze at a 58% premium, prompting a dozen downgrades of Braze to neutral/hold. DayOne Data Centers is weighing a delay or size cut to its US IPO as data center volatility rises, Disc Medicine priced a 6 million share offering at $75, Sachem Head is planning a more active role at Ionic Digital and Ananym Capital has taken a position in CTS Eventim.

The AI trade is getting a reprieve this morning: Nasdaq futures are higher after solid earnings from SpaceX and Super Micro soothed nerves around the AI trade, but as Bloomberg's Neil Campling notes, lots of questions remain, not least over how companies will pay for their lofty AI ambitions.

“SpaceX appears to have provided exactly what the market was looking for: evidence that AI-related demand remains very real,” said Simon Wiersma, chief investment strategist at ING. “That has improved sentiment not only toward SpaceX itself, but toward the broader AI ecosystem.”

Speaking in Berlin, Nvidia's Jensen Huang said a 1 gigawatt data center now costs about $50 billion (or roughly the same it has been for the past two years before Vera Rubin pushes itg to $100 billion/GW); Anthropic could spend $750 billion on compute; and Musk's ambition to bring 10GW of compute online by the end of 2027 will cost around $500 billion, according to JonesTrading's Mike O'Rourke. SpaceX has $100 billion in cash to start the buildout, but O'Rourke can envision Nvidia offering "some version of Buy Now, Pay Later (BNPL) financing for SpaceX's GPU purchase." Meanwhile, markets keep doing what they're not supposed to: just one day after the biggest Korean IPO of the year cratered 32% on its debut, Elice is up 30%, and the AI CDS frenzy has done little to stop the Kospi from triggering a sidecar on the way up.

“This sounds ludicrous, but ludicrous is what happens in a bubble,” says Jonestrading’s Mike O’Rourke.

“More importantly, we see the latest AI jitters as a bump, not a break, in the AI investment cycle,” writes Sim Moh Siong, FX strategist at Oversea-Chinese Banking Corp. “Taiwan’s strong external fundamentals remain supportive, although active central bank management should keep appreciation prospect gradual.”

Top finance executives are divided over whether a bubble is forming: Ken Griffin said investors are "almost certainly" in the midst of an AI bubble, while BlackRock's Larry Fink warned last week that delays in building data centers could raise computing costs and threaten economic growth. Mounting worries about AI are showing up in a rotation into value and defensives, with the Dow Jones outperforming the Nasdaq 100 by more than 6% so far this month, while option investors are increasingly generating flows that run counter to moves in the S&P 500, with this long-gamma flow from counter-trend trading now larger than traditional dealer gamma, which may explain record low levels of correlation.
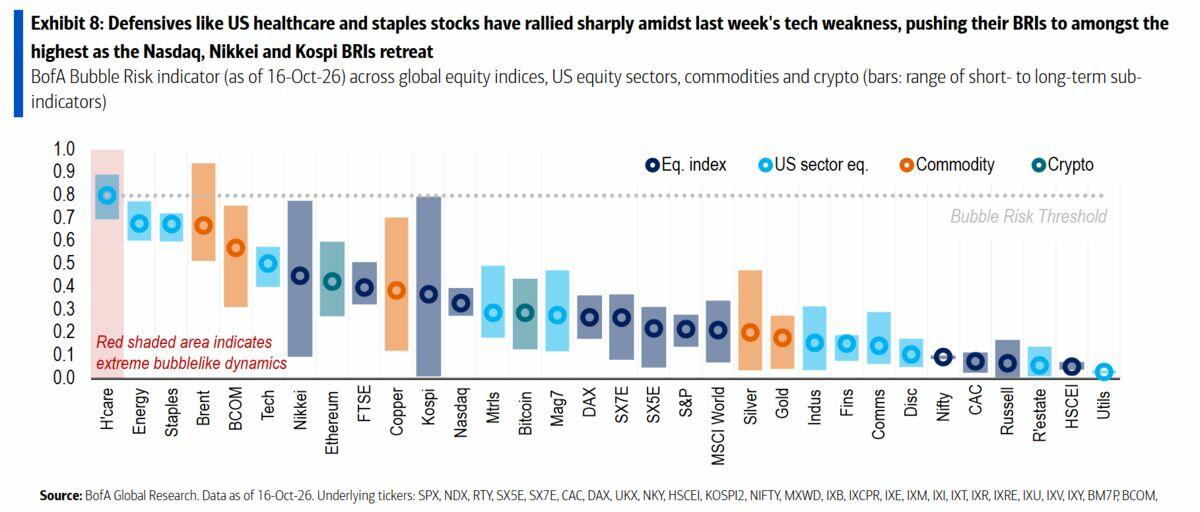
That rotation has gone so far that, according to Bank of America strategists, AI jitters are sending defensive sectors like healthcare and consumer staples nearer to "bubble" conditions, as investors shifting out of AI-linked stocks into safer havens push those valuations to more extreme levels (more in "From AI To KO: BofA Says The Flight-To-Safety Has Become A Bubble Of Its Own").
JPM's Market Intel desk under Andrew Tyler says SpaceX's beat and Super Micro's upside preannouncement were both supportive for AI sentiment, but warns that "these two catalysts alone would not resolve investors' concerns about financing risk and the scale of AI capex." The team doesn't think much has changed beneath the headline noise: Tuesday's sharp squeeze in the Russell "looks more like short covering than growing confidence," with high-touch volumes down 32% and, per trader Matt Reiner, "mass hesitation to step in and re-gross." The desk remains Tactically Bullish, favoring cyclicals outside tech while selectively buying tech weakness. All eyes now turn to Meta tonight: JPM's Mark Schilsky puts the revenue bogey at about $64 billion and says buyside consensus for 2027 opex plus capex is $435-475 billion, adding that a majority of investors still believe an equity raise is likely post-Q3. Separately, JPM's Stuart Humphrey called SpaceX "a very strong print, particularly SI," but reminds that 1.3 billion shares become eligible for sale off lockup on Thursday.

Goldman's desks are similarly skeptical of the bounce. GS Prime's Vincent Lin writes that "October has tested the AI trade": hedge funds just posted the largest two-week net selling of global Info Tech on record (-3.3 SDs), short sales outpaced long buys roughly 5 to 1 this month, and short leverage is in the 99th percentile, approaching 5-year highs ("short squeeze risk alert?"). TMT specialist Sean Johnstone says SpaceX "printed the cleanest AI-segment ramp yet," guiding Q1 2027 revenue to $33-37 billion vs a Street at about $22 billion, but the US desk was "still a net seller of Semis/AI into this bounce" and Tuesday's move higher "felt squeezy with short pockets at the top of the leader board." And for those keeping score on risk appetite, Goldman's cross-asset Risk Appetite Indicator has declined sharply over the past 3 weeks and turned negative for the first time since March, while Johannes Duttenhoefer flags that margin debt rose $26.2 billion in September, the second-highest month-end reading on record.

In geopolitics, the Iran standoff shows no sign of resolution: Iranian Foreign Minister Araghchi wrote in an FT op-ed that "there is little reason to expect progress now" given the White House's threats, Pakistan's army chief Munir reportedly delivered a US "final warning" to Tehran, and the FT reports Netanyahu is pushing to resume large-scale strikes on Iran. UKMTO received a late report of a tanker struck by an unknown projectile 30nm southeast of Al Faw, Iraq, though Gulf oil exports have surpassed prewar levels per the WSJ. On Ukraine, US envoy Steve Witkoff takes the security-guarantee proposals discussed in Oslo to St. Petersburg today, while the WSJ reported that Musk ordered a slowdown of Ukraine's Starlink service (prompting Marco Rubio to say Ukraine "would not exist" without US backing). In politics, National Democrats sued Trump and the DOJ over what they call a coordinated effort to erode confidence in the midterms.

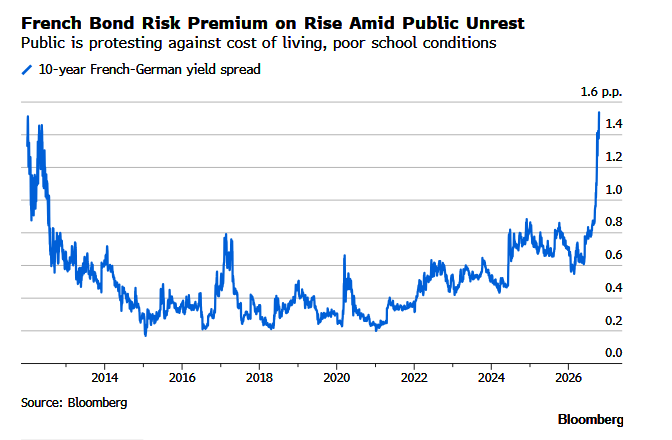
In Europe, the French bond rout continues: the 10Y OAT yield rose 7bps to 5%, the highest since July 2002, with the OAT-Bund spread widening to 158bps as higher energy prices hit bonds across the eurozone on top of persistent fiscal concerns. One trader bought 5,000 OAT March put spreads targeting the 10Y yield climbing to 5.60% by mid-February, a level last seen in 2000. The domestic unrest is now hitting earnings: Carrefour cut its 2026 targets citing riots, looting and curfews across France, and Goldman's FX desk expects Moody's to downgrade France to A1 on Friday.

In Europe, the Stoxx 600 is up 0.5%, extending an early gain as investors assess a flurry of corporate results, with real estate, energy and tech leading while autos, personal care and retail lag; the CAC 40 rises 0.4% as EssilorLuxottica's 14% jump outweighs Carrefour's 14% plunge. JPM notes Luxury, Semis, AI Disruptions and Cyclicals are among the top performing baskets; the Euro Stoxx 50 is up 0.6%, the DAX 0.5% and the FTSE 100 0.1%. Here are the biggest European movers:

  • Randstad shares rally as much as 19% after the recruitment firm reported 3Q organic growth that beat consensus expectations.
  • Adidas shares rise as much as 2.4% after the German sportswear maker reported preliminary third-quarter operating profit that beat estimates and raised its full-year profit outlook.
  • Pepco surges as much as 8.4% after the retailer’s main shareholder, Ibex, sold a 5.5% stake through accelerated book-building.
  • Iberdrola shares rise slightly after the Spanish power company raised its profit forecast. Analysts at Morgan Stanley say the increase is largely priced in.
  • Carrefour shares drop as much as 15% after the French supermarket operator slashed its full-year financial goals, citing the “worsening social and security situation” following violent protests and looting across the country that damaged its stores.
  • Michelin shares fall as much as 6.4% after Citi said third quarter revenue missed expectations due to weaker volumes.
  • Elisa shares drop as much as 6.3% after the Finnish telecom carrier reported declining telecom service revenues and 3Q Ebitda that missed consensus expectations.
  • Akzo Nobel shares fall as much as 1.8% after the paints and coatings manufacturer posted results analysts described as mixed, with weaker volumes somewhat offset by margin resilience.

Asian stocks rose, bouncing back from Tuesday's rout as blockbuster results from US tech revived the AI trade, with the MSCI Asia Pacific Index gaining as much as 1.6% and Samsung, SK Hynix and TSMC among the biggest drivers. South Korea's Kospi jumped 3.3% to 5,735.66, triggering a sidecar as Kospi 200 futures surged 5%, with foreigners snapping an 18-day net-selling streak in SK Hynix per Goldman, while Elice rebounded 30% after its 32% debut slump. Taiwan's Taiex rose 1.3%, its best day since Oct. 5, and the Nikkei added 0.9% to 64,621 despite softer-than-expected exports. China was the exception: the Hang Seng fell 0.9% to 23,651.87, its lowest close since July 7, as CATL tumbled 11.4% after its Q3 miss and Tencent slid 4%, and the CSI 300 dropped 1.0%; the ASX 200 was little changed and Bank Indonesia held rates at 5.75%. Goldman's Rachel Hu notes that "the de-rating of AI and crowded growth trades continued to dominate regional price action."

In FX, the Bloomberg Dollar Spot Index is little changed and the DXY trades in a tight 101.73-101.83 range. The Aussie is the best G10 performer, up 0.5% to 0.7036, the highest since Sept. 28, after RBA Deputy Governor Andrew Hauser said the inflation outlook is "materially worse" than forecast; Goldman now expects a 25bp RBA hike in November and markets price about a 50% chance. The euro slips 0.1% to 1.1226 as French spreads widen, while the pound is a touch firmer after UK CPI topped estimates, with EUR/GBP down 0.1% to 0.8389 even as the cost of hedging the pound against the euro hit a five-month high ahead of next week's UK budget. USD/JPY is little changed at 158.1, and the Taiwan dollar snapped a four-day drop.

In rates, Treasuries are slightly cheaper across the curve, led by the front-end and belly as stocks climb on better AI sentiment, while a leg higher in oil adds to the upside pressure on yields after continued attacks in the Strait of Hormuz. Yields are cheaper by up to 1.5bp across the front-end, marginally flattening 2s5s and 2s10s, with the 10Y trading around 5.12%; bunds lag by 1bp while gilts outperform by 1bp, with UK 2-year yields as much as 3bps lower at 4.93% as traders fully price a November BOE hike after CPI. Today's duration event is the $13 billion 20-year reopening at 1pm: the WI is trading around 5.485%, about 6.5bp cheaper than September's stop-out, which tailed by 2bp (in other words, not exactly a vote of confidence). Traders keep piling into bearish bets: 12,000 TY Wk5 104.0 puts were bought, taking the total above 100,000 contracts since the start of the week, a position which targets 10Y yields at least 20bps higher by month-end. Swaps price about a 20% chance of a Fed hike next week. The IG dollar issuance slate includes a handful of names after two issuers priced a combined $3.5 billion on Tuesday, taking the week to just over halfway to dealers' $25 billion forecast.

Former New York Fed President Bill Dudley argues in a Bloomberg Opinion column that the AI investment boom is currently pushing US interest rates up before its eventual unwind slows the economy and prompts the Fed to cut sharply.

In commodities, WTI is up 1.4% at $99.20 and Brent rose 1.2% to $110.13 (holding within a $109.27-110.75 range), rebounding from Tuesday's losses as attacks on ships around the Strait of Hormuz threatened shipments and industry data showed US crude stockpiles fell 4.9 million barrels, far more than the 1.1 million expected. Goldman estimates global crude freight costs have surged about sevenfold over the past year to above $20/bbl, while the premium of Oman crude over Dubai fell to near $4, the lowest since late July, a sign of resilient Gulf exports. Morgan Stanley raised its 2027 Brent forecasts and says product markets will stay tight through mid-2027. Dutch TTF gas rose 4% toward €90/MWh on LNG disruptions; Macron said France secured 2 terawatt-hours a month of Qatari gas over the winter, and the UK approved the Jackdaw North Sea gas field. Spot gold is flat in a $4,106-4,131 range, silver is down 1% and LME copper is lower.

US economic data slate is empty after MBA mortgage applications fell 5.3% (7am), with the EIA weekly crude inventory report at 10:30am; the Fed is in blackout ahead of next week's decision. The Treasury sells $75 billion of 17-week bills (11:30am) and $13 billion of 20-year bonds (1pm). Abbott, AT&T, Philip Morris, Thermo Fisher, NextEra, CME and Moody's report before the open, with Meta, Tesla, IBM, Texas Instruments, Lam Research and SAP after the close; Nvidia's GTC Berlin continues.

Market Snapshot
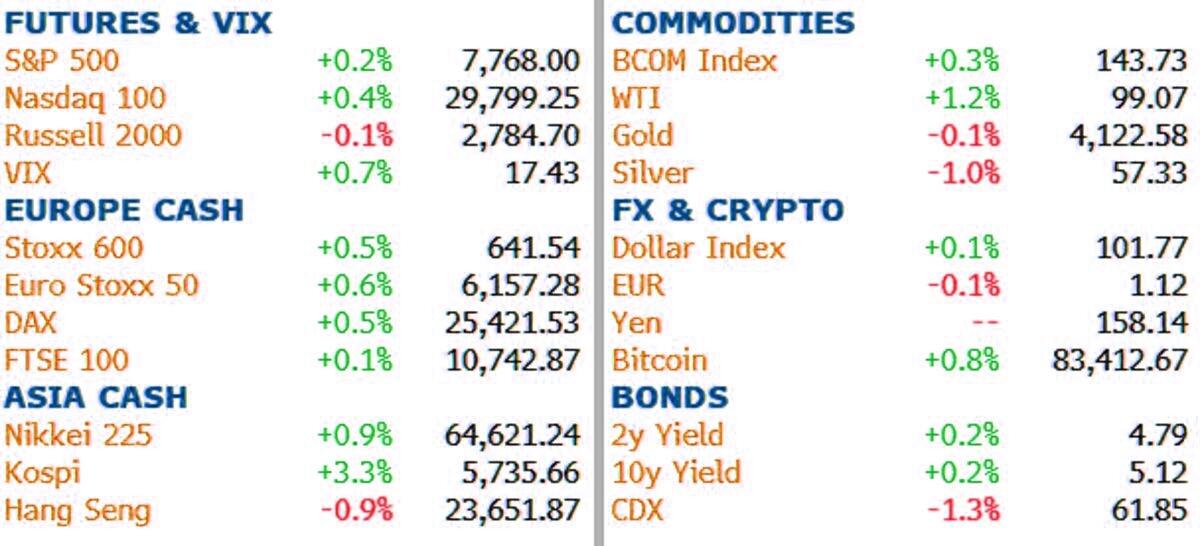
Top Overnight News

  • Anthropic could spend $750 billion on additional computing power in the coming years, the WSJ reported, citing a draft IPO prospectus, while billionaire Ken Griffin said investors are "almost certainly" in the midst of an AI bubble. BBG
  • Nvidia is in talks to invest hundreds of millions of dollars in Australian AI cloud provider Firmus. The Information
  • Nasdaq futures rose after SpaceX and Super Micro topped forecasts, reigniting the AI trade. Adding to the buzz, Elon Musk said SpaceX and Tesla are studying a potential merger that would be the biggest ever. BBG
  • Over the past two weeks, HFs aggressively net sold global Info Tech stocks at the fastest pace in the past decade (-3.3 SDs), driven by long-and-short sales. Net allocation to Global AI stocks now sits in the 38th percentile while aggregate long/short ratio is in the 6th percentile vs. the past year. GSPB
  • Persian Gulf oil exports have surpassed prewar levels, as an improvised shipping system under U.S. protection is helping tankers move oil through one of Iran’s fiercest waves of attacks in the Strait of Hormuz. WSJ
  • Benjamin Netanyahu is pushing to resume large-scale strikes against Iran and had instructed his military to plan for a major new offensive earlier this month, moves that risk plunging the region back into full-scale war. FT
  • More Oil Is Now Coming Out of the Persian Gulf Than Before the Iran War: WSJ
  • "Given that the White House has shown no willingness to reach an understanding on the way forward, while also threatening more violence, there is little reason to expect progress now," Iranian FM Araghchi said in an FT op-ed. BBG
  • UKMTO received a late report of a tanker struck by an unknown projectile 30 nautical miles southeast of Al Faw, Iraq, on Tuesday; crew reported safe. BBG
  • French yields rose above 5% for the first time since 2002 as persistent fiscal concerns continued to weigh on bonds BBG
  • U.K. inflation rose further above the Bank of England’s target in September as policymakers prepare for a meeting that investors expect will yield a first rate increase since the start of the war between the U.S. and Iran. WSJ
  • Britain’s national debt topped £3 trillion for the first time as the government borrowed more than forecast in the first half of the fiscal year. BBG
  • Australia’s inflation outlook looks “materially worse” than previously expected, RBA Deputy Governor Andrew Hauser said, bolstering expectations for a fifth hike this year in November. BBG
  • Japan’s exports rose 16.7% in September, missing forecasts despite an increase in chip shipments. South Korea’s exports jumped 65.9% in early October, powered by a more than 220% semiconductor surge. BBG
  • Leaders of Ukraine, Finland and Norway hailed progress in talks in Oslo on Tuesday about how to end Russia’s war in Ukraine, but they did not announce any breakthroughs. “I think we made genuine progress today,” said Finnish President Alexander Stubb, who co-hosted the talks with Norwegian Prime Minister Jonas Gahr Støre at the request of Ukraine. FT
  • Elon Musk ordered a slowdown of Ukraine's military-grade Starlink service, and Musk and Trump discussed the decision in a subsequent call. WSJ
  • The US is increasingly reliant on price-sensitive private investors to fund its debt as traditional buyers retreat. Hedge funds and other private investors now own about 70% of Treasuries, helping drive yields higher. BBG
  • US President Trump posted that he is watching data centres closely: Newsquawk
  • US and Mexican negotiators hit an impasse over tariffs on steel and aluminum, dashing earlier optimism. BBG
  • National Democrats sued Trump and the US Justice Department over what they say is a coordinated effort to erode confidence in the midterms. BBG
  • JPM's Mark Schilsky puts buyside consensus for Meta's 2027 opex plus capex at $435-475 billion, and says a majority of investors still expect an equity raise post-Q3. JPM
  • Goldman estimates global crude freight rates are above $20/bbl, about 7x a year ago, with the Hormuz war-risk premium alone accounting for about $7/bbl. GIR

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly firmer as after-hours strength in AI names, following Super Micro Computer's upbeat guidance and SpaceX's earnings call, offset the mixed lead from Wall Street, where the Nasdaq 100 lagged on AI-debt concerns. ASX 200 was little changed amid a busy morning of company updates, including NEXTDC's FY27 guidance cut, while Goldman Sachs shifted to expecting a 25bps RBA hike in November after hawkish remarks from RBA's Hauser. Nikkei 225 gained on the AI-led strength in US after-hours trade, shrugging off softer-than-expected exports and a wider-than-expected trade deficit. KOSPI outperformed and triggered a sidecar as KOSPI 200 futures jumped 5%, rebounding after Tuesday's sharp slide. Hang Seng and Shanghai Comp were lower with the latter reversing earlier opening gains, while CAICT data showed a 22.9% Y/Y drop in China's September smartphone shipments and CATL was in focus after its Q3 miss.

Top Asian News

  • Japanese Finance Minister Katayama said the government is coordinating closely with the BoJ, with no major divergence on the inflation outlook or monetary policy. Noted that tax cuts boost demand and push up prices. Government will ensure proactive and responsible fiscal policy strengthens Japan's supply capacity without accelerating inflation.
  • Japan and India to hold 2+2 meeting in mid-November, Kyodo reported citing officials, with the aim to strengthen cooperation in maritime security and economic subjects.
  • China's September smartphone shipments fell 22.9% Y/Y, according to CAICT.

European bourses (STOXX 600 +0.5%) have a slight positive tilt to start Wednesday’s session, with upside seen in France’s CAC 40 (+0.4%), as EssilorLuxottica (+14.2%) upside outweighs the downside in Carrefour (-14%). Outside of a busy earnings docket, which is set to be even busier tomorrow, there has been little in terms of a broader driver. Sectors are mixed. Real Estate tops the sector pile, with Energy and Tech rounding out the sector gainers. At the bottom sits Autos, as Optimised Personal Care and Retail follow. Other key updates include: Adidas +1.6%, Q3 metrics beat and lifts its FY26 operating profit guidance; Iberdrola +0.6%, raises its FY26 adj. net growth profit guidance to “at least” 10%; Qiagen +1.4%, as EQT reportedly offers USD 50/shr to acquire the company. US equity futures are mixed, with outperformance in the NQ following upbeat after-hour earnings from SpaceX and Super Micro. The former reported a sharp increase in AI revenue, which drove a swing to profit, while the latter raised its Q1 outlook on stronger AI platform demand. Focus now turns to Meta and Tesla earnings tonight.

Top European News

  • The UK government has approved the Jackdaw North Sea gas field, with the Energy Minister saying the project will start to supply gas to British homes and businesses from as early as the end of this month. In later comments, the UK Energy Secretary said that the government will decide shortly on the Rosebank oilfield project.
  • Germany's Federal Finance Agency Director said that unconditional European support measures to calm sovereign bond markets could trigger a more serious debt crisis later, Econostream reported.
  • French Finance Minister said France have the instruments to pass a budget.

FX

  • G10s are mixed against the USD. The Antipodeans gain, with mild outperformance in the Aussie after hawkish commentary from RBA’s Hauser. The EUR holds towards the foot of the pile.
  • DXY is essentially flat and trades within a 101.73-101.83 range, holding towards the lower end of the prior day’s range. The data docket has been light this week, and will remain so; therefore, the USD may need surprises in tech-earnings/geopolitics to make a move in either direction. On that note, the USD came under mild pressure on Tuesday following reports that the Iranians were presented a “compromise proposal”; newsflow since then has been lacking, but the Iranian FM suggested that indirect negotiations were ongoing. Nonetheless, the situation remains tense with reports suggesting that tankers are still under fire.
  • AUD is the best performer this morning, following hawkish commentary from RBA’s Hauser. He mentioned that the inflation outlook is “materially worse”, blaming AI spending and rising energy costs. Hauser added that Q3 CPI will show inflation accelerating. Money markets have upped their bets of a hike at the November meeting, and now assign a c. 50% chance of such a move. Further adding to the hawkish tone was Goldman Sachs now expecting a 25bps rate hike in November, vs its previous call of no move. AUD/USD topped the 0.70 mark, to trade back towards levels not seen since late-September.
  • EUR is the slight underperformer this morning, with sentiment around Europe remaining downbeat. The OAT-Bund spread remains exceptionally wide at c. 156bps, and building on recent advances. Of course, the civil unrest in France and the ongoing French fiscal situation remain front of mind.
  • Across the channel, the GBP is a touch firmer this morning. Some mild strength was seen following the region’s inflation report, which saw the headline rise a touch more than expected, whilst Core M/M fell from the prior. Overall, a slightly firmer-than-expected inflation report, which plays in favour of those pushing for a hike at the BoE's November confab. Today's report, alongside the recent solid jobs report, will provide MPC members with enough evidence to suggest that the UK economy is holding up fairly well to deliver a hike in November. For reference, Danske, MUFG and Pantheon all expect a hike next month, and Pantheon sees another in February.

Central Banks

  • RBA's Hauser said monetary policy is working, but the inflation outlook has deteriorated and appears worse than forecast. Inflation has remained elevated for an extended period, while inflation expectations must remain anchored to the target. Companies continue to cite cost pressures as their primary concern. There has been some slowing in labour market and housing data. RBA is still finalising its forecasts, and it remains uncertain what decision the Board will make. Looks like quarterly trimmed mean will be higher than expected.
  • BoJ is expected to assess whether underlying inflation has reached its 2% target at its October 29th-30th policy meeting, while keeping interest rates unchanged at around 1.25%, Kyodo reported.
  • BoJ's Himino said upside inflation risks remain high, warning that delays in adjusting monetary policy could allow inflation risks to materialise and harm the economy. Financial conditions remain accommodative, with real interest rates low and bank lending expanding rapidly. Medium- and long-term inflation expectations continue to rise. Underlying inflation is nearing the BoJ's 2% target and is expected to converge towards levels consistent with the target. Strong AI demand is boosting domestic capex and exports.
  • ECB's Kazaks said that some more policy tightening might be necessary if inflation continues to reside above target and that the recent rise in yields has already tightened financing conditions, Econostream reported.
  • ECB's Lane said greater global euro use may help the ECB control prices.
  • Indonesian Central Bank left the BI rate unchanged at 5.75%, raised the Deposit Facility rate to 5.00% (prev. 4.75%).
  • Goldman Sachs now expects the RBA to hike rates by 25bps to 4.85% in November, having previously expected rates to remain unchanged.

Fixed Income

  • A relatively contained morning for fixed income. USTs in a narrow sub-10 tick range, awaiting geopolitical updates with the docket otherwise fairly light and headlined by equity newsflow.
  • Bunds also contained, in a narrow 121.43-74 band; however, this currently comes with pressure of around 20 ticks, weighed by a gradual move higher in energy overnight and one that has continued marginally this morning for WTI and Brent. Particularly though, marked upside in TTF is doing the heavy lifting.
  • Gilts digested the morning’s inflation data as the hawkish driver it is, opening lower by just under 30 ticks and then slipping further to a 83.91 low, but still above 83.85 and 83.79 from Tuesday and Monday respectively. In brief, the series shows continued price pressures, with the headline well above the BoE’s forecast. However, and pertinently, the series still does not indicate overt or significant second round effects.
  • Overall, it keeps the BoE on track for a hike in 2026 and makes the November meeting ever more likely, barring a significant shock between now and then. But, the hike is likely to be a risk-management/prudence move, rather than a function of policymakers being concerned that second round effects are getting out of hand. A point that means calls for just one hike early in 2027, and then an extended hold before easing returns to the conversation, are likely fair at this stage.
  • Australia sold AUD 1.0bln of 4.25% October 2036 bonds; b/c 3.63x (prev. 4.51x), average yield of 5.2545% (prev. 5.3802%).

Commodities

  • WTI and Brent are trading with gains of 1.7% and 1.4%, respectively. Strength which appears to be a bit of a bounce back following the hefty losses seen in the prior session. WTI currently holds towards the upper end of a USD 97.91-99.57/bbl range, whilst Brent holds within a USD 109.27-110.75/bbl band.
  • The current geopolitical environment contains a number of key focus points. Starting with US-Iran, the Pakistani Army Chief met with Iranian officials in Tehran. Reports suggested that he provided a Qatar/Pakistan led “compromise proposal”, but this has yet to be confirmed. Instead, N12 reported that Army Chief Munir brought the US’ “final warning” to Iran, and if that does not bring peace, then the report suggests that the US could target Iranian nuclear facilities. The overarching theme is that the diplomatic path appears to be in effect, as confirmed by the Iranian Foreign Minister, but risks of escalation remain.
  • The other main points of interest are: 1) potential Russia-Ukraine peace; US Envoy Witkoff has met with Russian President Putin today, where he is expected to present a peace plan later; so far, Putin and Witkoff have struck a conciliatory tone. 2) Ongoing strikes between Saudi Arabia and the Houthis.
  • Dutch TTF (+4%) is stronger this morning, but holds a little shy of the EUR 90/MWh mark, remaining within a EUR 86.02-88.97/MWh range. Strength facilitated by ongoing LNG disruptions and as we enter the winter period, amidst low EU storage inventories. On the gas subject, the UK government has approved the Jackdaw gas field, and will begin production this month. The effect of this decision will likely be negligible on global markets, given it is expected to supply only around 6% of the UK’s domestic gas output.
  • Spot gold is essentially flat and trades towards the bottom end of a USD 4,106-4,131/oz range. Action today appears to be following the lacklustre action seen in the Dollar, and will ultimately take cues from any geopolitical updates. Elsewhere, base metals are broadly lower this morning. 3M LME Copper trades within a USD 14,284.63-14,463.63/t range.
  • US Weekly Private Inventory Data (bbls): Crude -4.9mln (exp. -1.1mln), Gasoline -2.0mln (exp. -0.7mln), Distillate -2.6mln (exp. -1.6mln), Cushing +0.9mln.
  • Russian Deputy PM Novak said they could see a full restoration of diesel volumes by end-2026 and they could have a commercial deal with China regarding Power of Baikal by end-2026, IFX reported.
  • South Korea's President Lee said the government is preparing to reduce mandatory domestic fuel supply obligations and allow refiners to increase exports.
  • Russian President Putin said that they could supply fertilisers in large quantities to the US market, TASS reported.
  • Iranian FM Araghchi said Tehran has opened dedicated routes for ships carrying Iraqi oil to pass through the Strait of Hormuz in order to reduce Iraq’s losses.
  • French President Macron said they secured 2 terawatt-hours per month of gas from Qatar during the winter period.

Geopolitics: Middle East

  • Pakistan Army Chief Munir, in his meeting with Iranian officials, brought with him the "final warning" from the United States, which called on Iran to submit to the American demand for concessions on the nuclear issue before taking any other steps.
  • Iranian Foreign Minister Araghchi said indirect US talks continue via Pakistan and Qatar despite Washington's public opposition. Araghchi added that the US accepted Iran's seven-day proposal to reopen the Strait of Hormuz but added conditions. Iran insisted Washington first honour commitments under the Islamabad MoU before further negotiations, stressing that diplomacy remains possible if the US fulfils its obligations.
  • Iranian Foreign Minister Araghchi said Tehran has yet to receive a response from Saudi Arabia or Yemen's Houthis regarding its mediation initiative, while warning against trusting the US in negotiations. All possibilities are on the table, including a new war launched by the United States and Israel against Iran. Sanctions and the blockade have imposed major burdens on Iran. Reopening the Strait of Hormuz depends on reaching an understanding with the US.
  • Iran's IRGC Political Deputy said Iran will target internet cables in the Strait of Hormuz if its infrastructure is attacked, Mehr reported.
  • Iran has reportedly prepared for an all-out, multi-layered and comprehensive war against its adversaries, Press TV reported, citing a source.
  • Israeli PM Netanyahu is pushing to resume major strikes on Iran, but a planned October 10th offensive was halted amid Trump's opposition ahead of the US midterms, FT reported.
  • UKMTO received report of an incident 11NM west of Bukha, Oman.
  • Houthi military spokesperson said they did not launch any drones toward Medina, Saudi Arabia, on Wednesday.
  • Saudi-led coalition said it intercepted and destroyed four drones launched towards Saudi Arabia, according to a coalition spokesperson.

Geopolitics: Ukraine

  • US Special Envoy Witkoff said talks in Oslo were productive and that there is forward progress on the issue of Ukraine, IFX reported. Witkoff added that a basic foundation exists for a ceasefire in Ukraine and hopes that Russian President Putin will consider resuming US-Ukraine-Russia talks. Furthermore, he emphasised that Russia and the United States have prospects for developing economic relations after the end of the conflict in Ukraine.
  • Russia's President Putin told US Special Envoy Witkoff that Russia is interested in restoring economic ties with the US, IFX reported.
  • Russian President Putin invited US Envoy Witkoff for discussions on the prospect of a meeting between Putin and US President Trump in China, IFX reported.
  • Elon Musk reportedly ordered a slowdown of Ukraine's military-grade Starlink service, while Musk and Trump discussed the decision in a subsequent call, WSJ reported.
  • Russia’s Foreign Ministry said it views Japan’s supply of drones to Ukraine as a hostile act; Russia will respond.

Crypto

  • Bitcoin fell to a low of USD 82.54k before gradually climbing to a peak of USD 83.6k throughout the European morning.

US Event Calendar

  • 7:00am: Oct 16 MBA Mortgage Applications, actual -5.3%, prior -2.7%
  • 10:30am: EIA weekly crude oil inventories
  • 11:30am: U.S. To Sell USD75 Bln 17-Week Bills
  • 1:00pm: U.S. To Sell USD13 Bln 20-Year Bond Reopening

Central Bank Speakers

  • Fed in external communications blackout ahead of the Oct. 28 FOMC decision
  • 9:00am: BOE’s Bailey Speaks in Fireside Chat
  • 12:00pm: ECB’s Lagarde Speaks in Wiesbaden

DB's Jim Reid concludes the overnight wrap

It’s been another 24 hours of uncertainty and volatility, and that’s not me talking about our household during a wet half term. In markets, what started as a widespread morning sell-off dominated by AI concerns, higher oil prices and ongoing worries over French sovereign debt turned into a more positive session as the US came in, ultimately driving the S&P 500 to close +0.28% higher as the index saw the most daily advancers since April.

Today we see the first of the hyperscalers report, with Meta out after the bell. This comes as SpaceX shares surged by about +8% in after-hours trading yesterday (vs NASDAQ Futures -0.16%), as the company exceeded quarterly revenue and net income expectations amid stronger AI revenue growth. Elon Musk also disclosed that SpaceX and Tesla have formed committees to consider a potential merger. Those results have boosted the tech mood overnight, with Nasdaq futures up +0.75% overnight, with those on the S&P +0.30% higher.

Asian bourses are also reversing yesterday’s losses this morning, which were partly triggered by a sharp fall in Korean data centre company Elice Inc (-32%) after its trading debut on Monday morning. However, they are back up +29.9% this morning highlighting the large vol in tech at the moment. Staying in Korea, the big Asian heavyweights Samsung (+4.62%) and SK Hynix (+3.91%) are also recovering helping the KOSPI (+2.61%) rebound even if it's off the highs of around +4.75% earlier in the session. Elsewhere, the Nikkei (+0.77%) is also trading higher on the tech rebound. In contrast, Chinese equities remain under pressure, with the CSI 300 (-0.65%), Hang Seng (-0.35%), and Shanghai Composite (-0.31%) all trading lower. The S&P/ASX 200 is flat.

Delving more into yesterday’s main stories now. Brent dropped from around $112 to $106 in the early London afternoon after several unconfirmed reports indicated that Qatar and Pakistan had put forward a proposal that could potentially revive talks aimed at ending the conflict in the Middle East. That in turn sparked both an equity and bond rally, as investors looked past ongoing AI worries to focus on hopes for a resolution. Later, Brent crude started to climb again, as the story was discredited by a diplomat involved in negotiations. According to Bloomberg, the diplomat said that while talks to reach a deal are ongoing, reports that the negotiating sides were close to a solution were false. After the European close we then heard Tasnim report Iran's President Pezeshkian as saying that he believes “the US will attack again if we negotiate”. So this left Brent back at $108.79/bbl by the close, -0.68% on the day but well off the day’s lows. And Brent is trading back up +1.4% at around $110.36 this morning. European natural gas futures also round tripped yesterday but ultimately declined -3.38% to €85.06/MWh, after climbing to their highest levels since 2022 intraday.

The relief from energy that played out late in the European session meant equities rallied as investors overcame some of their earlier AI jitters. Tech-heavy indices such as the Philadelphia Semiconductor Index (-0.29%) and Nasdaq (-0.02%) still underperformed, but this was a big improvement after chip stocks had been nearly -2.5% down early on. Exemplifying that intra-day swing was CoreWeave, which closed +1.65% higher on the day after trading as much as -6.36% lower near the open. Outside tech, stocks performed much better, with 403 daily advancers in the S&P 500, the most since April, while the equal-weighted version of the index rose by +1.15%.

In Europe, although stocks recovered from their morning lows, they still finished down, with the Stoxx 600 (-0.14%), CAC 40 (-0.38%) and DAX (-0.06%) all lower, whilst the STOXX Banks Index (-0.35%) edged lower to a new 4-month low. However, the euro recovered to finish +0.21% against the dollar.

Turning to bond markets, the initial sell-off also reversed later in the day, so by the close we saw yield declines led by 10yr bunds (-5.4bps), with BTPs (-4.8bps), gilts (-2.2bps) and OATs (-0.8bps) also lower. In addition to the pullback in energy late in the European session, this rally came as Germany’s ZEW investor expectations survey saw a larger-than-expected decline in October (28.1 vs 30.0 exp., 34.7 prev.). However, French bonds continued to underperform on a relative basis, with the 10yr OAT-Bund spread reaching 153bps, its widest level since 2011. So the French concerns are still there, even if the domestic unrest seems to have calmed for now.

In the US, 10yr Treasury yields also declined by -3.0bps to 5.11%, though 2yr yields (+0.4bps) ended the day little changed as oil prices reversed their decline. Earlier in the session, a decline in yields had also been supported by soft housing data for September. This included a decline in housing starts (-5.2% vs +1.9% exp.) and a sharp slowing in pending home sales, with their annual growth falling to its lowest since 2023 at -12.6% yoy. So signs of the recent rise in yields weighing on the US housing market.

In yesterday’s other data, in the UK the unemployment rate for June-Aug registered a big drop (4.7% vs. 4.9% est). So despite the number of job vacancies also falling, it was an overall hawkish batch of data, with payrolls also up by +13k. The UK inflation print is out just after this hits your inbox, but the labour market data will lean hawkish for many on the MPC and left 2yr gilts (+3.3bps) as a major exception from yesterday’s global bond rally. Staying in the UK, our economists are conducting a survey of expectations ahead of next week’s budget from the new Burnham Government. If you have a couple minutes to spare, they would appreciate your responses here.

Early morning data showed that Japan's exports increased by +16.7% in September compared to the same month last year, driven by robust demand for semiconductors and AI-related products that continued to support growth. This marked the 13th consecutive month of gains following a 9.3% rise in August, although it was below expectation of a +21.3% increase. Meanwhile, imports rose by +18.9% y/y, falling short of the forecast of a +20.4% increase. A decrease in imports contributed to reducing Japan's trade deficit to -536.6 billion yen in September from -1.11 trillion yen in the previous month.

To the day ahead, there will be a lot of data from the UK this morning, including September CPI, RPI and public finances. Central bank speakers include the ECB’s Lagarde and Cipollene and the BoE’s Bailey. We’ll also get earnings from Meta, Tesla and Lam Research among the notable names. Finally, the US is set to hold a 20yr bond auction at $13bn.

Tyler Durden Wed, 10/21/2026 - 08:18

Wall Street Set For Largest Bonuses In Industry History This Year

Zero Hedge -

Wall Street Set For Largest Bonuses In Industry History This Year

New York's financial industry is enjoying an extraordinary earnings boom, with profits potentially topping $90 billion this year and setting the stage for the biggest round of Wall Street bonuses on record, according to Bloomberg.

According to a new analysis from State Comptroller Thomas DiNapoli, securities firms generated more money during the opening six months of 2026 than in any comparable period previously recorded. If that performance continues, the industry could blow past its $65.1 billion earnings record from 2025.

Much of the surge has come from a revival in investment banking and exceptionally lucrative trading conditions. Revenue associated with underwriting jumped 68% in the first half, while advisory and account-management businesses posted a 16.4% increase. Goldman Sachs has been among the major beneficiaries, recently reporting $7.42 billion in quarterly stock-trading revenue, its third straight quarterly record in that business.

Bloomberg writes that the financial sector's success is providing a substantial boost to New York's employment figures and government finances. After reaching 207,400 workers last year, the industry is projected to expand its workforce by approximately 5,300 employees in 2026.

The state's dependence on Wall Street has also become increasingly pronounced. Securities-related business and individual income taxes delivered at least $26.3 billion to Albany during the 2025–2026 fiscal year, nearly 29% more than the prior year.

For employees, the implications are particularly lucrative. Provided markets remain relatively stable, DiNapoli believes the industry's enormous earnings could translate into unprecedented year-end compensation and bonus distributions in early 2027.

But the report also highlights a potential vulnerability beneath the financial windfall. Rising prices, international instability and technological changes associated with AI could eventually undermine the industry's performance.

And because New York now collects so much of its revenue from financial-sector activity, a sharp reversal on Wall Street would have consequences extending well beyond bankers and traders. A significant decline in profitability could quickly translate into weaker tax collections, pressure on public budgets and broader economic difficulties throughout the region.

Tyler Durden Wed, 10/21/2026 - 06:55

Franklin Templeton Warns: No One Is Ready For A Eurozone Debt Crisis 2.0

Zero Hedge -

Franklin Templeton Warns: No One Is Ready For A Eurozone Debt Crisis 2.0

New curfews in major French cities have helped contain the weeks of social unrest marked by far-left radicals and migrants burning buildings, looting mom-and-pop and luxury stores, and clashing with police. President Emmanuel Macron's failing government still faces another emerging issue: an alarming debt burden and a welfare state on the brink of collapse, addicted to decades of large deficits.

Franklin Templeton's chief investment officer for fixed income, Sonal Desai, warned that deteriorating finances could ignite another euro-area debt crisis, potentially harder to contain than the turmoil surrounding Greece.

"France has more than 10 times the debt that Greece had," Desai said in a webinar earlier today. "A simple bailout is not on the cards."

"I don't think anyone is really ready for a euro-zone debt crisis version 2.0," Desai added. "This one could be significantly worse if it were to come to pass."

She said investors shouldn't underestimate the potential for "significant volatility" in EU government bond markets. She added that Franklin Templeton's bond portfolios are positioned toward shorter-duration assets in Italy and France but have longer-duration investments in Spanish and German debt.

Earlier today, French borrowing costs climbed as investors demanded a larger premium to hold the nation's debt. This suggests mounting concerns over its debt load.

The extra yield investors demand to hold French 10-year bonds over German debt widened to 154 basis points, the highest since early October. 

"Bond markets now have much more choice over who they allocate to," said Karen Ward, chief market strategist for EMEA at JPMorgan Asset Management. "What we're seeing in France is just the bond market having this all-powerful role of having other options."

Bloomberg pointed out the possibility of European Central Bank intervention. ECB Governing Council member Olli Rehn said that all euro-area countries, including France, must bring deficits under control to ensure debt sustainability.

Jens Nordvig, president and co-founder of Vanda, warned earlier on Bloomberg TV that French spreads could widen even more.

"That cohesion, that political cooperation that is necessary for the bailout infrastructure to really work, is under pressure," Nordvig said.

In what could signal what's to come, US Treasury Secretary Scott Bessent said today that he doesn't anticipate a spillover from the French bond market.

"I don't anticipate a spillover from what's happening in France," Bessent said on conservative platform 2Way. "The French have a tough hand, but President Macron's economic team, whom I know very well, are really first-rate."

Next for France is to pare down the deficit, including reductions in welfare spending, or, in other words, fewer government handouts. And perhaps that's the real reason why the far-left and migrants who have been hooked on free government money are really rioting, not schoolchildren whom corporate media narratives describe as angry about small classrooms.

 All of this has generated tailwinds in polling for common-sense, right-wing presidential candidate Marine Le Pen, as the Macron globalists see their progressive experiment embarrassingly implode for the world to see, offering yet another reminder that welfare states and unfettered mass migration are a deadly, nation-killing, toxic mix. 

Tyler Durden Wed, 10/21/2026 - 05:45

Controversial Map In Netanyahu Briefing Triggers Wave Of Speculation

Zero Hedge -

Controversial Map In Netanyahu Briefing Triggers Wave Of Speculation

Via Middle East Eye

Israeli Prime Minister Benjamin Netanyahu unveiled a map of the wider Middle East showing his country and the UAE aligned with a paramilitary in Sudan accused of committing genocide, and separatists in Libya, Yemen and Somaliland.

The map, which carried the logo of Germany's Friedrich-Ebert-Stiftung Institute, will not surprise regional watchers, but it could prove awkward for some of Israel's regional partners and cement suspicions among Arab states.

Israel and the UAE were shown as part of a "Hexagon Alliance". The map showed Greece, Ethiopia and parts of India aligned with them. But it also showed a swath of southwestern Sudan as friendly to the UAE and Israel.

The Rapid Support Forces (RSF) control southwestern Sudan. United Nations experts and dozens of media reports, including from Middle East Eye, have revealed extensive Emirati support for the Sudanese paramilitary, which is led by former Janjaweed leader Mohamed Hamdan Dagalo and has been widely accused of committing genocide in Darfur. The UAE has officially denied backing the RSF.

The map was part of Netanyahu’s unveiling on Sunday of a new security doctrine that emphasizes preemptive strikes and the establishment of "buffer zones" on Israel’s borders.

"The War of Redemption necessitated an upgrade of fundamental principles within the traditional national security doctrine, among them: giving priority to prevention and offense over containment and defense, including launching preemptive strikes to thwart evolving threats; strengthening home front defense against new threats; cementing Israel's status as a regional power," Netanyahu’s office said in a statement on Sunday.

"Opportunities have been created for forging new alliances in our region and beyond," the statement added.

'Sunni Diamond Alliance'

The map Netanyahu shared shows Israel aligned with secessionist groups while framing its oldest Arab treaty partners as countries not considered friendly to Israel. The map did not show Egypt and Jordan as aligned with Israel.

Instead, it marked Egypt as part of a "Sunni diamond alliance" with Pakistan, Turkey, and Saudi Arabia; it showed Jordan, whose peace treaty with Israel dates back to 1994, as "friendly" to the alliance.

Netanyahu's public presentation is likely to raise concerns among critics about Israel’s support for secessionist groups and the partition of fragile states. He showed a government in eastern Libya controlled by Khalifa Haftar to be aligned with Israel. 

Yemen's Southern Transitional Council, a UAE-backed separatist movement that dissolved in January 2026 and re-emerged as the Transitional Council of South Arabia, was also shown on the map as being friendly towards Israel and the UAE

Israel became the first country to recognize Somaliland earlier this year. Somaliland is a breakaway republic of Somalia where Israel and the UAE have been expanding their military presence, according to multiple media reports.

Netanyahu’s map showed how Israel sees its security as part of a broader region extending well beyond the Arab world.

He showed Greece and Ethiopia as "friendly" states. The latter is on the verge of a full-scale war with Eritrea, where Israel has long coveted a Red Sea military base, MEE has reported.

Netanyahu's map also reaffirmed the longstanding ties between Hezbollah, the Houthis and Iran as part of an "Axis of Resistance". 

Tyler Durden Tue, 10/20/2026 - 20:30

Pages