Zero Hedge

Nearly 15,000 ICE Detainers Not Honored In New York City, DHS Says

Nearly 15,000 ICE Detainers Not Honored In New York City, DHS Says

Authored by Naveen Athrappully via The Epoch Times,

A total of 14,916 immigration detainers issued by Immigration and Customs Enforcement (ICE) were not honored by New York City due to its sanctuary policies, according to the Department of Homeland Security.

There were 47,750 criminal charges and convictions linked to these detainers that New York City ignored between Jan. 20, 2025, and Sept. 14, 2026, Homeland Security said in an Oct. 9 statement.

An immigration detainer is a request from ICE asking local, state, or federal law enforcement agencies to notify the agency before releasing a removable immigrant or to hold the individual for up to 48 hours beyond the scheduled release time so that the Homeland Security can take custody of the person.

"Sanctuary politicians create an environment for criminal activity to thrive, not for American citizens to be safe," Homeland Security Secretary Markwayne Mullin said in the statement. "When you have sanctuary cities and politicians, you endanger the safety of the public."

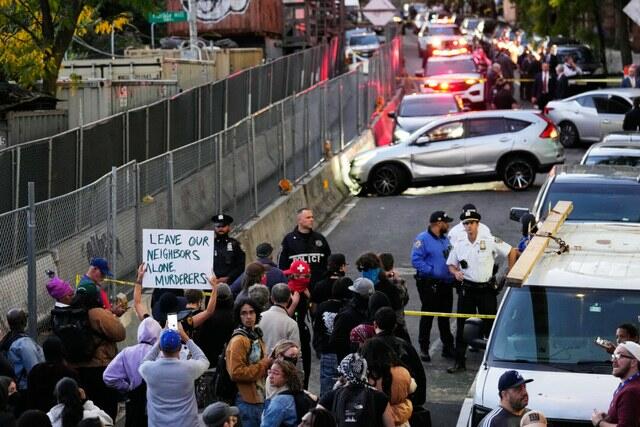
The Homeland Security statement was issued in the context of a recent shooting of Oscar Bengal, a criminal illegal immigrant in New York. Bengal, from the Dominican Republic, was shot on Oct. 8 while federal immigration agents were attempting to arrest him in the Bronx.

Bengal was sent to a local hospital for treatment and subsequently placed in detention.

The illegal immigrant had previous criminal convictions for grand larceny and has been arrested for drug possession, assault, weapons charges, and robbery, according to Homeland Security. He is allegedly associated with the Trinitarios street gang, which is implicated in the murder of a Border Patrol officer last year.

Bengal had entered the United States illegally and was arrested by the New York Police Department in December 2023. However, he was released back into the community in a few days due to sanctuary policies, Homeland Security said.

"When dangerous illegal aliens are released back onto the streets by radical sanctuary politicians, our officers are forced to make arrests at large in the community in unpredictable and dangerous environments," Homeland Security said in another statement.

Among the 47,750 criminal charges and convictions, the crimes include homicides, sexual assaults, drug offenses, kidnapping, weapons offenses, and assaults, Homeland Security said.

In July, New York Gov. Kathy Hochul wrote a letter to Mullin, criticizing the immigration enforcement actions being carried out in the state.

"My long-standing policy has always been that we will cooperate with law enforcement when crimes have been committed, and there is a warrant for arrest or a court order, because we want our streets to be safe as well; but this unbridled aggression against law-abiding New Yorkers must stop," Hochul said.

"Instead of focusing on the worst of the worst, your administration is detaining neighbors and coworkers, separating families, and secretly building the infrastructure to detain even more people."

According to New York's January 2025 guidance update for local authorities regarding immigration enforcement, there is no legal obligation for a local law enforcement agent to detain an individual pursuant to an ICE detainer.

In September last year, Homeland Security sent letters to multiple sanctuary states, including New York, requesting compliance with ICE detainers, in line with federal immigration regulations.

In December 2025, Homeland Security said that New York had released 6,947 criminal illegal immigrants, failing to honor ICE detainers. In addition, there were, at the time, 7,113 immigrants in custody in New York with an active detainer, accused of crimes such as assaults, homicides, and sexual predatory offenses.

Homeland Security said in its latest statement that Hochul brought in legislation barring local law enforcement from cooperating with ICE.

"Here in New York, we need local police focused on keeping our communities safe - not serving as de facto ICE agents, not conducting civil immigration enforcement," Hochul said in an Aug. 25 statement.

The legislation took effect on Aug. 25, after which 15 county sheriffs sued the New York government to overturn the ban.

New York is one of the states the Department of Justice has designated as following sanctuary policies, which can include placing limits on ICE detainers and restricting ICE agents' access to jails for immigration enforcement.

Other states that, at the time, designated such policies include California, Colorado, Connecticut, Delaware, Illinois, Minnesota, Oregon, Rhode Island, Vermont, and Washington. In addition, the District of Columbia and multiple counties and cities were also designated as having implemented sanctuary policies.

Tyler Durden Mon, 10/12/2026 - 17:00

Polymarket Sees 69% Chance Guilfoyle Out By Month's End As Trump, Rubio Weigh Firing

Polymarket Sees 69% Chance Guilfoyle Out By Month's End As Trump, Rubio Weigh Firing

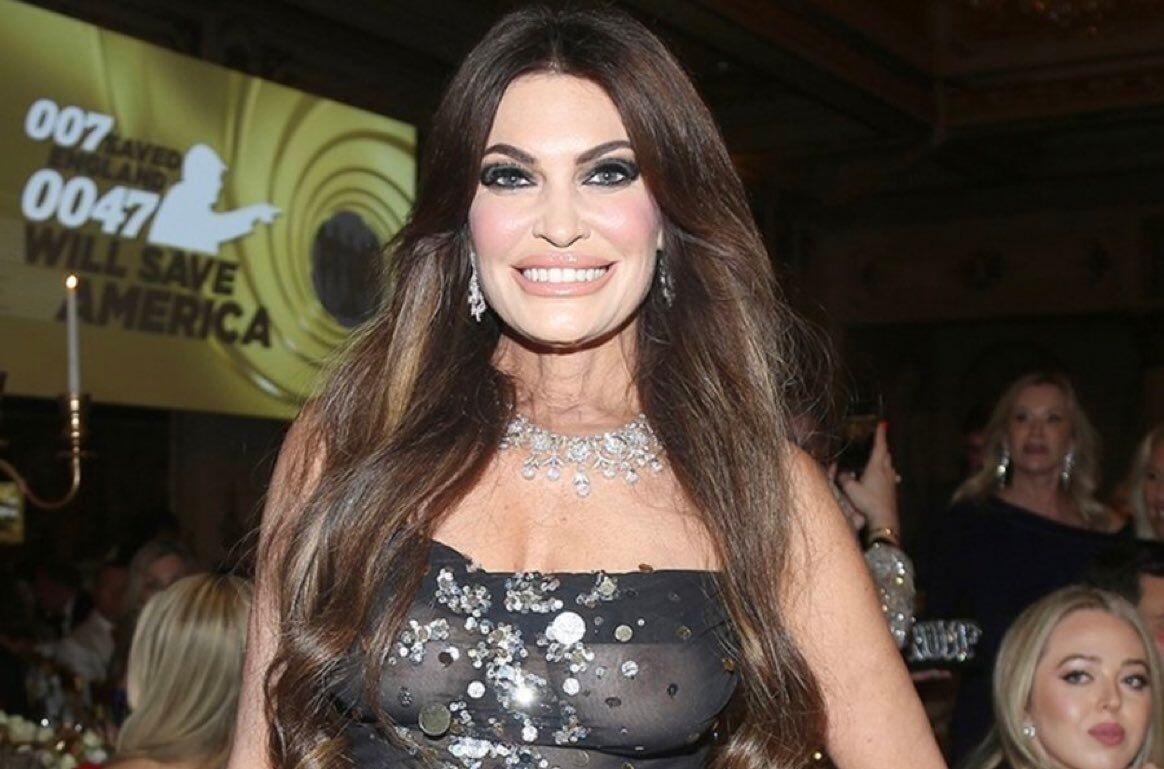
Prediction markets have dramatically repriced the tenure of Kimberly Guilfoyle as US Ambassador to Greece.

As of Monday, Polymarket traders put a 69% probability on her being out of the post by October 31 - up sharply from the mid-single digits just days earlier - after reporting that President Trump and Secretary of State Marco Rubio are actively considering her removal.

//--> Kimberly Guilfoyle out as U.S. Ambassador to Greece by October 31?
Yes 69% · No 34%
View full market & trade on Polymarket

A senior U.S. official told the Associated Press that Trump and Rubio are "extremely pissed off" by the accumulating allegations of improper conduct and would likely decide this week after the Columbus Day holiday. Rubio was described as particularly angry: he had just visited Athens, where Guilfoyle attended most of his events and greeted him with a bear hug as the stories circulated. The State Department's inspector general is examining the claims.

This follows ZeroHedge's earlier coverage of the two main strands of Wall Street Journal reporting that have driven the controversy. In late September we noted the firestorm after Guilfoyle was reported to have told Greek officials, during a March dinner discussing the collapse of Romania's government, that "We can do that to any country we want. We can do that here." The Journal has also detailed her promotion of a Greek construction and energy company's interests (Aktor Group) across the Balkans, including allowing its lobbyist into diplomatic meetings, while pushing U.S. LNG sales via the "vertical gas corridor."

Days later the Journal published the donor texts: six days before her July 9, 2025 Senate confirmation hearing, Guilfoyle allegedly messaged Trump donor Eric Deters on Signal asking him to wire $100,000 to her American Express account in a way that "won't show up anywhere," while he sought her help securing administration attention on personal tax and legal matters. Deters has said the relationship involved roughly $300,000 in prior appearance fees and discussions of up to $1 million more for influence; he has called the $100k request "absolutely a quid pro quo" and labeled her "a grifter." Her lawyers have disputed the authenticity of the messages and said any money sought related to unpaid pre-nomination speaking fees.

Newer Journal reporting has added claims of luxury travel funded by Greek businessmen. At the World Economic Forum in Davos, Guilfoyle was recorded boasting about flying on a private jet with Aktor CEO Alexandros Exarchou and later traveling with shipping tycoon Nikolas Tsakos; she reportedly told an American businessman seeking an invitation to an Eric Trump dinner, "You know, I can deliver the world to you... I'm going to make you a lot of f-ing money." Embassy statements have said she followed State Department ethics and gift-reporting guidelines.

Her legal team (David Schwartz and Jesse Binnall) issued a statement late Sunday denying wrongdoing, asserting compliance with regulations on private travel, and indicating they are evaluating legal remedies over the claimed speaking-fee debt. Rubio had praised her as an "incredibly effective advocate" in a statement ahead of his Athens visit, and while there called her a "strong ambassador" even as he refused to address the reports, telling journalists that press accounts are "not the gospel." Trump has previously described the situation as "too bad" while saying he had heard little and that she was "always very nice."

The Polymarket contract resolves "Yes" if Guilfoyle ceases to be ambassador for any period before the stated date (including via announcement of resignation or removal), based on official information or a consensus of credible reporting. Volume has climbed past $60,000 total as the October 31 contract moved from the mid-single digits into the 60s over the weekend; the December 31 contract sits around 73%.

Tyler Durden Mon, 10/12/2026 - 16:40

"Too Combustible": New York Times Calls For Canceling Sophie Cunningham

"Too Combustible": New York Times Calls For Canceling Sophie Cunningham

Authored by Jonathan Turley via JonathanTurley.org,

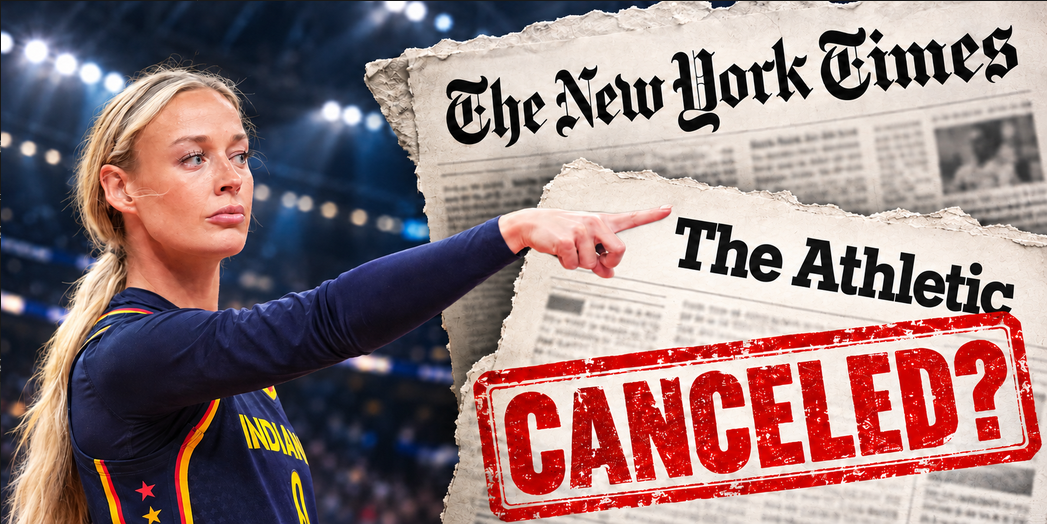
The New York Times demonstrated again this week that it remains solidly part of the cancel campaign culture. The Athletic, owned by the Times, joined the mob in calling for the Indiana Fever to dump Sophie Cunningham for publicly opposing biological males playing in women's sports - a position shared by the vast majority of citizens.

The column by Candace Buckner blames Cunningham for creating a "circus" and says that she is a distraction from the game due to her public stance. So, she is now "too combustible, her takes too "turbulent" to play basketball.

Of course, if she supported transplayers, she would presumably not be combustible but admirable.

Notably, the Times does not view those who have attacked Cunningham and her fans as too "combustible," including coaches wearing opposing slogans and statements in favor of biological males in women's sports. The New York Times itself reported that almost 80% of citizens hold the same position as Cunningham.

The Oct. 6 column called on Indiana not to renew Cunningham's contract after two seasons when she becomes a free agent because she is "too combustible."

However, the Times does not believe that those coaches and players speaking out in favor of such inclusion are "too combustible."

There was no call for sacking figures like Storm co-owner Celeste Keaton, who reportedly yelled profanities at girls who were simply supporting women in sports and Cunningham.

Nor was there a call to sack Minnesota Lynx head coach Cheryl Reeve for wearing a T-shirt supporting trans players in a game against the Indiana Fever and Cunningham.

Liberal sentiments are never combustible for the Times. The newspaper ran a long line of columns supporting Colin Kaepernick in his kneeling protests during games. Conversely, columns attacked former player Enes Kanter Freedom for wearing a T-Shirt reading "WOMAN noun. adult human female."

For most of us, the hatred for Cunningham is baffling. These athletes have a unique perspective on this controversy that can help inform the debate on both sides. We should welcome the insights of athletes for and against transgender players in this national discussion.

Instead, Cunningham has been subject to the same hateful, unhinged attacks that we have seen on other influential figures such as J.K. Rowling. There is no room for civil debate or any difference of opinion.

The purpose of these campaigns is obvious. Even with the vast majority of citizens supporting Cunningham's position, press and pundits want to deter others from publicly taking such positions. It is designed to chill speech and deter dissent.

On Friday's episode of "No Hesitation with Sophie Cunningham & Drew Hanlen," Hanlen correctly called the piece an "absolute hate piece." Cunningham responded even more succinctly to the Times with "suck it."

I am not concerned for Cunningham, who has shown great courage and steadfastness in the face of these critics. Rather, it was the latest evidence that the Times has changed little in fueling the mob and canceling opposing voices.

The Times has thrilled the extreme left with its signature relativism in defending any abuse on the left, from looting to murder. It has continued to feature violent extremists as political attacks rise around the country.

The same newspaper that fired editors and denounced Sen. Tom Cotton for his NYT column quelling violent protests would go on to print individuals who have said that they are ok with killing conservatives or capitalists.

Just before the anniversary of the Cotton controversy, the New York Times published a column by University of Rhode Island professor Erik Loomis, who defended the murder of a conservative protester and said that he saw "nothing wrong" with such acts of violence.

After canceling Sen. Cotton, the Times had no problem with publishing the views of a Chinese figure called the enforcer of Beijing in the crushing of protests.

The New York Times is undeterred because its readers seem to value the very hypocrisy revealed in these controversies. They can rely on the Times to offer spins and deflections to relieve them of any self-examination after tragedies like the Kirk assassination.

While denouncing disinformation, the Times has embraced false narratives and continues to publish distorted historical claims.

As with its cancellation of Sen. Cotton, the Times shows that the left is ready to resume the prior campaign of cancel campaigns and censorship of opposing views. That includes an athlete who merely voiced a view in favor of female athletes that is shared by roughly 80 percent of the country. It is not shared by the Times or its viewers, so (once again) Cunningham must go.

Opposing viewpoints are intolerable to many on the left, and the editors of the Times are once again rationalizing the worst impulses of American politics.

* * *

Tyler Durden Mon, 10/12/2026 - 16:20

DOJ Lacks Authority To Check Voter Lists Against Immigration Database, Judge Says

DOJ Lacks Authority To Check Voter Lists Against Immigration Database, Judge Says

Authored by Zachary Stieber via The Epoch Times,

The Department of Justice (DOJ) cannot take the names of registered voters and compare them against a federal immigration database, a federal judge has ruled.

U.S. District Judge Sparkle Sooknanan, based in Washington, handed down an order on Oct. 9 against the department.

The DOJ has been requesting lists of registered voters from states and, after obtaining them, checking them against the Systematic Alien Verification for Entitlements service, which contains citizenship information.

When people are identified as registered to vote despite not being citizens - according to the SAVE database - the DOJ has been demanding that states remove them from voter rolls.

"The challenged policy represents the federal government's attempt to decide who gets to vote," Sooknanan said. "But Congress has left that authority where our Constitution has always placed it: with the states."

She also said that the department "cannot run roughshod over longstanding laws that were carefully crafted to protect the rights of the American people."

The DOJ did not respond to a request for comment by the time of publication.

"The Trump administration has repeatedly taken extreme measures to interfere with how elections are run, undermine confidence in the results, and create confusion," Ming Cheung, a senior staff attorney with the American Civil Liberties Union, which is representing plaintiffs who sued over the policy, said in a statement.

"This effort to seize sensitive voter data is part of that same pattern, and today's ruling makes clear that the administration cannot use the federal government to disrupt elections or put voters' rights at risk."

Common Cause and Citizens for Responsibility and Ethics in Washington sued in April, arguing the effort to build a national voter database with the files from states was illegal in part because the DOJ planned to disclose confidential voter data to contractors to help verify the status of the voters and force states to remove voters identified as lacking citizenship.

"No federal statute authorizes DOJ's sprawling new voter surveillance, data consolidation, and purging operation," they said.

Government lawyers said that Congress authorized the department to enforce voting laws, including the National Voter Registration Act, and that the effort was part of that enforcement.

The act says states must make a "reasonable effort" to remove ineligible voters from voter lists and says the attorney general can sue states if they do not comply with the law.

The DOJ created the policy after President Donald Trump directed the attorney general to work with states to identify suspected violations of election laws, including voting by ineligible individuals.

Sooknanan said that the laws the government cited do not authorize the policy.

"It would turn these voter-protection laws on their head to find that they authorize DOJ's unprecedented actions," she wrote.

The National Voter Registration Act, for instance, emphasizes the role states have in maintaining voter rolls and does not empower the DOJ to demand voter data from states, the judge said.

She vacated the DOJ's effort to maintain voter lists.

The ruling came several weeks after the Supreme Court paused a ruling by Sooknanan in a related case that had blocked the government from using an expanded version of SAVE to verify voters' citizenship.

Tyler Durden Mon, 10/12/2026 - 15:40

The Biggest Threat To Today's Data Centers Is In The Battery Room

The Biggest Threat To Today's Data Centers Is In The Battery Room

Authored by David Ellis via Data Centre Dynamics,

As data centers continue to multiply, facilities are deploying industrial-scale Uninterruptible Power Supply (UPS) units by the hundreds and substation-size front-of-the-meter Battery Energy Storage Systems (BESS) to secure against grid failure, power surges, or other disruptions.

But while the battery units are looking after the servers, who is looking after the batteries?

In the last few years, lithium-ion batteries have become the backup power of choice for data center UPS and BESS systems, and for good reason. They have long lifespans, a small footprint, and superior energy density. While data centers tend to be safe, things can and do go wrong. When they do, it's almost always related to lithium-ion batteries.

The September 2025 data center fire in South Korea that led to a paralyzing nationwide outage in government services started with a single lithium battery explosion. Last year, a battery room at the Chirisa Technology Parks data center in Virginia caught fire twice in two months. Firefighters who responded to a May 2025 fire at an Oregon data center leased by X flagged the battery room as the source of the blaze. As the National Fire Protection Association (NFPA) noted recently, "Nearly every notable fire event in data centers in recent years has involved lithium-ion batteries in some way."

The biggest safety threat to modern data centers' backup battery systems falls on a single culprit: hydrogen. When a lithium-ion cell begins to fail, internal temperatures rise rapidly, forcing a breakdown in the battery's internal chemistry. Hydrogen, the smallest and lightest molecule, is often the most measurable gas during the initial stages of failure. Unlike traditional vented lead-acid batteries, lithium-ion cells do not regularly emit hydrogen gas. When 'off-gassing' does occur, it usually means something has gone very wrong. Overcharging, cell damage, separator defects, internal short circuits, or even the formation of tiny lithium dendrites can trigger a state known as thermal runaway. If early warning detection systems are not installed, this is when things get dangerous fast.

Once thermal runaway is triggered, it's a self-sustaining chain reaction. Rising heat melts the battery's internal separator, causing a short circuit that rapidly generates heat. The extreme heat drives internal thermal decomposition, which releases fuel and oxygen. The release of oxygen feeds sustained combustion that can spike to more than 1,000°F (538°C) in a matter of seconds. Because the cell is sealed, the extreme heat and pressure cause the battery to burst into flames that can ignite neighboring cells and equipment.

While industry data shows a steady decline in BESS failure rates per gigawatt-hour of deployed capacity, the stakes are still high. Because the large-scale shift to lithium-ion battery configurations has only taken place during the last 3-5 years, hyperscalers, regulators, and insurers are beginning to catch up to the reality that lithium-ion deployments do not conform to legacy safety protocols.

Previous safety best practices that focused on ventilation to prevent critical concentrations of hydrogen during regular off-gassing are no longer sufficient for today's battery rooms. Energy-dense lithium-ion cells are often packed in enclosed cabinets. This makes for a small footprint that can trap volatile gas beyond the reach of traditional ventilation units. Given the potential for a sudden flare-up, the safety approach for these configurations has shifted from ventilation to early-stage off-gas detection.

Regulations and standards are evolving accordingly to prioritize early detection and prevent worst-case scenarios. Standards like NFPA 855 were designed specifically for lithium-ion deployments, mandating continuous gas detection alongside standard exhaust systems.

Destructive testing standards, like UL 9540A, generate the fire-propagation data that inform spacing and suppression requirements in model codes and standards like NFPA 855. Additionally, UL 2075, a standard covering gas and vapor detector performance, is now being used in modern BESS and UPS environments to certify specific gas or off-gas detectors used to monitor hydrogen and hazardous gas accumulation in battery rooms.

While the standards and regulations evolve, their practical implementation has not kept pace with the scale of data center deployments. Designing a battery room layout that complies with specific standards and local fire and safety requirements is not exactly intuitive, nor is it top-of-mind for data centers focused on uptime and speed-to-market. Backup battery systems are largely treated as a necessary investment to satisfy stakeholders. In practice, the safety systems underwriting hyperscale battery deployments are not just check-boxes; they're the first line of defense keeping the facility online and off the front-page news.

Anyone who has bought the wrong smoke detector for their home understands that not all safety equipment is created equal. Some battery room gas sensors are overly sensitive and cause false alarms, like the smoke detector that goes off anytime there's a pan on the stove. Some gas sensors quickly lose calibration and require regular maintenance. Other sensors are not designed for integration into today's smart anti-explosion and fire systems and building management systems.

When it comes to safety, too many data centers are left guessing. Industry standards and certification are making it easier for hyperscale operators to identify what they need to optimize safety. But with highly compressed timelines between standard operations and a thermal incident, it's critical to monitor the very first signs of catastrophe. For today's gigawatt-scale data centers, the earliest sign of failure isn't smoke or fire, but hydrogen silently venting in a battery cabinet.

Data centers are rightly focused on delivering massive compute density and next-generation AI chips, but the systems powering those capabilities need rigorous attention as well. Securing a multi-billion-dollar deployment goes beyond acknowledging the thermal risks inherent in modern backup power systems to actively tracking the element responsible for turning a potential risk into an active crisis.

Tyler Durden Mon, 10/12/2026 - 15:00

DOJ Probes 5 Major TV Networks Over Suspension Of Pool Coverage

DOJ Probes 5 Major TV Networks Over Suspension Of Pool Coverage

Authored by Aldgra Fredly via The Epoch Times,

The Department of Justice (DOJ) is probing five major television networks for possible antitrust violations following their brief suspension of pool coverage of President Donald Trump last month.

A DOJ spokesperson said on Oct. 10 that the probe would look into whether CNN, ABC, NBC, CBS, and Fox News violated the federal antitrust laws when they halted their presidential pool coverage on Sept. 21 in protest of Trump's decision to ban CNN, MS NOW, and Politico from the White House.

The networks resumed coverage a few days later, after the administration reinstated the credentials of the three outlets under a court order.

"Group boycotts among commercial competitors can violate the Sherman Act," the spokesperson said in a statement.

The Sherman Act was enacted in 1890, aiming to prevent monopolistic practices and promote competition.

The five networks did not immediately respond to a request for comment. The Epoch Times reached out to the DOJ for further details but did not receive a response by the time of publication.

In an Oct. 10 statement, Reporters Committee President Bruce D. Brown accused the Trump administration of trying to obtain "records from the networks about how they are covering daily White House events during a media ban the president himself put in place."

"The decisions news organizations make about coverage are protected by the First Amendment, and summoning antitrust authority, on top of the retaliatory actions the White House has already taken to bar certain outlets, is another and even more brazen attempt to try to intimidate journalists," Brown said.

The five broadcast networks make up the White House television pool, which shares responsibility for filming and sharing footage of the president.

Trump announced the ban on CNN, MS NOW, and Politico from the White House on Sept. 18, accusing them of reporting "fake news."

In a Sept. 22 filing asking the court to deny the outlets' lawsuit challenging the ban, the DOJ said the three outlets had "failed to maintain basic minimum standards of professionalism and decorum expected to those given access to the White House Complex, including by publishing sensitive or classified information."

U.S. District Judge Timothy Kelly granted a 14-day temporary restraining order on Sept. 24, requiring the administration to restore hard pass access for the three outlets. The order was set to expire on Oct. 8, but Kelly extended it through Oct. 13 after the outlets requested a preliminary injunction.

The outlets alleged that the White House has "persisted in unpredictably and inconsistently implementing its ban," citing its move to exclude CNN from television press pool duties on Sept. 26.

In an emailed statement to The Epoch Times on Sept. 28, a White House official called Trump "the most accessible president in history," citing his efforts to hold press events, regular gaggle sessions, and interviews, take questions from reporters, and engage with the public through social media posts.

"Even after outlets were given access to the White House, they declined to cover various events, proving this isn't about access. It's performative and dishonest," the official said.

Tyler Durden Mon, 10/12/2026 - 14:20

Russian Tech Giant Yandex's Connectivity "Collapses" As Kiev Targets Data Centers

Russian Tech Giant Yandex's Connectivity "Collapses" As Kiev Targets Data Centers

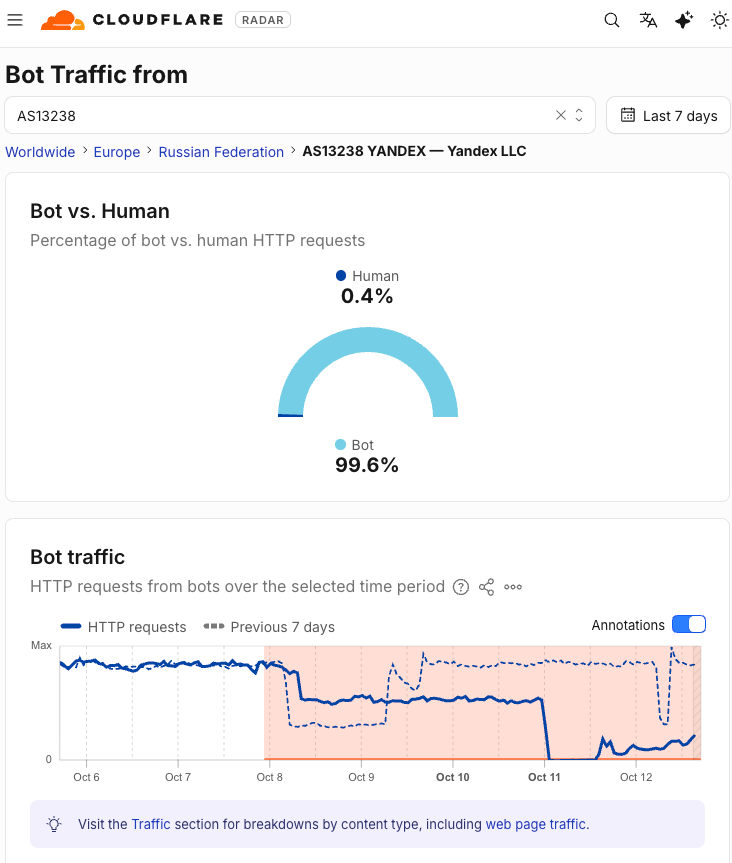
Data from the internet monitoring group NetBlocks show a sharp collapse in connectivity across Russian tech giant Yandex's networks following Ukrainian drone strikes on its data centers.

Separately, internet infrastructure company Cloudflare reports a collapse in bot traffic originating from Yandex's network, raising questions about whether the disruption affected bot farms used for information operations. Others have pointed out that the decline may reflect reduced activity by Yandex's web crawlers.

Traffic initially tumbled to about 57% of its peak last Thursday, coinciding with a Ukrainian drone strike on Yandex's Sasovo facility, which housed two supercomputers. A separate drone attack knocked a much larger data center in Kaluga offline, while Bloomberg reported a third strike on another Yandex data center.

The Moscow Times reports that Digital Development Minister Maksut Shadayev is working to protect Yandex's data centers following Ukrainian drone strikes on three of its facilities.

Shadayev told a parliamentary committee earlier on Monday that he had spoken with the Defense Ministry about how to secure Yandex's data centers. He described the attacks as "unprecedented."

Industry insiders told Russian business daily Kommersant that fixing damaged server equipment could take up to six months. Shadayev said backup systems and computing capacity elsewhere helped keep operations running.

With bot traffic from Yandex's network curtailed, X users are reporting that traffic on some Reddit subs has cratered...

At least the Ukrainians focused on data centers this time, instead of continuing the refinery attacks the US has asked Kiev to stop because of the worsening global refining crisis.

Tyler Durden Mon, 10/12/2026 - 14:05

Judge Orders White House To Stop Airing Taxpayer-Funded Ads

Judge Orders White House To Stop Airing Taxpayer-Funded Ads

Authored by Aldgra Fredly via The Epoch Times,

A federal judge on Oct. 11 issued a temporary restraining order barring the White House from airing the remaining slots of taxpayer-funded television ads featuring President Donald Trump and his administration's policies and achievements.

U.S. District Judge Jennifer L. Rochon said the motion filed by watchdog group Common Cause, candidate for Alabama State House Robert Hunter, and Service Employees International Union 32BJ and its political action committee had the legal standing to challenge the White House ads.

In a four-page ruling, Rochon said the plaintiffs have shown they were likely to succeed on the merits of their arguments and that issuing a block would serve the public interest. The judge also found that the plaintiffs would suffer irreparable harm if the restraining order was not granted.

Rochon barred the administration from "using, disbursing, or transferring funds appropriated to the Department of Homeland Security to develop, create, disseminate, place, distribute, publish, or air the challenged advertisements."

The judge also ordered the administration to cancel ads scheduled for broadcast on Oct. 11.

The order named the Department of Homeland Security and its chief Markwayne Mullin, Office of Management and Budget Director Russell Vought, and White House Chief of Staff Susie Wiles as defendants.

In a statement, the plaintiffs praised the judge's decision, saying it would help to prevent the use of taxpayer money on what it called "unlawful political propaganda."

"There is no legal justification - and no precedent - for the president to use the machinery of the government and funds set aside by Congress for other uses to influence electoral outcomes that further his own agenda," they said.

The Epoch Times reached out to the White House and the Department of Homeland Security for comment but did not receive a response by the time of publication.

The White House has previously said the ads were not campaign ads, noting that Trump is not on the ballot in the November election.

"These public service announcements are unapologetically American, clearly disclosed, and aimed at the country - not a line on the ballot," it said in a Sept. 25 statement.

The White House also cited examples of past administrations from both parties using such ads to explain their policies and promote their visions for the nation.

In an Oct. 7 lawsuit, the plaintiffs alleged that the Department of Homeland Security had signed a $20 million contract for the national broadcast of the ads.

The Democratic National Committee (DNC) filed a separate suit on Oct. 7 accusing the White House of violating federal budget rules by using taxpayer money to fund the ads.

Trump defended the ads on Oct. 5, saying it was "a rather standard thing to do" for an elected president and their administration.

"The Radical Left is upset with the fact that I am taking Ads, which I consider to be a positive promotion for our Great U.S.A., and paying for them with U.S.A. money," he said in a Truth Social post.

Trump said he would pay for the ads using his own money and the funds he raised for his MAGA Inc. political action committee.

Tyler Durden Mon, 10/12/2026 - 13:45

BofA Bets On Copper And Uranium As Higher Rates Put Gold Under Pressure

BofA Bets On Copper And Uranium As Higher Rates Put Gold Under Pressure

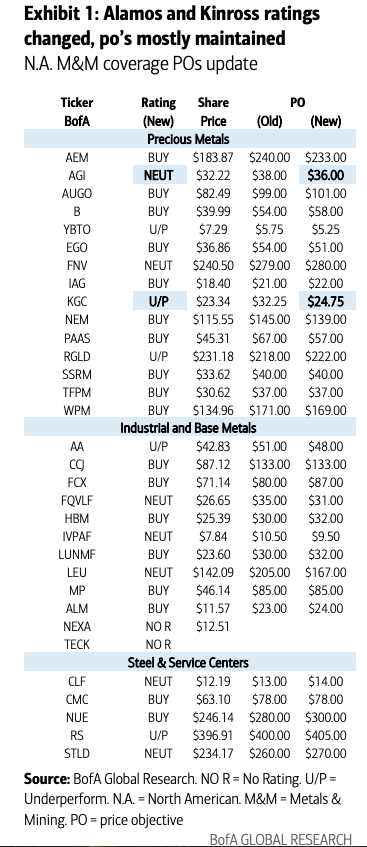
Bank of America metals and mining analyst Lawson Winder shared his latest outlook for the space in a Friday note titled, "We like copper and uranium, while rates should keep a lid on gold prices."

Winder said his desk favors copper and uranium producers as global supply constraints collide with soaring power-grid demand, supporting higher prices for these commodities. He pointed out that higher US interest rates should keep the dollar bid while weighing on gold.

On single stocks, BofA downgraded Kinross Gold to Underperform and Alamos Gold to Neutral. Freeport-McMoRan remains BofA's top copper stock, while Cameco is its top uranium pick.

For base metals, Winder said copper is the strongest industrial metal. He said constrained supply and long-term electrification demand support higher prices. His desk raised its 2026 average copper forecast by 3% to $13,278 a ton and increased its long-term estimate by 20% to $13,578, adding that prices could average $15,250 in 2027.

He lifted his Freeport price target to $87 from $80, citing progress in the Grasberg operational turnaround and prospects for production growth.

Uranium is another favorite for BofA analysts, even though they cut their 2026 average estimate for the radioactive metal used in nuclear fuel rods to about $97 a pound. They maintained their 2027 projection near $130, roughly 45% above the spot price cited in the report.

Cameco offers one of the top exposures to both uranium prices and nuclear buildout through its 49% stake in Westinghouse, the analyst said. He maintained his "Buy" rating and a $133 price target on one of the world's largest providers of uranium fuel for clean nuclear power.

Here's the full list of precious metals, industrial and base metals, and steel stocks in Winder's coverage universe:
Extended explanation of the coverage universe:

Agnico Eagle Mines (AEM)

Our $233 per share price objective is based on Agnico Eagle trading at 2.00x times our estimated NAV (current net debt position plus a mining asset DCF utilizing a 5% WACC). Historically, North American gold producers have traded between 1 and 2 times NAV, with 1.75-2.0 times being accorded to the organically growth-oriented gold producers such as AEM.

Risks of this price objective not being attained are commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, and political risk in the countries the company operates in. Upside risks are commodity price strength, better-than-forecast operating performance and favorable changes in the political environment in the regions where it operates.

Alamos Gold (YAGI / AGI)

Our price objective for Alamos Gold (AGI/YAGI) is US$36.00/C$51.00, based on the stock trading at 1.00x our estimated net asset value (NAV) and a 1.42 CADUSD FX rate. Historically, North American precious metal producers have traded between 1x and 3x NAV but more recently between 1x and 2x, with unhedged, growth-oriented producers occupying the upper end of the range and Junior and Mid-tier producers trading historically at a discount to the senior producers.

Upside risks to our PO are a higher-than-forecast gold price, a lower-than-forecast CADUSD FX rate, exploration success at Island, Mulatos and Young-Davidson, better-than-expected synergies at Magino, advantageous changes to the regulatory and/or tax regimes in the jurisdictions in which they operate, and the potential for AGI to be acquired at a premium valuation.

Downside risks are a lower-than-forecast gold price and higher-than-forecast CADUSD FX rate, risks of the Argonaut transaction not receiving regulatory approval, operational challenges with the Magino mine, risks associated with undertaken M&A (such as with respect to integration of assets), and unforeseen operating and development issues at other assets.

Alcoa Corporation (AA)

Our price objective of $48.00 for AA is based on 4.0x 2026E EV/EBITDA, 3.5x 2027E EV/EBITDA and 1.0x net asset value (NAV), with each value equally weighted. The 4.0x 2026E EV/EBITDA target multiple is below the lower end of the global aluminum producer peer average of 4-5x due to our more bearish outlook for alumina from the BofA Global Research Commodities team as well as continued overhang related to Section 232 tariffs, San Ciprian/Alumar restart and Western Australia bauxite permits. The 3.0x is also below AA's historical trading average (since 2016 separation) of 5x. The 3.5x 2027E EV/EBITDA multiple is lower than the 2026E multiple to account for time value. The 1.0x price to NAV (P/NAV) target multiple is in line with our broad NA metals and mining coverage.

Downside risks to our price objective are 1) aluminum price weakness, 2) extended delays in getting its bauxite mine approvals in Western Australia, 3) pension liabilities, 4) higher raw materials costs including electricity, oil, caustic soda, coke, and pitch, 5) power contract negotiation risk (electricity is a large cost component), 6) power disruption risk and other unforeseen weather-related risks, 7) political, regulatory and country risks, 8) unfavorable currency changes including in the BRL, CAD, EUR, ISK and NOK, and 9) the removal of protective tariffs in markets.

Upside risks to our price objective are 1) higher aluminum prices, 2) better-than-expected cost containment, and 3) global demand growth.

Almonty Industries Inc (ALM)

Our $24 price objective (PO) is based on 8.0x 2027E EV/EBITDA, 7.5x 2028E EV/EBITDA, and 1.0x P/NAV. We think the target multiples are conservative as they are discounted to critical mineral stocks that trade around 25x 2026E EV/EBITDA. At 8.0x 2027E EV/EBITDA, our target multiple would be in-line with historical trading average of the copper stocks (which we consider more industrial metal stocks but have some elements of critical mineral stocks), and a substantial discount to the current 25x trading multiple of the critical mineral stocks). Our 7.5x 2028E EV/EBITDA target multiple is a standardized (0.5x) discount to 2027E to account time value risk. While our 1.0x P/NAV target multiple is typical for copper and critical mineral stocks, it does reflect a substantial discount to where both groups are now trading.

Upside risks to our PO are higher than expected tungsten prices (whether accelerating demand or continued supply challenges), weaker local currencies than expected that reduce USD operating costs (i.e. EUR, KRW), the build-out of key projects that are not included in our current forecasts (Los Santos, Valtreixal, Gentung), and the potential for ALM to become the subject of an acquisition.

Downside risks to our PO are lower than expected tungsten prices (whether slowing demand or greater than expected supply), stronger local currencies than expected that increase USD operating costs (i.e. the EUR and KRW), and operational challenges.

Aura Minerals (AUGO / XEDTA)

Our price objective for Aura Minerals is US$101.00 and R$169.00 per share, and is based on the stock trading at 1.35 times our estimated net asset value (NAV). Our NAV is based on a 5% discount rate and a long-term gold price of $3,500/oz. In recent history, North American precious metal stocks have traded between 1 and 2 times NAV, with unhedged, growth-oriented producers with solid balance sheets occupying the upper end of the range. Our 1.35x NAV for AUGO is at a premium to the average of Intermediate/Junior (Jr) peers in our coverage to recognize its peer leading production growth profile.

Upside risks to our price objective are stronger-than-forecast commodity prices, lower than expected costs, positive regulatory, permitting or operating developments and significant success in exploration.

Downside risks to our price objective are unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs, and delays in the development of its growth projects.

FX and controlling shareholder influence could be risks in either direction.

B2Gold Corp (YBTO / BTG)

Our price objective for B2Gold (BTG/YBTO) is US$3.75/C$5.25 based on the stock trading at 0.75x our estimated net asset value (NAV). Historically, North American precious metal stocks have traded between 1.0x and 3.0x NAV and between 1.0x and 2.0x more recently with a median of 1.25-1.50 times, with unhedged, growth-oriented producers occupying the upper end of the range. We use a 0.75x NAV multiple for BTG vs. mid-tier gold producer peers' target multiples at 0.75x-1.25x given higher execution risk.

Downside risks to our BTG valuation are: 1) political risk from Mali 2) mine plan estimates in excess of BTG reserves, 3) lack of commodity diversification, 4) mine plans that are based on outstanding permits or approvals, 5) unfavorable changes in currencies, 6) unforeseen increases in in put costs such as the price of oil and labor, 7) the possibility it could lose its social license to operate at any of its mines or projects 8) potential cuts to the dividend or reduced capital return and 9) issues with the ongoing construction and ramp-up of the Goose project. Upside risks are a higher gold price, the possibility for BTG to be acquired and unexpected exploration success. 10) Our gold price forecast is also a risk to our BTG valuation/forecasts.

Barrick Mining (B)

Our price objective (PO) for Barrick Gold is $58.00 per share and is based on the stock trading at 1.25x our estimated net asset value (NAV). Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with unhedged, growth-oriented producers with assets located in relatively geopolitically stable regions occupying the upper end of the range. Preventing us from assigning a higher target P/NAV multiple is Barrick's stable gold output. Downside risks to our price objective are: commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, political or legal challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects. Upside risks are stronger than expected commodity prices, better than expected production and cost control.

Cameco Corporation (YCCO / CCJ)

Our C$190 ($133) PO is based on 1.0x our NAV and 35.0x 2026E & 34.5x 2027E EV/EBITDA (all 3 equally weighted). We use a CADUSD FX rate of 1.42. The 35.0x 2026E EV/EBITDA is above its long-term average of c.15x, but below the long-term peak of c.40.0x that occurred when nuclear energy growth was last very strong. The 34.5x for 2027E is a slight discount to 35.0x used for 2026E given time-related risk. The 1.0x P/NAV is above the longer-term average of c.0.9x but below peak of 1.35x. We think 1.0x is justified given Cameco's world-class tier one assets in favorable jurisdictions (Canada) & potential exploration upside partially offset by voluntary idling of one of those tier-one assets (but is in the process of restarting).

Downside risks: 1) slower-than-expected global energy demand growth, 2) continued push-out of a Japanese nuclear fleet restart, 3) any worsening in sentiment toward nuclear or more favorable sentiment toward alternative power fuel sources, and 4) any production problems at Cameco's only operating mine, Cigar Lake.

Upside risks: 1) additional potential mine disruptions that may further improve supply-demand dynamics, 2) better pace of reactor development in key future demand countries (China, Japan, and India), 3) more stringent carbon emissions restrictions in key countries, encouraging nuclear power as an environmentally friendly base line energy source, 4) a material rise in natural gas prices making nuclear power generation competitive in the US.

Centerra Gold (YCG / CGAU)

Our price objective for Centerra Gold is C$22.75 per share and US$16.00 per share, based on the stock trading at 0.75x our estimated net asset value (NAV). Historically North American precious metal stocks have traded between 1 and 3 times NAV, with a median of 1.50 times over the past nine years (and 2.00 times longer-term), with unhedged, growth-oriented producers occupying the upper end of the range.

Downside risks to our price objective for Centerra Gold are commodity price weakness, delays in the development of its growth projects and the potential for additional operating issues at Öksüt. Upside risks to our price objective are gold and molybdenum prices rising, unexpected exploration success at any of the assets, and a favorable renegotiation of its gold/copper stream on Mt. Milligan.

Centrus Energy Corp. (LEU)

Our price objective (PO) of $167 per share is derived based on 2.5x our estimated net asset value (NAV). The 2.5x 2026E NAV target multiple is a premium to the nuclear fuel supply peers to account for barriers to entry, its emerging next generation nuclear fuel growth business, strong enrichment market fundamentals to which its peers have minimal exposure, and U.S. government support, that is now being realized via the early 2026, $900m DoE funding award.

Downside risks are:1) lower than forecast enrichment pricing, 2) loss of access to enriched uranium product, 3) unexpected restrictive regulatory changes, possibly including sanctions, 4) shipping disruptions, and 5) technical disruptions.

Upside risks are: 1) higher than forecast enrichment pricing, 2) unexpected government financial and/or regulatory support, 3) a potential acquisition, and 4) faster than expected deployments of small and advanced modular reactors.

Cleveland-Cliffs (CLF)

Our $14.00 PO is based on 7.0x 2026E EV/EBITDA, 6.5x 2027E EV/EBITDA and 1.0x net asset value, with each value equally weighted. The 7.0x 2026E EV/EBITDA target multiple is higher than its historical trading average of 7.4x and is more in line with that of its key steel peers given an emerging recovery in US auto production and CLF's substantial automotive exposure relative to public peers.

Downside risks: 1) new capacities pressuring steel prices & margins, 2) obsolescence of its capacity relative to newer supply forcing closures, 3) higher-than-expected capex or interrupted operations to address older mills or environmental liabilities, 4) union representation may keep labor costs high relative to peers, 5) underfunded pension/health care position & high leverage, 6) risks to auto sector demand, including switching to aluminum & alternative materials, 7) higher imports and/or, 8) changes to trade policy.

Upside risks: 1) better steel demand than we anticipate, 2) steel price outperformance, especially if driven by raw materials as CLF is largely vertically integrated, 3) Further reduction in underfunded pension & OPEB liability, 4) resumption of the dividend, 5) better auto negotiating position for longer, and 6) sustained/higher barriers to imported steel. 6) More earnings accretion from agreement with major global steel producer.

CMC (CMC)

Our $78 per share price objective for Commercial Metals (CMC) is based on a blended 6.5x FY26E EV/EBITDA, 6.0x FY27E EV/EBITDA and 1.0x our NAV. The 6.5x 2026E EV/EBITDA target multiple is higher than its historical trading average of 6.1x to reflect the market rerating. However, the 6.5x multiple is below the target multiples used for other mini-mill peers (7.5x-8.0x) given its less diverse products / end-markets. This is partly offset by CMC's leverage to infrastructure (which is set to see strong growth from a significant increase in federal spending) and reshoring demand.

Upside risks to our price objective are: 1) better-than-expected construction / reshoring demand, 2) higher steel pricing, 3) better-than-expected pricing power in global long products that support pricing and limit imports, 4) additional trade relief, 5) cash deployment for organic or inorganic growth.

Downside risks to our price objective are: 1) sluggish demand due to delay in federal funding and/or tightened credit availability for private projects, 2) lower steel pricing, 3) execution risk related to Tensar and new micro-mills, 4) any rollback of trade relief, particularly related to Section 232, 5) threat of lower priced imports and 6) potential medium term oversupply from various new entrants in the domestic rebar market.

Eldorado Gold (EGO / YELD)

Our price objective of $51.00 (C$72.00) is based on the stock trading at 1.25x times its estimated net asset value (NAV). Historically, North American precious metal stocks have traded between 1 and 3 times NAV over the last five years, with a median of 1.50 times (and 2.00 times longer-term) and with unhedged, growth-oriented producers occupying the upper end of the range. We value EGO below the lower end of the valuation range due to higher political risk for operating in Greece and Türkiye.

Downside risks to our price objective for Eldorado Gold are commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects.

Upside risks are a higher-than-expected gold price, a more hospitable regulatory environment in the jurisdictions where the company operates (in particular, Greece), more favorable foreign exchange rates than now projected, and better-than-expected operational results.

First Quantum Minerals (YFM / FQVLF)

Our C$44.00 and US$31.00 price objectives are based on a 9.5x 2026E EV/EBITDA, 9.0x 2027E EV/EBITDA, and 1.00x our NAV estimate, reflecting the long-term value of the suspended Cobre Panamá mine (we assume mine restarts in late-2027E) and the steps taken to strengthen the balance sheet.

Upside risks are stronger than forecast copper prices, early resumption of FM's development projects (Cobre Panamá), favorable local currency changes that lower USD costs, and the potential for First Quantum to become an acquisition target.

Downside risks to our PO are a weaker-than-expected global economy that could impede metal demand growth expectations, affecting our commodity price forecasts. In addition, sovereign risks in Zambia (i.e., challenging geopolitical environment, developing infrastructure) and Panamá (mining a newer industry), ramp-up issues at Cobre Panamá, stronger than forecast local currencies that increase USD costs, labor action, and weather could also impact our FM valuation and PO.

Franco-Nevada (YFNV / FNV)

Our price objective for Franco-Nevada is C$398 (US$280) per share, based on the stock trading at 2.65x our estimated net asset value (NAV) on a cash-adjusted basis and a USD/CAD FX rate of 1.42x. Historically, North American precious metal streaming stocks have traded between 1.50 and 3.50 times NAV, with growth oriented streaming companies at the top end. Based on its strong balance sheet and low-cost asset base, we believe Franco-Nevada deserves a premium multiple. Franco-Nevada also benefits from an experienced management team.

Upside risks to our PO are substantially higher commodity prices, higher-than-expected output at the royalty assets, and/or higher reserves.

Downside risks are commodity price weakness and unforeseen operating problems at the mines on which its royalties are based.

Freeport-McMoRan (FCX)

Our $87.00 per share price objective blends 11x 2026E, 10.5x 2027E EV/EBITDA and 1.0x our net asset value (NAV). The EV/EBITDA target multiples are above the 8.0x historical average for copper producers covered by BofA Global Research to reflect the impact from temporary lower volumes at Grasberg and our bullish view for Copper. Our P/NAV multiple of 1.0x is in line with most of the copper producers covered by BofA Global Research but is arguably conservative given several potentially value-enhancing growth options that we do not currently model. These include a new mill at El Abra, a mill expansion at Bagdad and low-grade leaching.

Downside risks to our price objective are 1) global economic weakness, 2) Operating disruptions, 3) execution risk at its cost-cutting or expansion programs, 4) stricter or unfavorable regulatory or environmental regulations, particularly at its Indonesian operations, 5) other factors pressuring prices of the commodities it produces and 6) unfavorable currency moves.

Upside risks are 1) better-than-expected copper and gold prices, 2) a more accommodating operating environment in Indonesia and 3) further cost-cutting progress.

Hudbay Minerals (YHBM / HBM)

Our C$45.50 (US$32.00) per share price objective for Hudbay Minerals (YHBM/HBM) is based on a 8.5x 2026E EV/EBITDA multiple, 8.0x 2027E EV/EBITDA multiple and 1.0x our net asset (NAV) estimate, weighted equally to each. Since 2005, the global copper producers have traded in an EV/EBITDA range from 2.0x to 13.0x with HBM trading at a discount. For HBM, we use a below peer target multiple given a less diverse asset base than average (just two copper mines and one gold mine) partly offset by stronger average jurisdictional exposure.

Upside risks are stronger-than-forecast copper prices, favorable local currency changes that lower USD costs, the receipt of all permits for Rosemont with no legal challenges, a sooner than expected start of mining of the Pampacancha satellite deposit and the potential for HBM to be targeted for acquisition.

A downside risk to our PO is a weaker-than-expected global economy that could impede metal demand growth expectations, affecting our commodity price forecasts. Other downside risks are a delay in attaining surface access rights at Pampacancha, the political and regulatory climate in the jurisdictions in which HBM operates (Canada, Peru and the USA), stronger than forecast local currencies that increase USD costs, increases in general operating and development costs, labor action, weather and the inability to attain the needed permits to develop Rosemont, M&A risk.

IAMGOLD Corp. (IAG / YIMG)

Our price objective for IAMGOLD is US$22.00/C$31.50 per share, and is based on the stock trading at 1.35x times our estimated net asset value (NAV) and a 1.42 CADUSD exchange rate. Historically, North American precious metal stocks have traded between 1.50 and 3 times NAV, with a median of 2.00 times over the long-term, and with unhedged, growth-oriented producers with solid financial positions and low relative costs and located in stable mining jurisdiction occupying the upper end of the range. We ascribe a moderate P/NAV multiple to IAMGOLD to reflect our forecast for higher than average political risk in Burkina Faso, execution risks at the Cote Gold project, and higher cash costs and debt vs. peers. As the Cote Gold project in Canada ramp-ups, this should drive strong volume growth, lower costs and political risk, and ultimately drive deleveraging.

Upside risks: Gold price could surprise to the upside vs. our expectation. Potential positive developments in terms of exploration results and project execution.

Downside risks: Gold price could surprise to the downside vs. our expectations. Risks on project capital cost over-runs / schedule disappointment. We also consider the risk for unfavorable political developments, particularly in higher perceived political risk jurisdictions such as Burkina Faso.

Ivanhoe Mines (YIVN / IVPAF)

Our C$13.50 (US$14.50) price objective is based on 1.10x our net asset (NAV) estimate. The 1.10x price to net asset value (P/NAV) target multiple is at a modest premium to the current trading multiples of global copper producers to reflect its superior production growth, low relative unit costs, a strong balance sheet and solid copper optionality with the 100%-owned Western Foreland property.

Upside risks to our PO are stronger-than-forecast copper prices, faster-than-expected ramp-up of IVN's development projects (in particular, Kamoa-Kakula), the discovery of new mineral resources that become mining projects (Western Foreland has this potential), favorable local currency changes that lower USD costs, participation in the M&A backdrop

Downside risks to our PO are a weaker-than-expected global economy, jurisdictional risks in the Democratic Republic of Congo (DRC) and South Africa (i.e., tax regime changes, mining policy shifts, poorly defined legal frameworks, difficulty in obtaining social license, etc.), ramp-up issues at Kamoa-Kakula, input cost inflation, stronger-than-forecast local currencies that increase USD costs, labor action, and weather.

Kinross Gold (KGC)

Our price objective for Kinross Gold is $24.75 per share, and is based on the stock trading at 1.25 times our net asset value (NAV) estimate, reflecting production growth that is forecast to be slightly lower than the senior/mid-tier average. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with companies with declining production at the lower end of the range.

Risks to our price objective for Kinross Gold are commodity price weakness, the inability to secure financing for expansion or development projects, unforeseen operating problems, political or legal challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects or current mine expansions. On the upside, risks are stronger than expected commodity prices and an operating turnaround that exceeds our expectations in terms of timing and magnitude, and exploration success.

Lundin Mining Corp (YLUN / XLPRF)

Our C$45.00, US$33.00 and SEK304 per share price objectives for Lundin Mining are based on 11.5x and 11.0x EV/EBITDA multiples applied to our 2026E EBITDA and 2027E EBITDA and 1.0x applied to our net asset value (NAV) estimate. We apply a USDCAD FX rate of 1.42 and a USDSEK FX rate of 9.14. Since 2005, the global base metal producers have traded in an EV/EBITDA range from 2.0x to 13.0x, with Lundin trading at a discount to the average due to it being a smaller company. However, we see potential for a re-rating as LUN executes on its growth strategy including its transformative Vicuña project.

Downside risks to our PO are worse-than-expected economic performance that could impede our metal demand expectations, impacting our commodity price forecasts. In addition, development and/or permitting delays, stronger than forecast local currencies that increase USD costs, worker strike action, several possible technical missteps and weather could also impact our Lundin valuation and PO.

Upside risks are higher-than-forecast commodity prices as well as weakening local currencies, substantial exploration success leading to longer mine lives and/or higher margin ounces, the potential for LUN to become an acquisition target.

Lundin Mining Corp (LUNMF)

Our C$45.00, US$32.00 and SEK304 per share price objectives for Lundin Mining are based on 11.5x and 11.0x EV/EBITDA multiples applied to our 2026E EBITDA and 2027E EBITDA and 1.0x applied to our net asset value (NAV) estimate. We apply a USDCAD FX rate of 1.42 and a USDSEK FX rate of 9.14. Since 2005, the global base metal producers have traded in an EV/EBITDA range from 2.0x to 13.0x, with Lundin trading at a discount to the average due to it being a smaller company. However, we see potential for a re-rating as LUN executes on its growth strategy including its transformative Vicuña project.

Downside risks to our PO are worse-than-expected economic performance that could impede our metal demand expectations, impacting our commodity price forecasts. In addition, development and/or permitting delays, stronger than forecast local currencies that increase USD costs, worker strike action, several possible technical missteps and weather could also impact our Lundin valuation and PO.

Upside risks are higher-than-forecast commodity prices as well as weakening local currencies, substantial exploration success leading to longer mine lives and/or higher margin ounces, the potential for LUN to become an acquisition target.

MP Materials (MP)

Our $85 PO assumes a 25x multiple on our 2029E EBITDA, discounted back to today's money using MP's weighted average cost of capital of around 7.0%. The 25x multiple assigned is below its own historical average (of 34.2x) but in-line with its 2020-2024 average of 25.2x. The higher multiple vs peers recognizes 1) reduced execution risk, 2) expansion potential, 3) rising strategic premium, 4) and explicit Department of Defense (DoD) support. As the only integrated rare earth and magnetics producer in the Western Hemisphere, we continue to see MP as a unique investment vehicle for exposure. We are medium to long-term bullish neodymium-praseodymium (NdPr), MP's key upstream product.

Upside risks: 1) stronger EV and wind generation demand, 2) scarcity of other rare earths investment vehicles, 3) likely first-mover advantage in the vertical integration opportunity, 4) barriers to entry (Stage I and II), 5) potential for additional U.S. government financial support, 6) possible more collaborations with major EV makers, 7) the possibility that MP could be acquired, and 8) higher than expected rare earths pricing.

Downside risks: 1) execution of Stage II and III and cost containment, 2) higher China supply quotas, 3) new entrants, particularly outside of China., 4) increased competition in Stage III, 5) limited clarity on Stage III profitability, 6) rare earth magnet substitutes, and 7) slower EV adoption hurting demand.

Newmont Corporation (NEM / XNCRF)

Our price objective for Newmont is $139 (A$200) per share, and is based on the stock trading at 1.75x times our estimated net asset value (NAV). We assume a USDAUD exchange rate of 1.47. Our NAV is based on a 5% discount rate and a long-term gold price of $3,500/oz. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with a median of 1.50 times over the past three years (2.00 times longer-term), and with unhedged, growth-oriented producers with solid balance sheets occupying the upper end of the range. In the great gold rally of 2011, NEM's multiple peaked at 2.50x.

Upside risks to our price objective are stronger-than-forecast commodity prices, better than expected success at reducing costs and positive regulatory, permitting or operating developments. Downside risks to our price objective for Newmont are the inability to secure financing for expansion or development projects, unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects.

Nexa Resources (NEXA)

We have removed the investment opinion on the company's stock. Investors should no longer rely on our previous opinion or price objective.

Nucor (NUE)

Our price objective of $300 per share is based on 9.0x 2026E EV/EBITDA, 8.5x 2027E EV/EBITDA and 1.0x NAV, with each value equally weighted. The 9x 2026E EV/EBITDA target multiple is above its historical average of 7.3x to reflect potential upside from higher spot pricing and its highly variable cost structure, diversified product mix, strong volume growth potential (from multiple projects underway) and investment grade balance sheet with a disciplined capital return policy (minimum of 40% of net income).

Downside risks to our price objective are: 1) lower steel price and higher scrap costs squeezing margins, 2) weaker than expected demand especially in construction markets, 3) project start-up delays and cost overruns, and 4) M&A's which could be dilutive in the near-term.

Upside risks to our price objective are: 1) higher than expected steel prices, 2) lower than expected input costs, 3) lower import volumes, 4) more favorable trade policies, and 5) a stronger than expected economy.

Pan American Silver (PAAS)

Our price objective for Pan American Silver is $57.00, and is based on the stock trading at 1.75x our estimated net asset value (NAV) on a net investments-adjusted basis (i.e. the 1.75x multiple is applied to the asset value and then the value of the equity investments is added to that with an effective 1.0x multiple applied). Our NAV is based on a 5% discount rate for all assets, except Escobal for which we use 7.5%. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with silver producers generally trading at a discount to gold producers.

Upside risks to our price objective are higher than expected commodity price forecasts, a change in the regulatory/permitting environment in the Chubut province of Argentina where Pan American's dormant Navidad project is located, operating results that exceed expectations and lower than expected capital costs.

Downside risks to our price objective are unforeseen operating issues, realized commodity prices that are below our forecast, regulatory issues (including tax, environmental and permitting) that cause financial results to differ from our forecast, and higher than expected capital costs.

Reliance, Inc. (RS)

Our $405 per share price objective for Reliance Inc. (RS) is based on 11.5x 2026E EV/EBITDA, 11.0x 2027E EV/EBITDA and 1.0x NAV, with each value equally weighted. The 11.5x 2026E EV/EBITDA target multiple is above its historical trading average of 8.3x to account for improved business model with higher long-term sustainable gross profit margin of 29-31% versus 25-27% in 2015/16 and potential growth through M&A.

Downside risks to our price objective are: 1) a sharp correction in prices (carbon steel, stainless and aluminum), 2) weaker than expected macro, leading to lower metal demand, 3) higher imports and 4) execution risk related its acquisition strategy.

Upside risks to our price objective are: 1) aggressive buybacks or dividend increases, 2) higher metal prices, 3) more attractive consolidation opportunities and 4) a better demand environment.

Royal Gold (RGLD)

Our price objective for Royal Gold is $222 per share, which is based on the stock trading at 2.00x our adjusted net asset value (NAV), valuing net cash cost 1:1. Our net asset value (NAV) is based on a 5% discount rate. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with unhedged, growth-oriented producers occupying the upper end of the range. Given Royal Gold's status as a royalty company as opposed to an operator, our target valuation multiple reflects its good cash flow-generating ability.

Upside risks to our PO are substantially higher commodity prices, higher-than-expected output at the royalty assets, and/or higher reserves at the royalty assets. Downside risks are a weaker gold price, problems at the operations, and no exploration success.

SSR Mining Inc. (SSRM / YSSRM)

Our price objective for SSR Mining is $40.00 (C$56.00) per share, and is based on 1.25x our adjusted estimated net asset value (NAV). Our NAV is based on a 5% discount rate (consistent with the vast majority of gold operations within our North American precious metals coverage) and long-term gold price forecast of $3,500 per ounce. Historically, North American precious metal stocks have traded between 1 and 3x NAV, with a median of 1.00x over the past three years (2.00x longer-term). Our target multiple reflects the enormous uncertainty surrounding the outcome of the heap leach pad slide at the Copler mine balanced by stronger North American operations.

Upside risks to our price objective are stronger-than-forecast commodity prices, better-than-expected success at reducing costs and positive regulatory, permitting or operating developments.

Downside risks to our price objective for SSR are the inability to secure financing for expansion or development projects, unforeseen operating problems, political, legal or permitting challenges in the regions in which the company operates, rising capital and operating costs and delays in the development of its growth projects.

Steel Dynamics (STLD)

Our $270 per share price objective for Steel Dynamics (STLD) is based on 8.5x 2026E EV/EBITDA, 8.0x 2027E EV/EBITDA and 1.0x NAV, with each value equally weighted. Our 8.5x target EV/EBITDA multiple is higher than its historical trading average of 6.6x to reflect potential upside from higher spot pricing and its industry leading utilization rate, highly variable cost structure, leading value-add product portfolio, investment grade balance sheet and unique exposure to higher margin downstream business via its aluminum rolling mill. At spot pricing, the implied valuation multiple is closer to 8.0x, still high historically.

Upside risks to our price objective are: better than expected macro leading to stronger steel pricing and spreads than we forecast, continued Fabrication tailwind, aggressive shareholder returns, more protective trade policy, and lower imports.

Downside risks to our price objective are: lower steel and metal spreads, project delays, lower than expected demand, higher imports, and excess industry supply.

Teck Resources (YTECK / TECK)

We have removed the investment opinion on the company's stock. Investors should no longer rely on our previous opinion or price objective.

Triple Flag Precious Metals Corp. (YTFPM / TFPM)

Our C$53.00 ($37.00) per share PO for TFPM is based on a target valuation multiple of 2.00x our estimated NAV. The multiple is a slight discount to the senior royalty & streaming peers giving consideration to TFPM's smaller market cap and liquidity, and less diversification by geography, commodity and operator, partly offset by above average margins and attributable GEO production growth. The multiple is at the high end of the range for the gold producer peers given the attractive relative investment characteristics of the royalty & streaming business model (precious metals exposure with insulation from opex and capex inflation and upside from production growth and exploration success.

Our NAV estimate is based on a 5% real discount rate and long-term gold and silver prices of $3,500/oz and $42.00/oz (starting in 2031E).

Downside risks to our PO are: 1) a lack of input the operation of portfolio assets, 2) competition from a growing royalty and streaming sector 3) precious metal price volatility, 4) asset investments in non-investment grade emerging markets, 5) concentrated ownership structure, 6) ramp up delays at development projects.

Upside risks are: 1) higher than expected gold and silver prices, 2) future exploration discoveries and unexpected expansions at mines in the portfolio, 3) a potential acquisition of TFPM.

Wheaton Precious Metals (WPM)

Our price objective for Wheaton is $169.00 per share, and is based on the stock trading at 3.25x times our estimated net asset value (NAV). Our NAV per share is based on a 5 percent discount rate. Historically, North American precious metal stocks have traded between 1 and 3 times NAV, with a median of 2.00 times longer-term (1.50 times in the last three years), and with royalty/streaming companies occupying the upper end of the range.

Risks to our price objective for Wheaton are continued commodity price weakness, unforeseen operating problems at the mines on which its silver streams are based, financing challenges, political or legal challenges in the regions in which the mines operate, and delays in the development of projects for which the company silver streams.

Professional subscribers can read the full metals note here at our new Marketdesk.ai portal. 

Tyler Durden Mon, 10/12/2026 - 13:35

Majority Of Voters Concerned About Socialists Running For Office; New Poll Finds

Majority Of Voters Concerned About Socialists Running For Office; New Poll Finds

Authored by Sarah Roderick-Fitch via The Center Square,

A majority of American voters are concerned with socialist candidates running and possibly winning political office, according to a new poll.

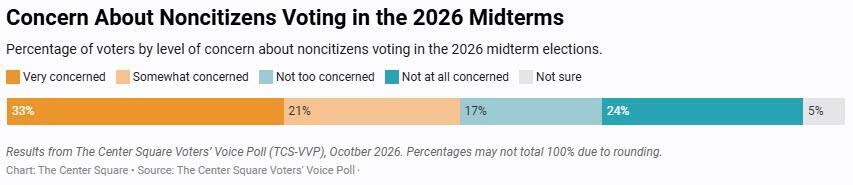
The Center Square Voters' Voice poll found that 55% of American voters are concerned about Democratic Socialist candidates running for and winning elected office in the U.S., while 37% aren't concerned.

A slew of candidates running as democratic socialists appears to be raising alarms with a majority of American voters.

Of the 55% who are concerned, 35% are very concerned, while 20% say they are "somewhat concerned."

Of those not concerned, only 17% say they are not too concerned, while 20% say they are not at all concerned.

The poll comes as several Democratic Socialist candidates have risen in popularity across the country. The Democratic Socialists of America are touting 67 wins across the country, with 93 running. However, the group includes 62 DSA candidates who have lost.

The latest poll comes on the heels of an August poll by The Center Square's Voters' Voice Poll, which found 63% of Americans are concerned with the growth of socialism or communism in American politics, while 29% were not concerned.

Of the 63% concerned in August, 36% said they were very concerned, and 27% are somewhat concerned.

The Center Square's Voters Voice Poll, conducted by Noble Predictive Insights, surveyed 2,527 registered voters from Oct. 5-7 via an opt-in online panel and text-to-web cell phone messages. The sample included 1,136 Republicans, 1,171 Democrats, and 220 True Independents, who did not lean toward either major party when asked.

Heading into the midterm elections in November, Republicans and several Democratic voices have warned against democratic socialists rising to power across the country, with the backing of U.S. Sen. Bernie Sanders, I-Vt., and U.S. Rep. Alexandria Ocasio-Cortez, D-N.Y.

It's not only Republicans warning against socialism. U.S. Sen. John Fetterman, D-Penn., has been outspoken on several self-proclaimed democratic socialists gaining popularity within the Democratic party.

Earlier in the month, Fetterman cited a CBS News poll that found nearly 60% of Democrats have a positive view of socialism.

"The Democratic Party is becoming the party of socialism. 58% view socialism positively. 50% view capitalism negatively. I'm a proud free market capitalist. This is lunacy," the senator wrote on social media.

Fetterman isn't the only Democrat calling out the party's growing socialist arm; veteran Democratic strategist James Carville has called on the Democratic Socialists of America to drop the word "Democratic" from their name to distance the party from leftist policies.

In contrast to the CBS poll, The Center Square's Voters' Voice Poll found that 49% of Democratic voters are concerned with the rise in socialism or communism, while 40% aren't concerned at all.

The poll comes as several democratic socialist candidates across the country, including in New York, Colorado, Michigan, California, and even Florida, have received the nod from Democratic voters to advance to the November elections.

Tyler Durden Mon, 10/12/2026 - 13:15

AI Strikes Again - Getty Images Heads For Chapter 11 Bankruptcy

AI Strikes Again - Getty Images Heads For Chapter 11 Bankruptcy

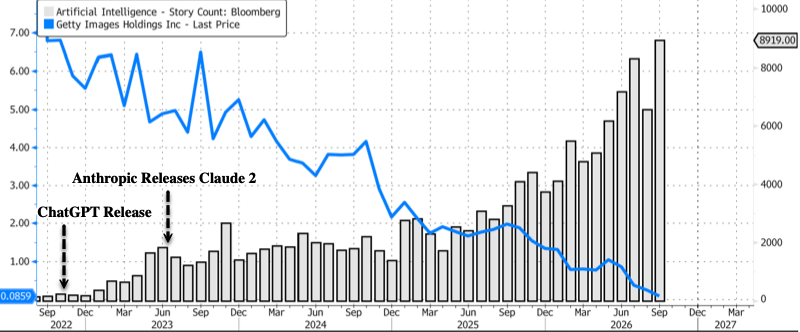
Getty Images' photo, video, and illustration licensing business to news outlets, advertisers, and businesses faces a quick death from AI.

Chatbots let users create visual content at a fraction of the cost of licensing, and Getty shares have collapsed since ChatGPT's launch in late 2022, coinciding with a surge in AI news coverage and the growing adoption of chatbots for professional and personal use.

And now, Bloomberg reports that Getty plans to file for a prepackaged Chapter 11 restructuring in the coming weeks after securing support from major creditors and commitments for up to $533 million in new equity.

Getty family members and Koch Equity Development affiliates will provide the equity investment as part of the restructuring support agreement. The company expects to complete the restructuring by year-end.

The outlet noted that holders representing 83.5% of Getty's unsecured bonds have agreed to retire $270 million of outstanding senior unsecured notes, reducing the company's debt burden.

Investors holding about 89% of its secured bonds and term loans, along with all revolving credit facility lenders, have agreed to lower interest obligations and extend secured debt maturities.

The new deal will let Getty keep afloat, backed by $143 million in financing... but for how long?

Beyond Getty, Shutterstock has likely felt the pain from AI-generated images and video, which could replace stock-content purchases and pressure licensing prices. Adobe Stock also faces substitution risk. 

* * * If you can afford it, get one of these. It will run a Starlink Mini + power-hungry Laptop for ~4 hours. Connectivity anywhere. 

Tyler Durden Mon, 10/12/2026 - 13:00

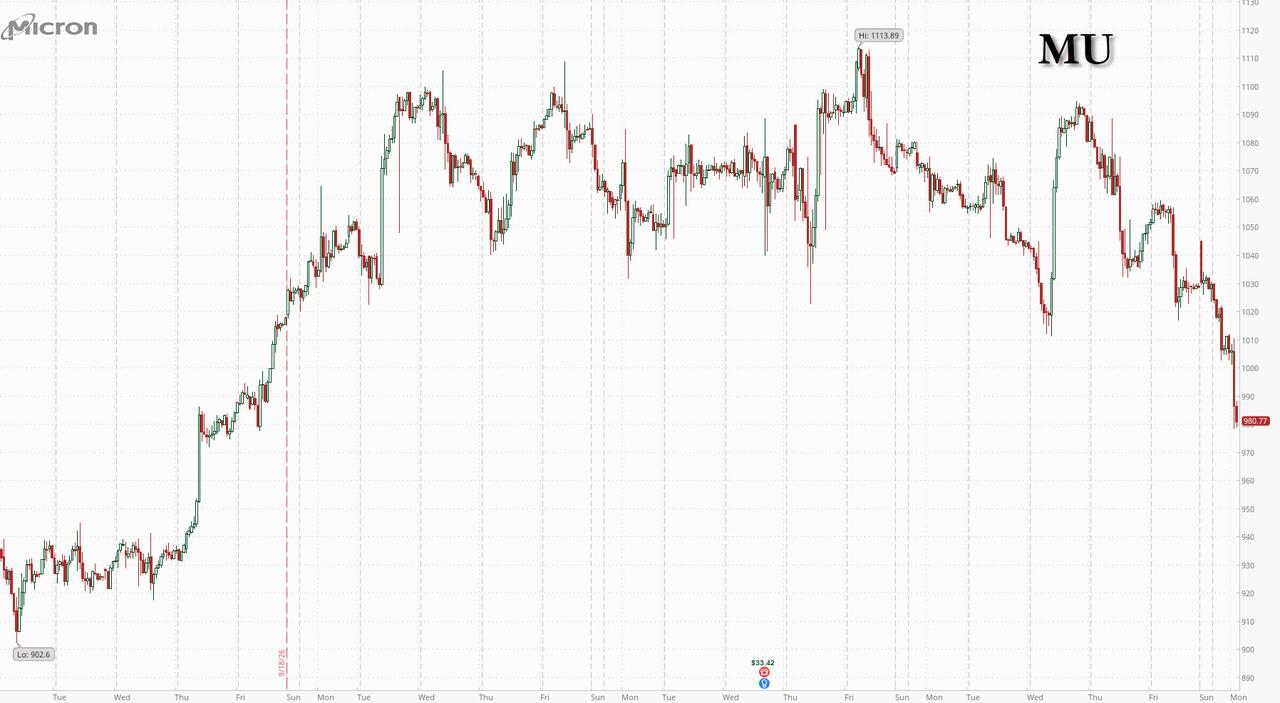
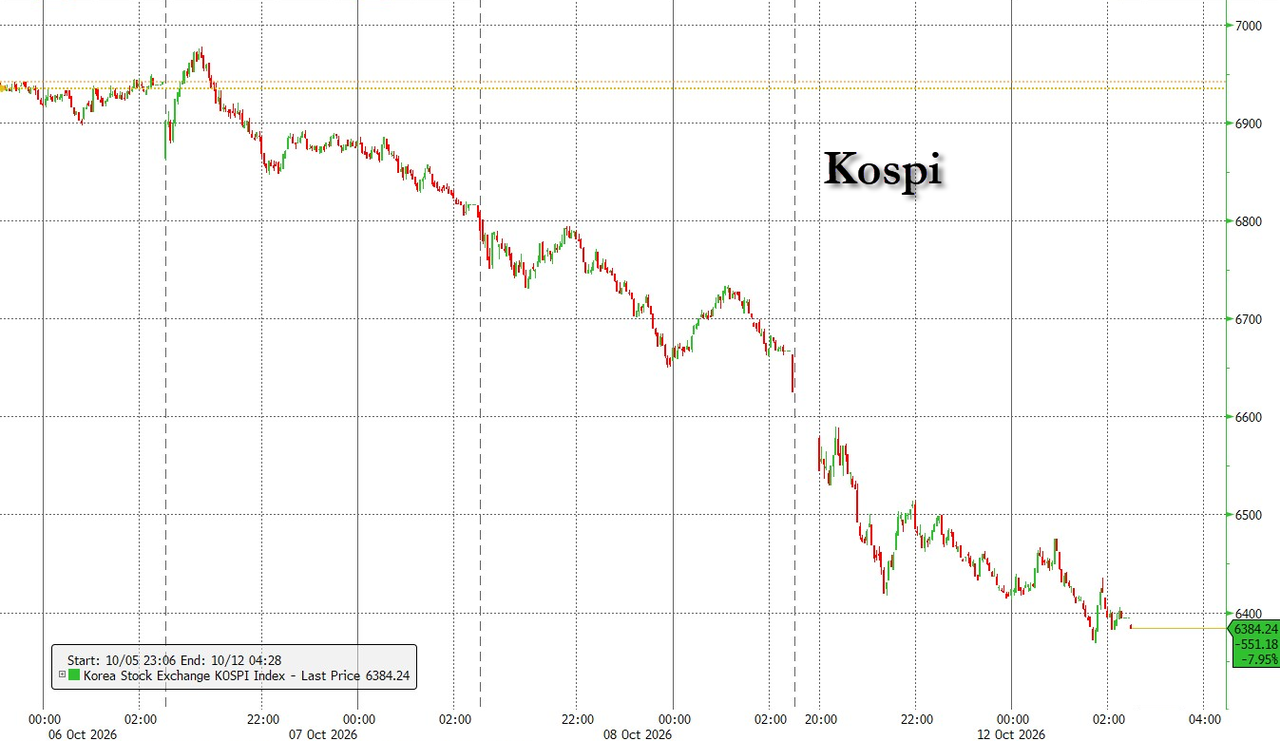
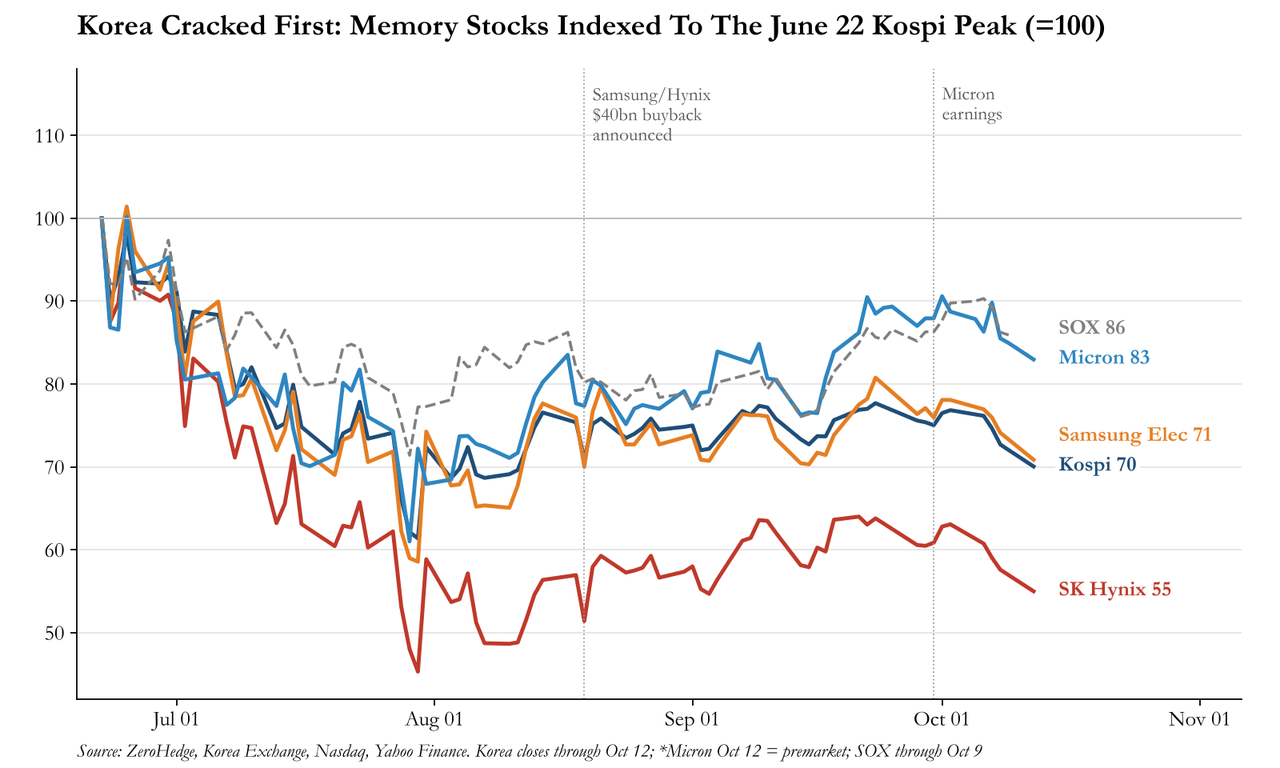
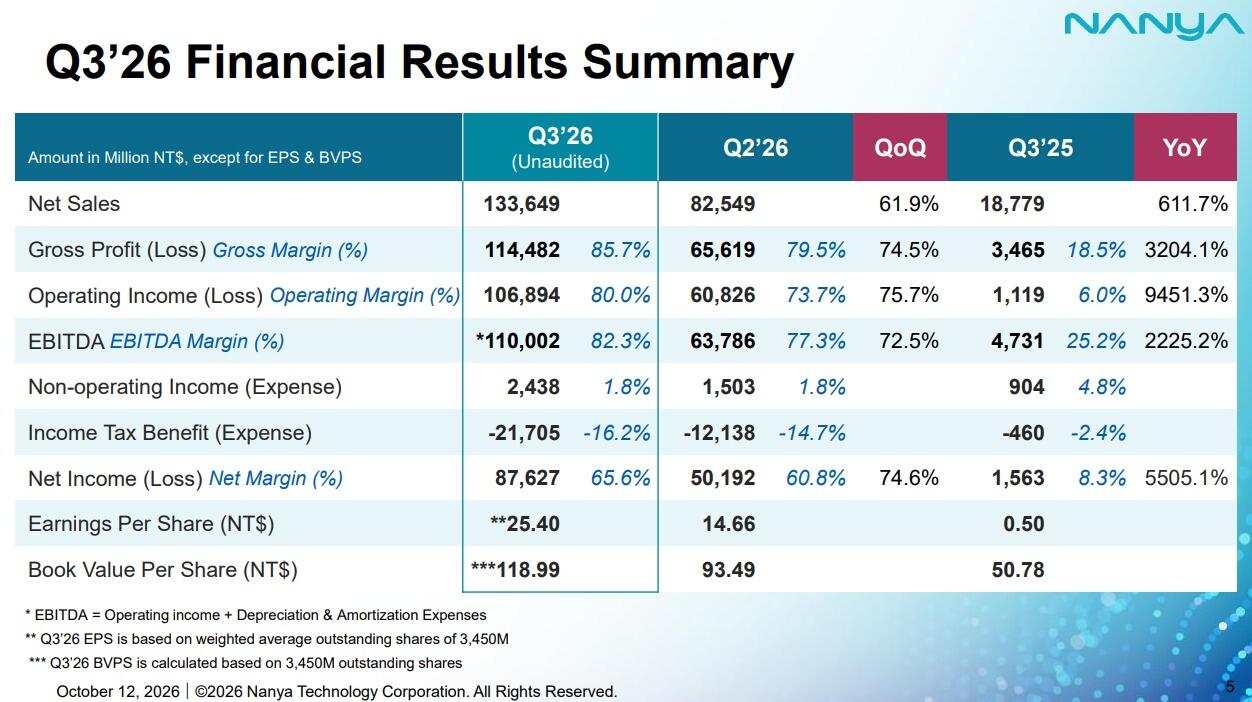
"Memory Remains The Epicenter": Micron Tumbles Below $1,000 As Kospi Catches-Down And CXMT Shrinks The DRAM Cell

"Memory Remains The Epicenter": Micron Tumbles Below $1,000 As Kospi Catches-Down And CXMT Shrinks The DRAM Cell

Micron just delivered the kind of quarter that would have sent the stock into orbit in June. Instead, it is tumbling and about to lose the $1,000 handle.

Barely two weeks after Micron (MU) guided to $60-$63 billion in fiscal Q1 revenue, crushing the $56.8 billion consensus, and a week after Goldman calculated that Micron alone would deliver 19% of the entire S&P 500's Q3 earnings growth...

Source

... the memory giant has slumped below $1000, down almost 5%, the lowest price in over 3 weeks. 

Sandisk was down even more, tumbling 7%, and according to Goldman's TMT desk, both names are now lower in 6 of their last 7 sessions. Micron is about to enter a bear market, down almost 20% from its June record close, and a stock where sentiment was "11/10" back in June is now trading like nobody wants to be the last one holding it.

The reason for the latest selloff is coming from the other side of the Pacific, where three things collided overnight: i) a Korean market reopening after Friday's Hangul Day holiday and catching up to two days of US chip selling, ii) the end of the record Samsung/SK Hynix buyback that we warned last week was the only thing propping up the Kospi, and iii) a weekend announcement out of Shanghai that China's DRAM champion CXMT has made "key progress" on the next-generation memory cell that Samsung and Hynix are still years away from mass producing.

Goldman's EMEA head of one-delta trading Rich Privorotsky summed it up in four words this morning (available to pro subs):

Pretty ugly in Korea. Kospi -3-4%, Samsung/Hynix -4%, Taiwan broadly flat. Memory remains the epicenter. CXMT announced a new 4F² DRAM architecture over the weekend. China already has ~10% DRAM revenue share and is aggressively adding capacity. Adds to concerns around peak memory earnings despite extraordinary near term fundamentals. Also perhaps a bit of travel and arrive post Samsung numbers which failed to massively surpass expectations.

In other words, the fundamentals have never been better, and that is precisely the problem: they are all priced in.

Let's take a closer look at the latest Korean carnage, the CXMT news, and why the bull case (record margins, sold-out 2027) is now running into the one thing markets fear more than a shortage: the end of one.

Korea Catches Down

The Kospi tumbled 3.65% to 6,384.2 in what Goldman's Seoul trading desk called "a one-way move from the open," closing right on top of its 200-day moving average at 6,376 (available to pro subs). The tech-heavy Kosdaq did even worse, sliding 4.8%. Here's how the desk described the session:

KOSPI fell sharply in a one-way move from the open and closed just above its 200DMA support (@ 6376), as escalating geopolitical tensions and US memory weakness weighed on the broader market. Foreigners extended their five day net-selling streak (focus-selling in Tech -$1.3bn), while retail investors net bought with bids concentrated in Tech (+$1.2bn, size of net-buying on a decreasing trend).

The semi index KRXSEMI dropped 5.2%, while SK Hynix (000660 KS) and Samsung (005930 KS) each lost about 4.5% as they played catch-down to "SOX's two-day weakness on reopening." That two-day weakness came on Thursday, when Goldman's US desk saw "a heavy wave of selling in Semis / AI complex around OpenAI revenue headlines that continued through Friday despite the clarification update." Foreigners dumped $782 million of Hynix and $415 million of Samsung, while retail (+$710 million in Samsung) once again caught the falling knives.

Here is how the past week looked in real time, as we posted this morning:

That is an 8% drop in the three sessions since Samsung's buyback program ran out, and the Kospi is now 30% below its June 22 record close. Korea's market, the poster child of the AI trade in the first half, has become the worst performer in the second, and as Bloomberg noted in a piece we ran last night, turnover has collapsed 70% from its late-May peak while foreigners have pulled $131 billion from Korean stocks this year, the most of any major Asian market.

The Only Buyer Has Left The Building (As Predicted)

Regular readers will recall that on Sept 3 we warned that only record buybacks were preventing a Kospi crash, and last Wednesday that the W55 trillion ($40 billion) Samsung/Hynix repurchase program, the largest in Korean history, was ending weeks ahead of schedule. As we put it at the time:

Samsung's program effectively ended on Oct 6, and Hynix's has a handful of sessions left at most at which point the biggest buyer in Korea will be gone. The math since then is not pretty: the Kospi has dropped in every session since, and today's flow data show exactly the hole we flagged. With the corporate bid gone, the only remaining buyer is Korean retail, and even there Goldman notes the "size of net-buying [is] on a decreasing trend." Bloomberg's numbers paint the same picture: margin loans are down from a June peak of 38.6 trillion won to about 33 trillion, and investor deposits have fallen to roughly 100 trillion won from nearly 140 trillion.

Translation: Korea's retail army already got carted out once in July, and it is in no hurry to volunteer for round two.

The ZH chart below shows just how far Korea has decoupled from the US memory complex since the June top. SK Hynix is down 45% from its June 22 close; the Kospi and Samsung are down roughly 30%. Micron and the SOX, which held up on the back of blowout US earnings, are only now starting to catch the Korean cold.

Four Square F: Why CXMT's Weekend News Matters

And then there's China.

On Saturday, ChangXin Memory Technologies (CXMT) president Cao Kanyu told an industry event in Shanghai that the company has made "key progress" on a new DRAM cell structure and plans to roll out a server-memory product based on it by the end of 2026, according to the South China Morning Post.

The technology is the so-called "4F²" (four square F) design, where each memory cell occupies an area of 4F², with F being the minimum line width of the chip. Today's mainstream commercial DRAM uses a 6F² cell. CXMT says the core of its design is a proprietary Vertical Surrounding Gate (VSG) transistor that uses a vertical gate to curb current leakage while shrinking the cell footprint.

Some quick math: shrinking each cell from 6F² to 4F² cuts its area by a third, which means up to ~50% more cells on the same die at the same line width, before any of the real-world overhead that eats into the gain. For a company that is effectively locked out of EUV, a density gain that doesn't require a leading-edge lithography node is precisely the workaround one would expect.

Why does this matter for Samsung and Hynix? Because they are chasing the same thing on a much slower timeline. SK Hynix only unveiled its 4F² roadmap in 2025, and Samsung, according to Korea's The Elec, targets mass production of sub-10nm DRAM based on the design by 2028. If CXMT actually ships a 4F² server product by year-end (a big if, since "key progress" is the kind of phrase that tends to precede more key progress), Beijing's memory champion will have leapfrogged the Korean duo on cell architecture by about two years.

Of course, the CXMT threat is hardly news to our readers. Back in July, we reported that CXMT was testing a production line for next-gen bonded DRAM, closing the gap with Korea "far faster than expected", and three weeks later, as the stock exploded over 450% in its IPO debut, Goldman warned that the "memory industry has a new problem." When Goldman initiated coverage of CXMT a month later, the bank laid out the scale of that problem:

And for those still counting on export controls to keep China in check, there was this, from early September:

Then, three weeks ago, Acer's CEO Jason Chen went further, telling reporters that "the supply shortage problem has already completely disappeared" as Chinese capacity keeps coming onto the market, and accusing the Big 3 memory makers of using public statements to signal each other that prices will stay high (since antitrust law prevents them from just saying so to each other directly). He expects memory prices to peak around the middle of 2027. Acer, HP and Asus are already putting CXMT chips in their PCs.

Put it all together and you get Privorotsky's "peak memory earnings" concern: nobody is arguing with the next two quarters; the worry is the price of DRAM in 2028, when Chinese supply is projected to be half of Hynix's and new Korean fabs come online at the same time.

"Extraordinary Near Term Fundamentals"... Again

The irony, of course, is that the numbers keep getting better. Case in point: Taiwan's Nanya Technology, which reported Q3 results this morning that Goldman's Taipei desk called "another astonishing quarter":

  • Revenue of NT$133.6 billion, up 62% QoQ and 612% YoY
  • Gross margin of 85.7% (+6.2pp QoQ) and operating margin of 80%
  • Blended ASPs up more than 60% QoQ, with over half of that driven by contract resets on expiring 2025 long-term agreements

And the outlook remains just as tight: management expects double-digit contract price gains and gross margins above 80% to remain "achievable" in 2027, with no bit shipment growth at all in early 2027 due to near-zero channel inventory, with volumes inflecting only after new fab output starts in Q4 2027. Goldman's desk, however, noted the uncomfortable truth in its personal take: there is "not much excitement recently to drive further re-ratings."

That is the memory market in one sentence: record earnings, shrinking multiples. Or as Pictet's Jon Withaar told Bloomberg, the memory names "have become value names, cheap at current earnings," and "retail and fast money hedge funds do not chase value." Growth is what they chase, and they are increasingly worried that it peaks right around when CXMT's 4F² chips hit the market.

Hedge funds certainly aren't waiting around to find out. Goldman's Prime Book shows that last week US Info Tech went from the most net bought sector in 4 of the past 5 weeks to the most net sold, at the fastest pace in seven weeks, with Tech Hardware, Storage & Peripherals and Semis the most sold subsectors. Meanwhile, the Samsung earnings that were supposed to restart the trade (a nearly ninefold surge in operating profit) produced a selloff instead, which is all you need to know about where expectations are.

What To Watch

Goldman's Korea research team flagged six things it will be listening for on Samsung's Oct 29 earnings call, and the first one tells you exactly what the market is worried about: "whether the company calls for a tighter memory supply in 2028 similar to Micron." The others include new LTAs with customers, the HBM4 ramp (and the impact of HBM "despeccing"), updated capex plans, and shareholder returns (good luck with that last one: the market just got a live demonstration of what happens when the buyback ends). SK Hynix reports the last week of October.

Before then, this week brings TSMC on Thursday, ASML on Wednesday (which is reportedly raising spare-part prices for its Korean customers by 10%, with Samsung and Hynix accepting the hike starting January 2027; nice work if you can get it), and SEMICON West, all of which will give the chip complex plenty of opportunities to either restore faith or provide more fodder for the peak-cycle crowd.

Bottom Line

Privorotsky was careful to call this a concern about "peak memory earnings despite extraordinary near term fundamentals," and Nanya's results prove the near term is indeed extraordinary. But markets discount the future, and the future now includes a Chinese competitor that briefly became China's most valuable company in August, ASML tools stockpiled for three years, a 4F² product on the roadmap for this December, and the stated ambition of supplying half as much DRAM as SK Hynix by 2028.

The bulls will say the selloff is overdone and memory is "cheap at current earnings." We think the more likely outcome is that Korea, which led the memory trade on the way up and cracked first on the way down, is once again the leading indicator, just as we suggested back in June when we wrote that Micron won't be where you'll first hear the memory trade is over. Korea is now 30% off its highs and Hynix 45%; Micron is down 17% and about to enter a bear market.

Because nothing says "peak cycle" quite like 86% gross margins.

Tyler Durden Mon, 10/12/2026 - 11:05

Starbucks Kills Chipotle Takeover Rumor: "We're Not Buying" The Burrito Chain

Starbucks Kills Chipotle Takeover Rumor: "We're Not Buying" The Burrito Chain

Hopes of buying a Starbucks Iced Brown Sugar Oatmilk Shaken Espresso and a Chipotle Chicken Burrito Bowl under one roof through a possible merger of the two quick-service restaurant chains were squashed Monday morning.

"As a matter of policy, we don't comment on rumors and speculation, but we want to be clear we are not buying Chipotle," a Starbucks spokesperson told Barron's. The company said it remains focused on executing its "Back to Starbucks" turnaround strategy.

The rumor mill around the two QSRs' potential marriage began last Thursday, after a Financial Times report said Starbucks had explored acquiring Chipotle.

Analysts have expressed skepticism about the potential deal, which would be one of the biggest takeovers in the restaurant industry.

William Blair restaurant analyst Sharon Zackfia provided her first take on last week's news:

The Financial Times is reporting that Starbucks is exploring a potential takeover of Chipotle (CMG $32.88; Outperform), the restaurant concept that Starbucks CEO Brian Niccol helmed for 6 years prior to moving to Starbucks just over 2 years ago. Clearly, Niccol knows the Chipotle business extraordinarily well, which at a bare minimum is likely reassuring to Chipotle investors since the stock has declined more than 35% since the news of Niccol's departure. But what would a combined company look like, and what possible synergies and efficiencies exist?

There are no obvious revenue synergies between the two brands, although perhaps opportunities exist in shared loyalty ecosystems, cross-brand product placements (i.e., Starbucks Refreshers with your Barbacoa Burrito Bowl), or expanding Chipotle's licensed international business more quickly through Starbucks' existing relationships. Traditional supply chain efficiencies are likely limited given very different supply chains, with Starbucks sourcing green coffee and pre-made food products, while Chipotle works directly with farms for raw ingredients. G&A savings would likely center in corporate G&A and technology, which we very roundly estimate could be in the $300 million range.

With an enterprise value of more than $40 billion, Chipotle would represent the largest-ever restaurant acquisition. We suspect a fair proxy of a likely acquisition price would be closer to $50 billion, similar to the 20% premiums that Inspire Brands paid to purchase Dunkin' and that JAB paid to purchase Panera Bread. As of the end of June, Starbucks had about $9.4 billion in net debt and a debt ratio of just over 2 times. An incremental debt slug of nearly $49 billion to buy Chipotle is tough math, and would be dilutive to a combined company 2027 EPS at any interest rate over 4% (assuming no cost savings/revenue synergies). It would also balloon the combined company's leverage ratio to about 6 times, which would be high in the publicly traded restaurant landscape. An all-shares takeover would be slightly accretive to EPS, with our back-of-the-envelope math suggesting accretion of about 3%. One wild card could be a potential sale of Starbucks Japan, which could help fund a Chipotle acquisition.

Following this morning's Barron's report, Chipotle shares fell 3% in early US trading, while Starbucks gained about 1%.

Starbucks' denial removes any such dream of a near-term tie-up that would've resulted in buying an espresso and burrito under one roof. 

Tyler Durden Mon, 10/12/2026 - 10:50

Zelensky Says He'll Hold Elections If Putin Agrees To 60-Day Ceasefire

Zelensky Says He'll Hold Elections If Putin Agrees To 60-Day Ceasefire

Authored by Dave DeCamp via AntiWar.com

Ukrainian President Volodymyr Zelensky said on Sunday that he would hold elections in Ukraine if Russian President Vladimir Putin agreed to a 60-day ceasefire, comments that came after President Trump said Ukraine needed a new president to reach a deal with Russia.

Zelensky’s term expired in May 2024, but he has remained in power because no elections have been held, and he has continued to reject the growing calls within Ukraine to hold a vote.

Zelensky during his nightly address on October 11, 2026 (Office of Ukrainian President)

Trump said on Saturday that he suggested Ukraine "get a new leader who can make a deal because he could have made many deals and for some reason he never does."

Responding to Trump, Zelensky said in an interview with ABC News that Trump should tell Putin to agree to a 60-day ceasefire.

"So please tell Putin, give us two months, 60 days off. Total ceasefire, 60 days, and we will organize elections," he said. "Of course, we will be ready for any choice of our people, exactly Ukrainian people."

Zelensky and other Ukrainian officials have justified not holding an election by pointing to Ukraine’s constitution, which prohibits elections during martial law, first declared after Russia’s invasion and extended since, though Zelensky suggested back in 2023 that he could hold one if the US and other Western countries paid for it.

Zelensky also offered criticism of a deal Trump announced that would involve the US importing Russian diesel, calling it a "birthday gift" to Putin that would allow Russia to "kill us, kill our children."

Trump also lashed out at Zelensky on Saturday over Ukraine’s attacks on Russian oil refineries, as he’s attempting to shift blame for the global energy crisis from the US war with Iran to the Russia-Ukraine war.

Moscow responds by once again saying it is not looking for a temporary truce, but wants a lasting political settlement to the conflict:

However, it’s been widely reported that Ukraine's attacks on Russian energy infrastructure are supported by US intelligence.

Tyler Durden Mon, 10/12/2026 - 10:20

"Full-On Truman Show": Former State Dept. Official Exposes USAID's Censorship Machine In Brazil

"Full-On Truman Show": Former State Dept. Official Exposes USAID's Censorship Machine In Brazil

Former State Department official Mike Benz laid out USAID's sweeping involvement in Brazil's political and institutional landscape, detailing a network of American funding that reached media organizations, universities, activist groups and organizations involved with the country's election system.

Benz, who serves as executive director of the Foundation for Freedom Online, broke down the extent of USAID's footprint during an appearance on "The Benny Show" with host Benny Johnson.

"What's happening in Brazil was a full-on Truman show. You had the media funded by USAID. You had the universities funded by USAID. You had the staffers of the Supreme Court and the TSE (Superior Electoral Court), the election court, USAID. You had all the constitutional law advocates funded by USAID. You had the LGBT activists funded by USAID," Benz explained.

"It's full spectrum. If you were to walk down a city block in Sao Paulo or, I don't know, Brasilia, you would have a 360 vision of institutions funded and puppeteered by USAID without ever knowing it," the former State Department official added. "In fact, USAID, knowing what they were doing, and I need to be careful about what I can and can't say here, let's just say, would anyone be surprised, for example, if USAID was going around and telling its grantees in Brazil to remove the USAID logo so that it doesn't get out that grantee's connection to USAID?"

Benz said USAID's influence could continue even after its funding disappeared because institutional and legal changes remained in place.

"They knew what they were doing. They knew how sensitive it was. Would you be surprised, for example, if USAID, which basically set up the censorship state in Brazil, and this is actually something, let me quickly pivot to say, it is true that this is the first Brazilian election since the 2020 municipal elections in Brazil that does not have USAID money slushing around Lula and his allies, but is still an election that is in many ways under the thumb of the ghost of USAID," he said. "There is something I call kind of the clockmaker's dilemma, which is USAID, even when you remove it, the institutional and legal changes that a country goes through can live on even if you cut USAID funding down to zero."

Benz then zeroed in on two of Brazil's most powerful institutions, the Supreme Federal Court (STF) and Superior Electoral Court (TSE): "For example, in Brazil, you have this apparatus through the STF and TSE, the Supreme Court and the basically election court that determines all things around elections, and basically after Bolsonaro won in 2018, the TSE court with Alexandre de Moraes, the famous Voldemort judge, they declared disinformation a threat to free and fair elections, not just disinformation during an election season, but disinformation any time, misinformation, disinformation any time about anything because it could pollute people's, I don't know, sense of what's true or false in the information ecosystem, and so it could have an impact on an election three years away if this false information is allowed to circulate online."

Benz also went into detail about USAID's connections to Brazil's election and judicial establishment.

"That was set up by USAID, USAID flooded the zone, USAID had contact at every level with the TSE court, with the Alexandre de Moraes court," he said. "I testified to the Brazilian Senate Relations Committee and put pictures from USAID's website of Alexandre de Moraes being trained by CEPS (Competitive Economy Program), the USAID grantee, by NED (National Endowment for Democracy), the USAID grantee has gotten $3 billion from USAID and was created by the Central Intelligence Agency."

Benz's remarks come just days after Brazil's conservatives delivered a powerful showing at the ballot box. Flávio Bolsonaro finished first in the opening round of the presidential election, taking 47.03% of the vote to left-wing President Luiz Inácio Lula da Silva's 45.16%, setting up an October 25 runoff.

Bolsonaro's Liberal Party emerged as the largest party in both houses of Congress, winning 121 seats in the Chamber of Deputies and expanding its Senate delegation from 15 to 28 seats.

* * *

https://store.zerohedge.com/products/wagyu-tomahawk-steak?utm_source=zerohedge&utm_medium=banner&utm_campaign=beef_order_tonight_20261011&utm_content=03-wagyu-tomahawk-order-tonight-v2


Tyler Durden Mon, 10/12/2026 - 10:15

Cyberattack Disrupts Refrigeration Systems At Hundreds Of French Supermarkets

Cyberattack Disrupts Refrigeration Systems At Hundreds Of French Supermarkets

A cyberattack targeting supermarket refrigeration equipment has caused widespread disruption across France, leaving hundreds of stores facing spoiled inventory, financial losses and potentially costly equipment damage, according to France 24.

Roughly 150 to 200 Intermarché locations and nearly 100 Coopérative U stores were caught up in the incident, which allowed attackers to interfere with temperature controls remotely. E. Leclerc, France's largest supermarket operator, was also reportedly affected, while Carrefour Market and Monoprix have been identified as possible additional targets, according to AFP and BFM TV.

Rather than stealing customer information or demanding ransom, the attackers apparently focused on destroying physical inventory. Refrigeration systems were reportedly forced into abnormal operating conditions, rendering substantial quantities of perishable merchandise unsellable. Some equipment was allegedly pushed into continuous defrost cycles, with temperatures reaching 122°F. Two stores in Alsace alone reportedly sustained approximately €270,000 in losses, according to La Dépêche du Midi.

Coopérative U chief Dominique Schelcher described the incident as unlike anything the industry had previously experienced. Beyond the immediate destruction of food, retailers now face questions about insurance coverage, operational recovery and the security of increasingly interconnected store equipment.

The report says that French authorities have launched a criminal investigation, with prosecutors examining the scale of the losses and reports that some refrigeration units caught fire.

The episode illustrates how cyberattacks are increasingly capable of inflicting damage well beyond computer networks. By exploiting connected industrial equipment, attackers can disrupt everyday commerce, destroy valuable goods and potentially threaten critical infrastructure without ever physically entering a facility.

The incident comes as France intensifies efforts to defend essential infrastructure against foreign interference, including potential Russian hybrid operations. However, no public evidence has established who was responsible for this particular attack, according to AFP.

Tyler Durden Mon, 10/12/2026 - 10:05

The War On Columbus Was Never Really About Columbus

The War On Columbus Was Never Really About Columbus

Authored by Jarrett Stepman via The Daily Signal,

Christopher Columbus is having a revival thanks to President Donald Trump and the good sense of the American people.

This is a remarkable change from just a few years ago, when it seemed likely that the country was ready to purge Columbus, the Founding Fathers, and pretty much any notable figure from our past.

It was so over for Columbus Day that even some Republicans were looking to sweep it into the dustbin of history.

But we've come a long way since 2020.

More Americans now understand that the attack on Columbus is an attack on the idea of America itself, and that caving to the Left's demands to strike his holiday from the calendar as his statues came tumbling down was tantamount to civilizational suicide.

Trump's reelection ushered in a major vibe shift that was already under way. Columbus Day came back stronger than ever as part of the larger counterrevolution against the madness of the Great Awokening.

In March, a Columbus statue - a replica of one tossed by protesters into Baltimore Harbor during the post-George Floyd riots, no less - was placed in front of the White House.

And on Wednesday, Trump issued a proclamation announcing that Columbus Day would be celebrated on Oct. 12.

"Today, we reaffirm that Christopher Columbus is a legend whose vision, fortitude, and perseverance unleashed a dynamic of history that led to the creation of the greatest, freest, and most just Nation in history," Trump's proclamation read. "We are forever indebted to his courageous voyage, and we will never allow his legacy to be erased by radical extremists."

That is an accurate and appropriate tribute for a man for whom we owe so much, even if Columbus never saw, considered, or had any notion of the future United States. We certainly are indebted to his incredible voyage that changed the tide of history.

But that last line from Trump about never allowing his legacy to be erased is key here, because the battle over Columbus is so important for our own day, even apart from the particulars of his life and momentous voyage.

Leftist writers like Howard Zinn and the generations of acolytes he spawned begin from the premise that the West, Christendom, is inherently broken and perhaps even the source of evil and "inequality" in our world.

The far-Left has long condemned Columbus and those who followed him into the New World as genocidal monsters, virtually boogeymen who were not only flawed as all men are but as uniquely terrible.

This is in many ways a perversion of history. The same folks who lament and often overstate the violence and malice of European arrivals in the Americas hardly seem to care about the violence and terror that preceded them. That's irrelevant and even annoyingly inconvenient to their narrative.

What they want is a future in which Western societies - especially the people of the United States - fundamentally reject their own past, culture, traditions, and certainly their religion. That is the only way to ensure that a new, secular ideology - these days some variant of identitarian socialism or Marxism - can rush to fill the vacuum of what brings life meaning and order.

By this method of indoctrination and reprogramming, traditional Western rational skepticism was transformed into a malignant, irrational self-loathing.

The gloved, flipping off of a Columbus statue by the now-mayor of New York, Zohran Mamdani, is the perfect expression of this kind of deranged, knee-jerk anti-Americanism so common among the spoiled children of the global elites and the campus activist class that follows them. Columbus set set into the unknown with three small ships and a compass to guide him. These twerps cast vulgarities behind soft gloves and think they are edgy.

Columbus was once a figure whom all Americans, immigrant and native-born, could love and admire, just like our flag and our Constitution.

If it was up to the Left, he would remain only as a symbol for all who live in America, immigrant and native-born, to loathe and condemn.

Again, don't be fooled, this battle isn't really about a 15th-century Italian navigator, it's about us, the here and the now, the nation that ultimately emerged from splinters of his tiny ships.

The Left thought they had finally won this battle.

It wasn't just a few radical extremists on the fringes of college campuses who were trying to obliterate Columbus Day while putting Indigenous Peoples' Day atop the figurative empty pedestal where he once stood. It was "mainstream" institutions and political leaders carrying out the purge too.

President Joe Biden - or perhaps a facsimile wielding an autopen - essentially declared the far-Left's triumph in 2021. He put out a "commemoration" for Columbus Day that spent more time apologizing for the famed explorer and lamenting the "shameful" history of America than saying anything nice about him.

An Italian and some Spaniards got on a boat and did something. That was about the only positive thing he could say amid the condemnations.

This is what the Left had been building up to for a long time. This was the final blow. It was over for Columbus Day. The wheels of history had turned. The old explorer and the America he once represented were finally gone and buried for good.

We know now that the battle wasn't over. There are still many, many Americans who aren't so eager to jettison our past and darken our future. The battle for our future is ongoing. Columbus stands again in front of the White House, and hopefully in more communities across the United States.

This Columbus Day we should remember how far we had fallen; how close we came to the final chapter of our incredible history. Let us boldly go forward, like Columbus, with pride in our past and confidence in our future.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden Mon, 10/12/2026 - 09:50

Feds Raid Ilhan Omar's DC Home As Immigration Fraud Investigation Heats Up

Feds Raid Ilhan Omar's DC Home As Immigration Fraud Investigation Heats Up

Federal agents raided the Washington, D.C., home of Rep. Ilhan Omar (D-MN) early Monday morning as part of an ongoing criminal investigation into the Somali-born congresswoman's immigration paperwork, according to Fox News.

The pre-dawn operation began around 6 a.m., with multiple agents wearing Homeland Security Investigations (HSI) jackets observed outside the residence. Two sources close to the investigation told Fox News that authorities are examining immigration documents completed by Omar's late father when she was a child.

The Department of Justice confirmed that federal agents had executed a search warrant.

"Today in the Washington, D.C., area, Homeland Security Investigations executed a judicially authorized search warrant secured by the Department of Justice. This enforcement action is part of an ongoing federal investigation," a DOJ spokesperson told Fox News Digital.

The DOJ has not publicly disclosed the specific allegations underlying the warrant.

The raid marks a significant escalation in a federal investigation that White House border czar Tom Homan publicly acknowledged last month - and revives longstanding questions surrounding Omar's immigration and marital history.

Homan Confirmed Criminal Investigation In September

As Jonathan Turley previously noted, Homan confirmed that federal authorities were examining allegations involving the Minnesota Democrat.

The controversy centers in part on longstanding claims that Omar married her brother, Ahmed Nur Said Elmi, to facilitate an immigration benefit - allegations Omar has repeatedly denied and which have not been established as fact.

Turley examined whether the allegations could support a fraud case or instead amounted to potentially defamatory accusations, and noted that the statute of limitations could complicate any prosecution involving events dating back many years.

In September, Omar told Fox News that DHS had not contacted her regarding the investigation.

"No, they have not," she said when asked whether federal authorities had reached out. At the time, Homan declined to disclose whether investigators possessed evidence of immigration or naturalization fraud.

Less than a month later, federal agents have now searched her Washington residence under a warrant obtained by the Justice Department.

Years Of Controversy Over Omar's Immigration History

Omar, who was born in Somalia and became a naturalized American citizen in 2000, has faced questions about her marital history since before her election to Congress in 2018. The controversy involves her 2009 legal marriage to Elmi, their subsequent separation, and her relationship with Ahmed Hirsi, with whom she had children before their legal marriage.

Critics have questioned the chronology of those relationships and alleged that Elmi was actually Omar's brother. Omar has consistently rejected the allegation as false and politically motivated. 

Monday's developments raise a separate question: whether investigators are examining discrepancies in the childhood immigration records, the longstanding marital allegations, or some combination of issues.

    OCTOBER ONLY.$10 OFFYOUR NEXT ORDER.$30 min. Ends Oct 31. One per customer.GET MY $10 OFF →Signs you up for ZeroHedge Store emails. Can't be combined. Every order helps support ZeroHedge. Tyler Durden Mon, 10/12/2026 - 09:35

Riyadh Airport Closure Extended As Saudi Arabia Projects 'Normalcy', Hosting World Petroleum Congress

Riyadh Airport Closure Extended As Saudi Arabia Projects 'Normalcy', Hosting World Petroleum Congress

Saudi Arabia’s King Khalid International Airport's closure has been significantly extended in an unprecedented move by aviation authorities following the two weekend ballistic missile attacks by Yemen's Houthis which left at least 13 people killed and over 300 injured. Prior strikes rocked the airport last week, and in all 15 have been killed in two weeks, including a Saudi Airlines pilot.

Saudi Arabia's civil aviation body Monday extended the suspension of operations, stating "The General Authority of Civil Aviation has announced the extension of the suspension of operations at King Khalid International Airport in Riyadh in order to complete the necessary procedures to verify the safety of the facilities and their operational readiness."

While it didn't give a date of planned resumption of airport operations, separately a NOTAM (Notice to Air Missions, formerly Notice to Airmen) indicated a likely closure through the entire week, through a least Saturday:

Aviation @FAANews NOTAM A3604/26, issued on October 12, declares the entire airport unavailable due to precautionary measures until October 17 at 21:00 UTC, equivalent to midnight in Saudi Arabia at the start of October 18. This follows an earlier NOTAM closing Aircraft Stand C1 from October 8 through October 15. The notices confirm an airport-wide operational restriction, although they do not specify the full extent of the damage or establish when normal operations will resume.

Saudi Energy Minister Prince Abdulaziz bin Salman has said that Houthi attacks on the kingdom's airports are serious and so his country's response must be "equally serious". The Saudis are still lobbying intensely behind the scenes for more direct military help from Western allies, especially the United States, which so far has been largely on the sidelines.

Saudi Ministry of Media handout/Reuters

The Houthis are not just turning up the security pressure on Saudi Arabia, but the economic pressure as well. On Monday CNBC writes, "Australia, New Zealand, the U.K., the U.S., France, Germany, Japan and others have warned against travel to the kingdom, which is hosting the World ⁠Petroleum Congress."

The Saudis are actually pressing ahead with the 25th WPC Energy Conference in Riyadh (going all this week), trying desperately to project a sense of normalcy. Where are the missile interceptors?

The Saudi energy minister, Abdulaziz bin Salman, told the conference that “fear has no place in the Saudi lexicon”, emphasising that the resilience of the kingdom’s energy system and the determination of its people to confront crises.

An urgent review is under way as to how Houthi missiles are repeatedly penetrating badly stretched Saudi air defences. Schoolchildren and some office workers were advised to work from home. The Houthis have also targeted the city of Khamis Mushait, and the King Fahd international airport in Dammam.

Oil prices have in the meantime climbed to near two-week highs. WTI is up 1.2% at $93.00 and Brent is at session highs, above $106 having traded in a $102.33-$106.17 range, as Iran insists Hormuz stays shut until all seven of its conditions are met and Trump mulls joining Saudi strikes on the Houthis. Below is a note from Deutsche Bank's Jim Reid:

The big geopolitical/energy story over the weekend is the continued complexity of the Middle East and Russia/Ukraine conflicts. Trump announced yesterday that Russia and Ukraine had agreed to an immediate "energy ceasefire", but overnight developments underline how fragile that claim is. Zelenskyy said Ukraine supports a ceasefire if Russia does too and is awaiting details from Washington, while Moscow had still not publicly confirmed it. Zelenskyy also said Russia subsequently struck a thermal power plant in Kharkiv and other Ukrainian energy infrastructure. So for now this looks more like an untested US proposal than a functioning ceasefire, particularly after a similar arrangement last month failed to endure.

The proposed ceasefire is closely linked to the extraordinary US pivot on Russian diesel. Ukrainian refinery strikes had forced Moscow to restrict fuel exports, tightening an already constrained products market. Trump's deal with Putin would allow around 13.5 million barrels of Russian diesel back into global markets this month via a temporary US sanctions waiver, potentially including the first US imports since March 2022. Zelenskyy has criticised the move, while Reuters reported that Washington threatened to cut intelligence sharing and weapons procurement support unless Kyiv halted refinery strikes. Russian barrels returning would be bearish for diesel cracks, but the overnight strikes make the ceasefire increasingly uncertain and highlight strains between Washington and Kyiv.

Meanwhile, Middle East energy risk has moved sharply in the other direction. Riyadh's King Khalid International Airport was hit again on Sunday after repeated attacks over the past week. Saudi Arabia said the latest strike killed one person and injured 11, after Saturday's attack killed 12 and wounded more than 300. The escalation comes as Saudi-backed Yemeni government forces counter recent Houthi gains near Bab el-Mandeb, the crucial Red Sea shipping chokepoint. Repeated strikes disrupting flights in Riyadh also underline how difficult the Houthi threat may be for Saudi Arabia to suppress.

That leaves a meaningful risk of wider regional escalation. Saudi Arabia has intensified air strikes in Yemen, while Trump said the US "may" join strikes against the Houthis after an American was among those killed on Saturday. Overnight, Iran denied directing the Houthis and its foreign minister urged diplomacy with Saudi Arabia, but there is little sign yet of de-escalation. Washington has so far limited support to intelligence sharing while Riyadh seeks more direct US help and air-defence support. So even if a Russia/Ukraine ceasefire and Russian diesel waiver ease pressure on refined products, attacks on Riyadh and fighting around Bab el-Mandeb leave an upside tail risk for oil and shipping costs, alongside continuing Strait of Hormuz disruption.

As for the ability (or inability) of Saudi Arabia and its allies to protect the kingdom's airports and key Aramco oil facilities, this will remain a big open question. Various global airlines will continue their suspensions even after Riyadh and other airports try to open back up for business.

More Latest Developments

via Al Jazeera...

  • OPEC has lowered its oil demand growth forecast for this year to 400,000 barrels per day from 1.4 million at the start of the year, Haitham al-Ghais, Secretary General of the organisation says.
  • Saudi Aramco CEO Amin Nasser has said that until the Strait of Hormuz is fully reopened, pressure across the energy chain will only intensify.
  • Mohsen Rezai, Iran’s Supreme National Security Council secretary, says the Strait of Hormuz will not fully reopen until the US starts fulfiling its commitments and respecting Iranian demands.
  • Abolfazl Shekarchi, chief spokesman of the Iranian armed forces, has said the country will not allow the restoration of the US-Israeli regional order in West Asia, according to the IRIB broadcaster.
  • Three in four households in Yemen are unable to put food on the table as fighting intensifies in the country, the World Food Programme (WFP) warns.

via Newsquawk...

  • Deadly Houthi attacks on the Saudi capital’s main airport over the weekend raised the risk of a wider war that may draw in the US. More missiles and drones were intercepted overnight. BBG
  • The United States' response to Iran's seven conditions in a proposal to reopen the strategic Strait of Hormuz was "insufficient", Iran's security chief, Mohsen Rezaei, was quoted by state media on Sunday as saying. RTRS
  • Oil swung after US President Donald Trump said Kyiv and Moscow had agreed to an “energy ceasefire,” while in the Middle East, Saudi Arabia suffered its deadliest strikes since the Iran war began. BBG
  • Ukraine will continue to respond with long-range strikes against Russia unless Moscow agrees to an energy ceasefire that still hasn’t happened, President Volodymyr Zelenskyy said on Monday. BBG
  • Saudi Arabia is looking at ways to expand its oil pipeline capacity to destinations outside the Persian Gulf to 10 million barrels a day within two to three years, said Energy Minister Prince Abdulaziz bin Salman. BBG
  • US Senators reportedly demanded that President Trump reverse the Russian fuel imports deal, while Republican Senator Tillis warned that Trump’s Russian diesel deal may be illegal and put American lives at risk.
Tyler Durden Mon, 10/12/2026 - 09:20

'No Beardos, No Weirdos': Hegseth's 'State Of The Force' Speech Shows Recruiting Up, Generals Out

'No Beardos, No Weirdos': Hegseth's 'State Of The Force' Speech Shows Recruiting Up, Generals Out

Authored by Mike Fredenburg via The Epoch Times,

Secretary of War Hegseth's Sept. 30 State of the Force speech was refreshingly blunt, but it was also extremely informative. On the blunt side of things, Hegseth let the sergeants, chiefs, and junior officers know that the U.S. military was done with the woke mindset that had been destroying its fighting power:

"We are no longer the woke department or the weak department. Simple translation of that: no fatties, no trannies, no beardos, no weirdos, no wimps, no radicals. Just warriors. Just tough, ready, committed troops."

He framed last year's historic speech as a break from "the Defense Department of old" and "liberation day [from the DEI/woke mindset]," stating that the War Department's mission was "war fighting. Preparing to fight and preparing to win, unrelenting, unapologetic, and uncompromising in that single pursuit."

The Golden Rule

Encouragingly, just as he did a year ago in his Sept. 30, 2025, speech to generals and admirals, he stated civilian and military leadership were morally obligated to follow the Golden Rule:

"Do unto your unit as you would have done unto your own child's unit. Would you want them serving in a unit where standards were lowered to meet quotas? Or a unit where leaders were promoted for reasons other than merit, performance, or war fighting? The answer is not just no. The answer is hell no."

But along with his emphasis on rooting out the corrosive DEI/woke mindset that was seriously damaging America's fighting ability, Hegseth made a whole bunch of announcements and claims, including:

  • Recruiting is at multi-decade highs across the active force, Guard, and Reserve, and retention is at record levels, including among sailors on long deployments.
  • About 10 percent of generals and admirals have been removed, and general-officer billets cut by another 10 percent, for a reduction of about 20 percent.
  • Standards from around 1990 are back, including gender-neutral combat standards set at the previous male level, a combat field test, two fitness tests a year, height and weight standards, and daily physical training.
  • Diversity quotas, identity observances, and social-emotional leader evaluations have been dropped in favor of merit-based promotion and a performance test for colonels seeking general rank.
  • Military sexual assaults and suicides are down, and black and female recruiting are up even without quotas.
  • Commanders report more authority, capability, and backing than at any point in their careers.
  • Autonomous Warfare Command: A new four-star command dedicated to deploying autonomous and robotic systems across the joint force, slated for full launch by Oct. 1, 2027.
  • Project Meridian: A comprehensive 120-day future warfare study co-led by high-profile figures including Elon Musk, Palmer Luckey, and Newt Gingrich, with findings expected in late January 2027.
  • Fortress America: An initiative focusing on domestic base resilience by requiring major U.S. installations to self-generate power, bringing critical supply chains home, and hardening communications.
  • The Next Great American Base: A competitive program encouraging state governors to vie to host a new installation for 15,000 to 25,000 troops, marking the first new domestic military base in approximately 40 years.
  • America's Corps of Cadets, with distinguished-military-college status and commissioning priority for new programs at Louisiana State, Liberty, Tuskegee, Mississippi State, and Hillsdale.
  • An Office of Religious Affairs reporting directly to the Secretary, charged with protecting chaplain funding, chapel infrastructure, and religious support.
Recruiting and Retention Up Bigly

Many of the announcements warrant a whole article, if not a book, but the claims on recruiting and retention will be addressed here. Hegseth said the turnaround is "wildly popular both inside our ranks and with young Americans looking from the outside," and that retention is at record rates. As an implied rebuke to the exaggerated narrative of how bad things had been aboard the USS Abraham Lincoln, he noted the ship had an 84.4 percent reenlistment rate - among the highest of any aircraft carrier despite being at sea for more than 260 days. But beyond the one ship, Hegseth noted that when it comes to recruiting, every branch has been setting records since President Donald Trump won in November 2024: Army, Navy, Marine Corps, Air Force, Space Force, National Guard, Reserves, pilots, and special forces.

Indeed, all five active-duty services met or exceeded their fiscal 2025 recruiting goals, the strongest department-wide performance in about 15 years. The Army signed about 62,050 recruits, the Navy about 44,096, and the Air Force about 30,166, with both the Marine Corps and Space Force meeting their goals of 26,600 and 819, respectively. Through the first part of fiscal 2026, the services were still at or above their retention goals. The Air Force, for example, has been maintaining retention rates of between 85 and 90 percent.

Hegseth attributes the success in recruiting and retention to restored confidence in military leadership rather than bonuses: Americans enlist and stay, he argued, when they are led by "strong patriots, not by weak weirdos," and when promotion is merit-based. With recruiting and retention up, Hegseth made the case, a strong case, that Trump's support for restoring the warrior culture of the U.S. military reversed a downward slide and replaced it with an upward trend in competence, readiness, and warfighting. The new commands, bases, and pipelines matter, but for men and women that comprise the backbone of the military, what mattered more was the promise that he and Trump have their back, and that the people fighting beside them will be there because they meet the higher, revitalized standards, not a quota, and that the same rule will apply to the leaders giving the orders.

And that is the way it should be - period.

Views expressed in this article are opinions of the author and do not necessarily reflect the views of The Epoch Times or ZeroHedge.

Tyler Durden Mon, 10/12/2026 - 08:45

Pages