Zero Hedge

40 Percent Error Rate Found In Afghan Refugee Vetting Samples, Inspector General Finds

40 Percent Error Rate Found In Afghan Refugee Vetting Samples, Inspector General Finds

Authored by Naveen Athrappully via The Epoch Times,

A Department of Homeland Security (DHS) Office of Inspector General review has found errors in 40 percent of sampled asylum files for Afghan nationals who entered the United States under a Biden-era refugee program.

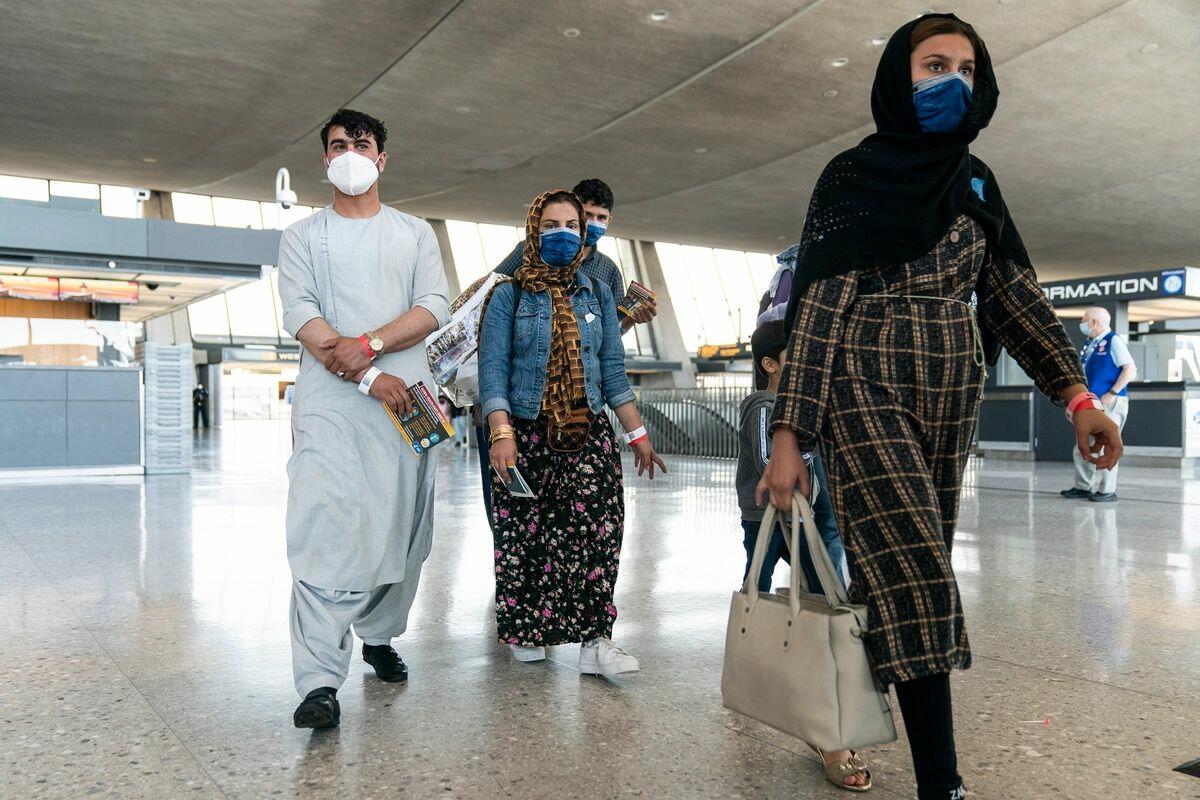
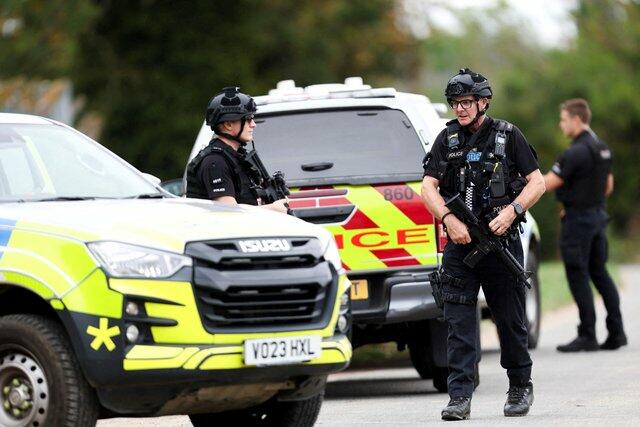
Afghan families walk to a bus that will take them to a refugee processing center at Dulles International Airport in Dulles, Va., on Aug. 24, 2021. Joshua Roberts/Getty Images

The report analyzed data from Operation Allies Welcome, which was initiated in the aftermath of the U.S. withdrawal from Afghanistan in 2021 and aimed to resettle roughly 97,000 Afghan nationals in the United States.

The DHS Office of Inspector General (OIG) analyzed a sample of 678 applications from 13,682 adjudicated applications filed by Afghan nationals resettled in the United States under the program.

The analysis identified a 40 percent error rate in adjudicating asylum files, including 303 missed aliases, 45 unresolved records, 23 missing security checks, and 115 other documentation issues, the OIG said in a Sept. 23 report.

"Most errors resulted from missed aliases or incomplete documentation, including two cases related to potential inadmissibility on terrorism-related grounds," the report states.

One of the terrorism-related errors involved an asylum officer failing to include an applicant's Terrorism-Related Inadmissibility Grounds worksheet in the case file. The second error involved officials failing to indicate whether they approved or disapproved an asylum officer's analysis of an applicant subject to Terrorism-Related Inadmissibility Grounds.

In a Sept. 29 statement, DHS said that Operation Allies Welcome led to many criminal immigrants being released into the United States, including those accused of sexual battery, kidnapping, drug possession, hit-and-runs, and lewd or lascivious acts with a minor.

For instance, in November 2025, DHS assisted the FBI in arresting an Afghan national who was charged with threatening to kill Americans. He was in the United States as part of Operation Allies Welcome.

In December 2025, a member of the ISIS terrorist group's Afghanistan affiliate who entered the United States under the operation was arrested. And in March this year, an Afghan national allowed into the country under the program who previously was convicted of indecent exposure to a minor was arrested.

In a June 2022 statement, U.S. Citizenship and Immigration Services (USCIS), under the Biden administration, had announced that Afghans who have supported and worked with the United States in Afghanistan and have undergone rigorous vetting could qualify for protection and other immigration benefits.

Then-DHS Secretary Alejandro N. Mayorkas said in the statement that this would "allow eligible individuals who pose no national security or public safety risk to receive asylum, refugee status, or other legal immigration status, demonstrating the United States' continued commitment to our Afghan allies and their family members."

Mullin: 'Dangerously Mismanaged'

DHS Secretary Markwayne Mullin said in the recent statement: "Our asylum system should be as strict as possible. If even one dangerous criminal or terrorist slips through and enters our country, it endangers countless American lives."

The Operation Allies Welcome program was "dangerously mismanaged" and disregarded "the thorough and well-established procedures of [the U.S.] asylum system," Mullin said.

OIG said in its report that it initiated the evaluation after receiving complaints that an agreement made by DHS would result in asylum adjudication issues. DHS made the settlement with certain plaintiffs in September 2023, agreeing to adjudicate 90 percent of asylum applications from the Operation Allies Welcome population within 150 days.

This went against standard procedures, in which applications from non-Operation Allies Welcome groups can take up to 180 days.

According to the OIG, USCIS employees complained that the shortened time frame could negatively affect proper review of applications. OIG included a response by USCIS to a redacted draft copy of the latest report.

USCIS Director Joseph B. Edlow said in a letter to DHS OIG that the draft report failed to consider that instances of missing aliases or improper security checks were taking place amid "broader, established, and robust screening, vetting, and security checks safeguards already in place that minimize the impact of these errors."

Edlow said that the agency's security check requirements include biometric and biographical checks of individuals against multiple law enforcement and watchlist databases. The agency also continues to enhance vetting requirements for people who have applied for asylum, according to the letter.

A December 2025 report by the Center for Immigration Studies said that more than 200,000 Afghan nationals had entered the United States under the previous administration's policies after the U.S. withdrawal from Afghanistan.

"Contrary to popular narratives, most Afghans admitted during and after the evacuation had nothing to do with the U.S. government or any of its contractors," senior researcher Nayla Rush said in the report. "They were not U.S. 'allies,' nor were they 'persecuted' individuals in need of refugee resettlement."

Tyler Durden Fri, 10/02/2026 - 10:20

Oil Dips As Europe Folds - G7 Agrees To 100-Million-Barrel Emergency Release

Oil Dips As Europe Folds - G7 Agrees To 100-Million-Barrel Emergency Release

Update (1000ET): French President Macron has just confirmed what we reported earlier, that the G7 has agreed to release as much as 100 million barrels of emergency oil and diesel stocks after pressure from the Trump administration to quell rising fuel prices.

The release, being coordinated by the International Energy Agency, will take place over the next four months, Emmanuel Macron, France’s president told journalists in a briefing on Friday. He is also the current chair of the G7 nations.

The G7 would like to trigger a drop in fuel prices, he said.

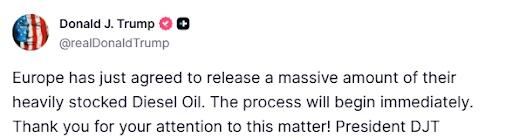
Trump was quick to respond too, with no real gloating yet...

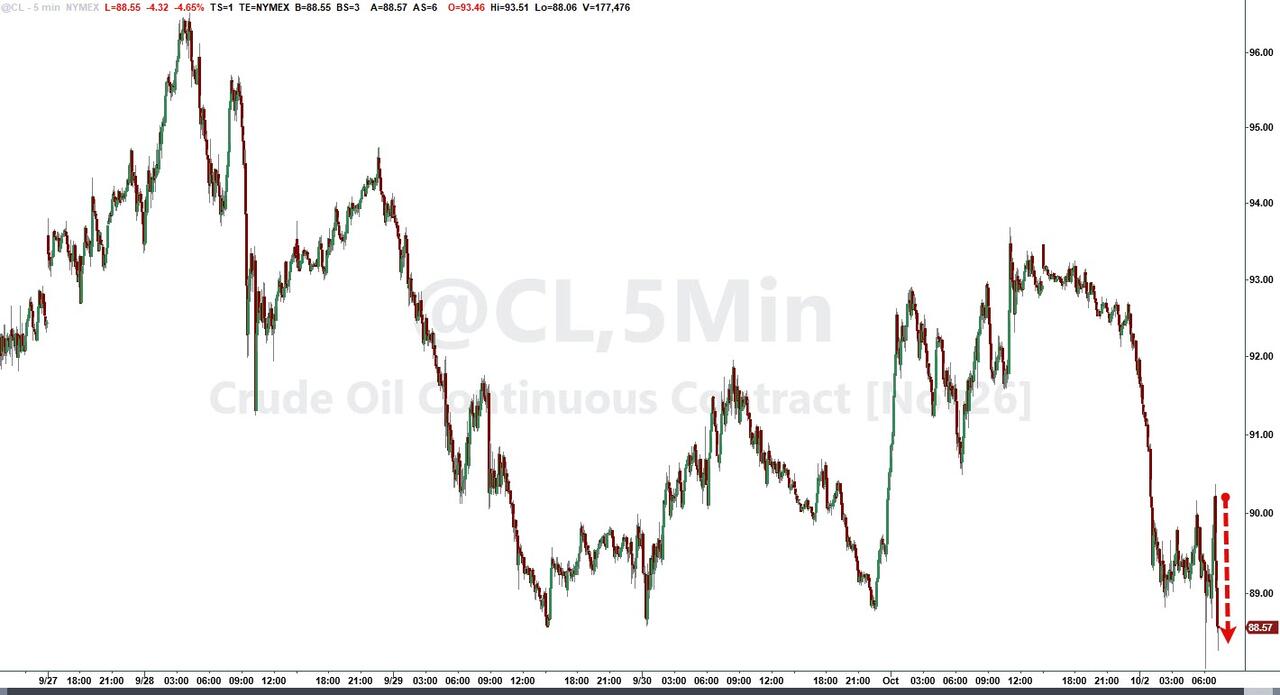
Oil prices fell back towards the low of the day on the news...

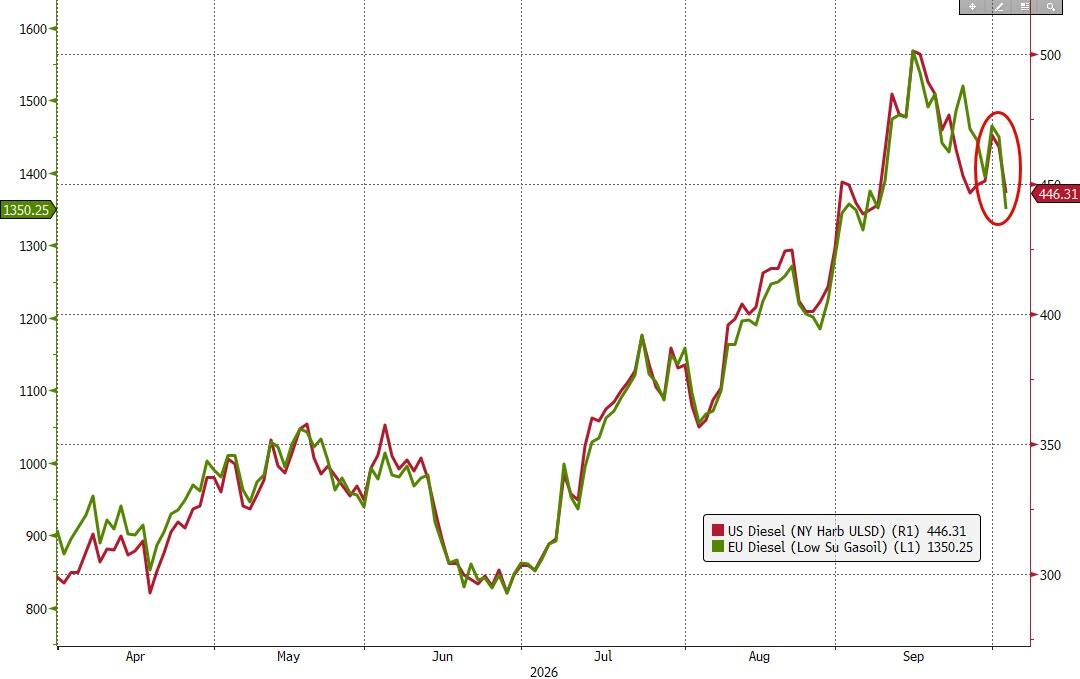
Both US and EU diesel prices are also lower...

With little oil of its own, and an outsized appetite for diesel, Europe again found itself bargaining from a position of relative weakness... and bending the knee.

*  *  *

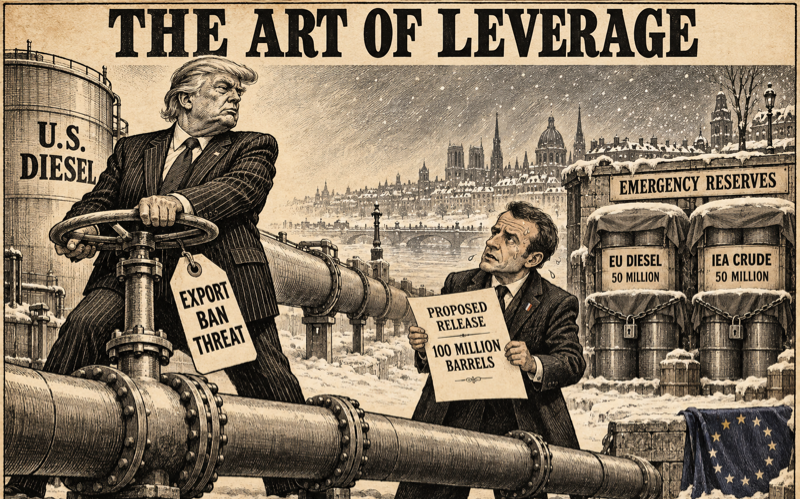
As we detailed earlier, Bloomberg's reported that France proposed that other European countries and International Energy Agency members release 100 million barrels of diesel and crude oil from emergency stockpiles would signal that Brussels is caving to President Trump’s demand. 

Europe's dependence on US fuel supplies gives the Trump administration major bargaining power as the continent approaches winter with below-average energy supplies and exposure to higher costs if a cold snap or further supply disruptions materialize.

The report has not been officially confirmed and is based on sources, but it says European countries are considering releasing 50 million barrels of diesel, with International Energy Agency members making another 50 million barrels of crude available.

One day earlier, Reuters reported that the Trump administration asked Germany and France to release emergency diesel inventories to help create a buffer against the supply squeeze in the industrial fuel or face a potential US diesel export ban.

The art of wheeling and dealing is all about leverage, and it appears the US threat of a diesel export ban might be enough to make Europeans come to their senses and dump emergency fuel and crude supplies onto the market.

Bloomberg also mentioned that French President Emmanuel Macron and President Trump spoke overnight and that G7 leaders are set to convene around 0830 ET.

"It is in Europe's best interest to work with the United States as we pursue multiple pathways to boost the supply of refined products and lower costs for consumers," one source, a US official, told Reuters on Thursday.

Tyler Durden Fri, 10/02/2026 - 10:05

Jobs Huge Miss: Sept Payrolls Plunge To 29K, Below All Estimates As July Revised Negative... But Employment Soars

Jobs Huge Miss: Sept Payrolls Plunge To 29K, Below All Estimates As July Revised Negative... But Employment Soars

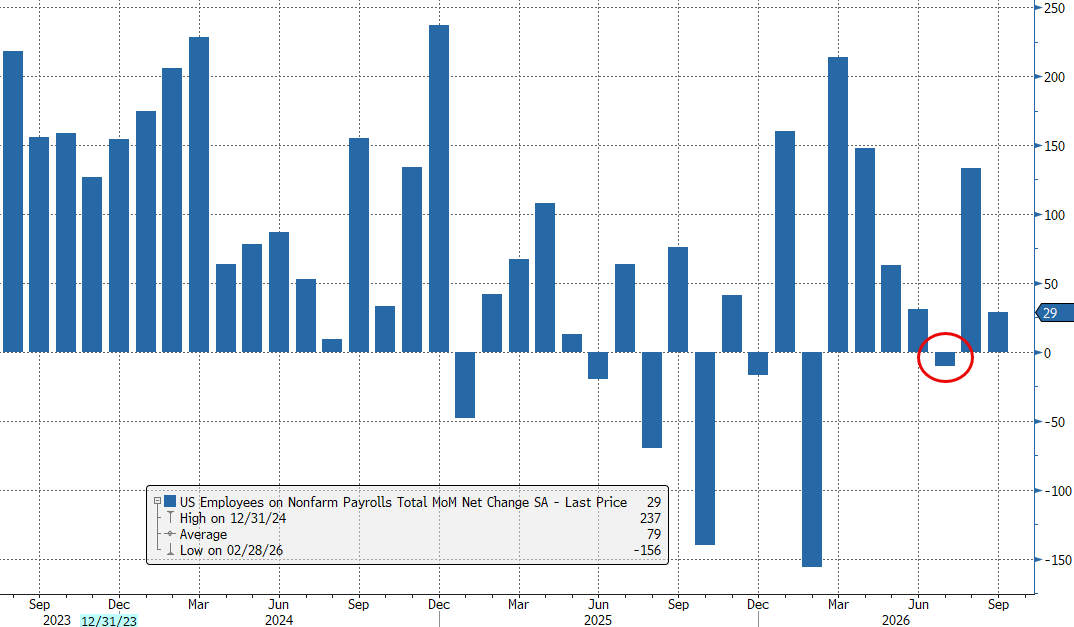
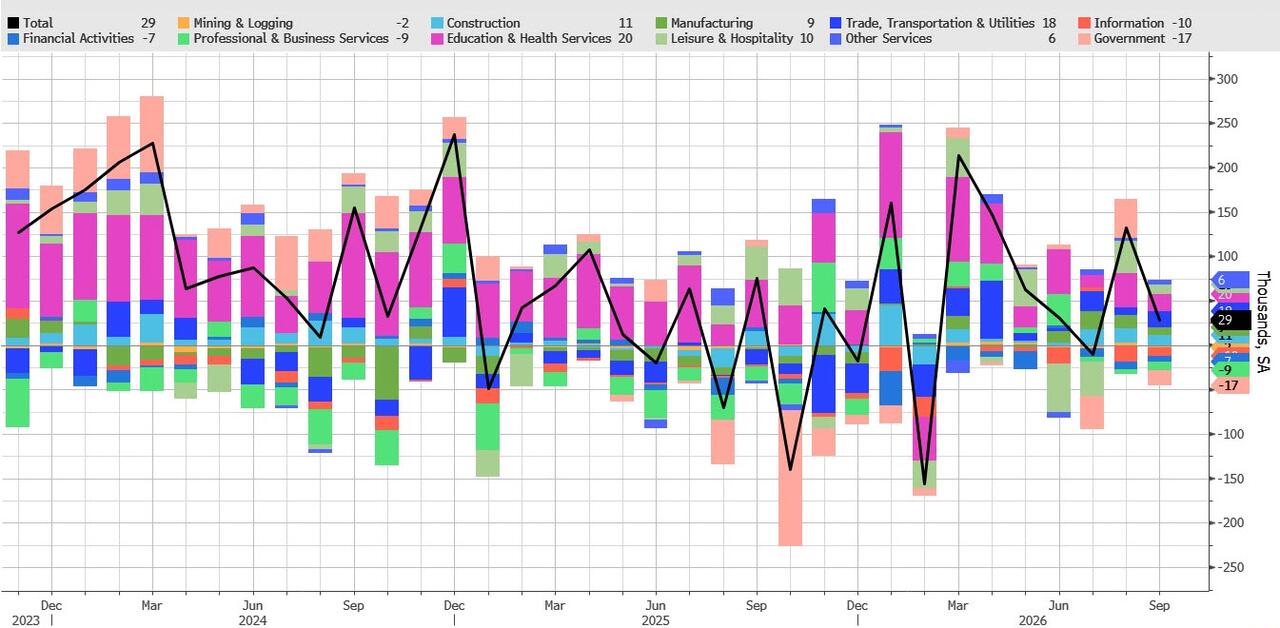
In our jobs preview post, we told readers to "beware a bond squeeze as august seasonals reverse" and boy were we right: yields are tumbling from 5.22% to 5.16%, a new weekly low, as all those record TSY shorts get bigly squeezed following what was a big miss in the September jobs print which tumbled from a downward revised August (as we said it would be) 133K vs 162K originally to just 29K.

It wasn't just August that was revised down by 29,000, from +162,000 to +133,000: July was also revised down by 31,000, from +21,000 to  -10,000.  This means that the original negative print of -23K, and which was revised up to 31K last month, is now once again negative and that had the Fed known this, it most likely would not have hiked last month. With  these revisions, employment in July and August combined is 60,000 lower than previously reported. 

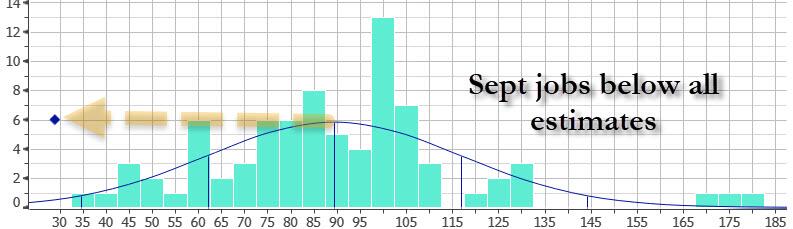
More notably, the 29K job print was below all estimates, which is amusing since August was originally above all estimates, but has since been revised sharply lower and just in line.

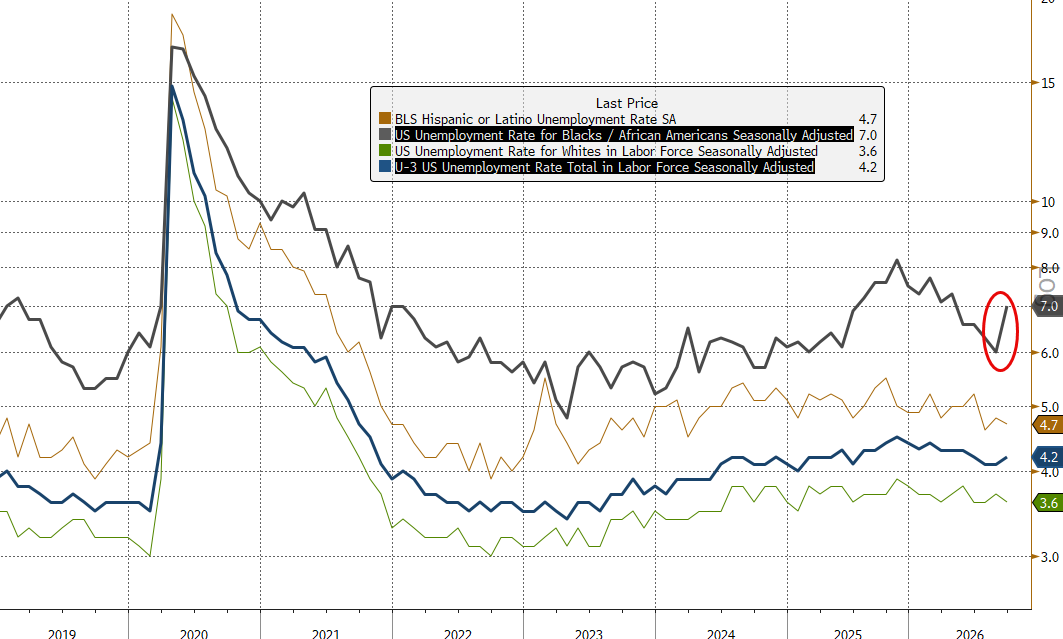
While the headline payrolls print was a big miss, the unemployment rate actually rose to 4.2%, from 4.1%, and above estimates of an unchanged print, as the number of unemployed workers rose to 7.109MM from 7.031MM, up 78K, while the labor force rose by 485K to 170.262MM. Among the major worker groups, the unemployment rate for people who are Black (7.0 percent) jumped in September. The jobless rates for adult men (3.9 percent), adult women (3.6 percent),  teenagers (14.5 percent), and people who are White (3.6 percent), Asian (2.9 percent), or Hispanic  (4.7 percent) showed little change over the month.

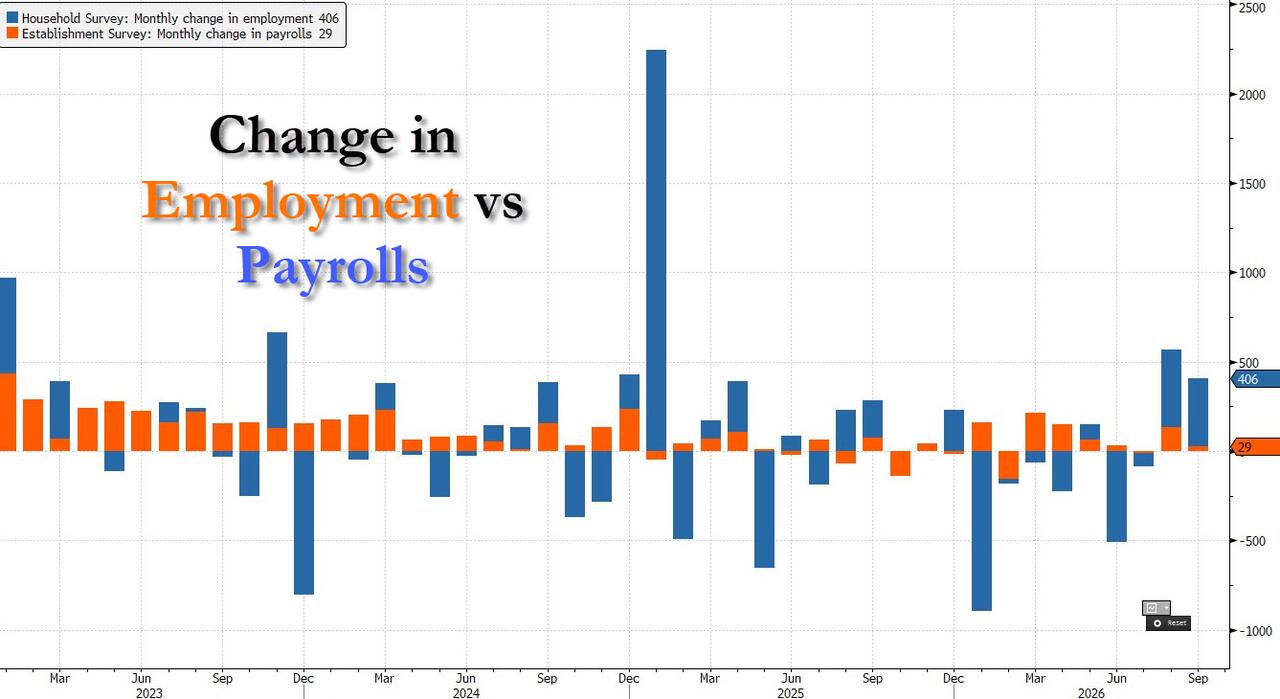
As for the specific reason why the unemp rate rose despite the drop in payrolls, that's because the Household Survey showed a 406K surge in the number of employed workers, the second highest since Jan 2025 (only August's 569K was higher)...

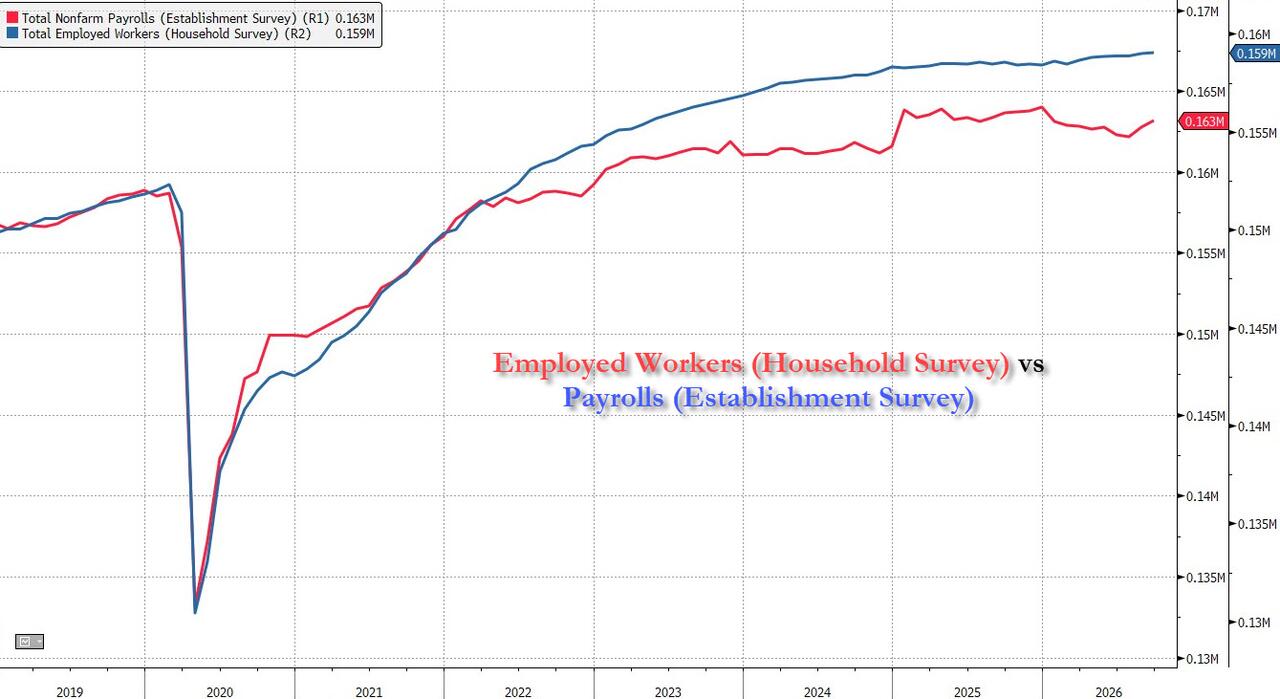
... which pushed the total number of employed workers to 163.152MM, the highest since January.

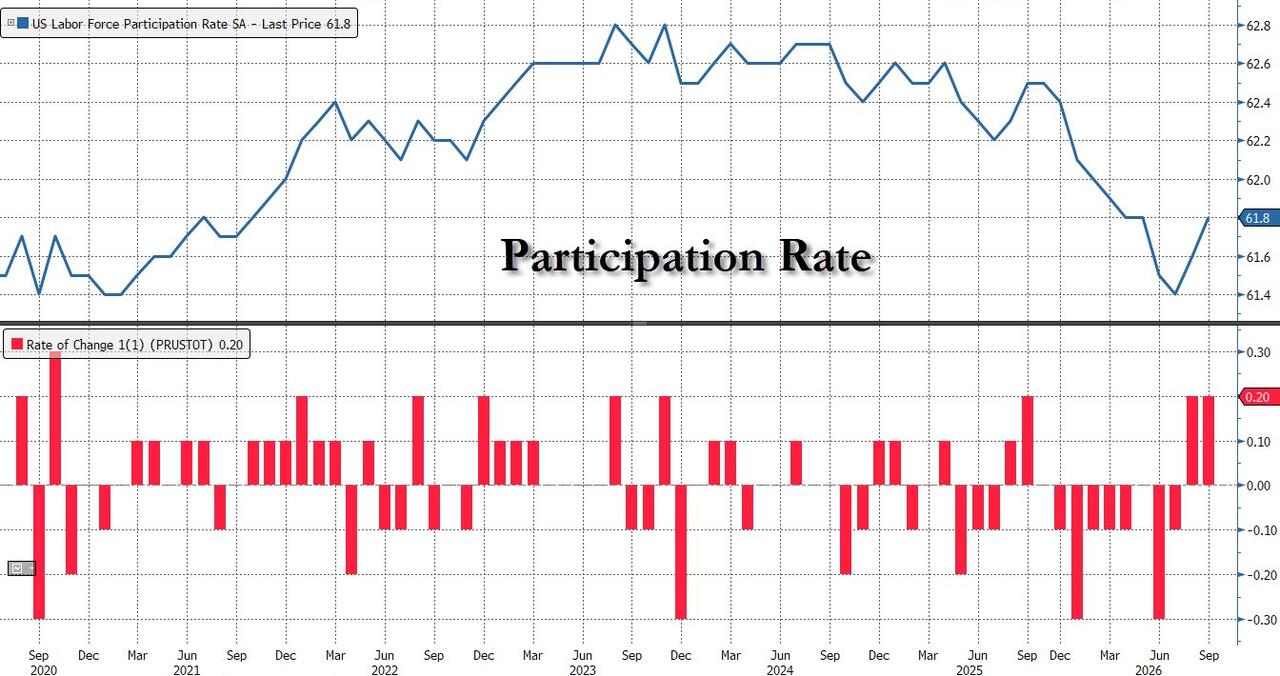
It's also why the participation rate has jumped sharply in the past two months after dropping to a 5 year low in July.

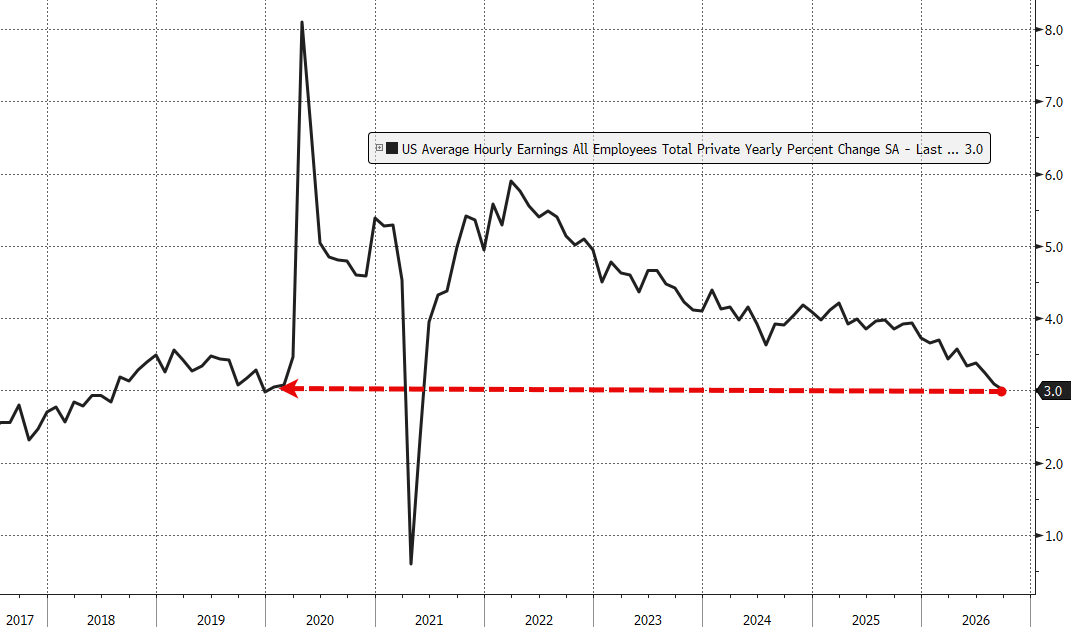
There was some more relief on the inflation front as average hourly earnings rose just 0.1%, below the 0.3% expected, which pulled the annual wage growth to just 3.0%, down from 3.1% and below estimates of an unchanged print.In September, average hourly earnings of private-sector production and  nonsupervisory employees rose by 7 cents, or 0.2 percent, to $32.60. 

The average workweek for all employees on private nonfarm payrolls remained at 34.4 hours in September. In manufacturing, the average workweek was unchanged at 40.6 hours, and overtime held at  3.0 hours. The average workweek for production and nonsupervisory employees on private nonfarm payrolls remained at 33.8 hours. 

Taking a closer look at the numbers in the report, we find the following:

  • The number of long-term unemployed (those jobless for 27 weeks or more) was essentially unchanged  at 1.9 million in September. The long-term unemployed accounted for 27.1 percent of all unemployed  people. 
  • Both the labor force participation rate, at 61.8 percent, and the employment-population ratio, at  59.2 percent, changed little in September. These measures showed little net change since January.  
  • The number of people employed part time for economic reasons changed little at 4.5 million in  September. These individuals would have preferred full-time employment but were working part time  because their hours had been reduced or they were unable to find full-time jobs. 
  • In September, the number of people not in the labor force who currently want a job changed little  at 5.8 million. These individuals were not counted as unemployed because they were not actively  looking for work during the 4 weeks preceding the survey or were unavailable to take a job. 
  • Among those not in the labor force who wanted a job, the number of people marginally attached to the labor force decreased by 236,000 to 1.5 million in September. These individuals wanted and were available for work and had looked for a job sometime in the prior 12 months but had not looked for work in the 4 weeks preceding the survey. The number of discouraged workers, a subset of the marginally attached who believed that no jobs were available for them, changed little over the  month at 414,000. 

Next, looking at the actual industries in today's report, we find the following: 

  • Health care employment continued its upward trend in September (+17,000), but at a slower pace than the average monthly gain over the prior 12 months (+33,000). In September, employment continued to trend up in ambulatory health care services (+13,000) and in hospitals (+12,000), while nursing and  residential care facilities lost jobs (-9,000).
  • Employment in construction changed little in September (+11,000). The industry had added an average of 10,000 jobs per month over the prior 12 months. In September, employment in nonresidential  specialty trade contractors continued to trend up (+12,000).
  • Manufacturing employment was little changed in September (+9,000) but is up by 72,000 since a recent low in December 2025. Over the month, employment increased in plastics and rubber products manufacturing (+5,000) and in machinery manufacturing (+5,000).
  • In September, financial activities employment was little changed (-7,000). Employment in financial activities is down by 129,000 since a recent peak in May 2025, with most of the job loss in insurance carriers and related activities (-90,000).
  • Employment also showed little change over the month in other major industries, including mining, quarrying, and oil and gas extraction; wholesale trade; retail trade; transportation and warehousing; information; professional and business services; social assistance; leisure and  hospitality; other services; and government.

And visually:

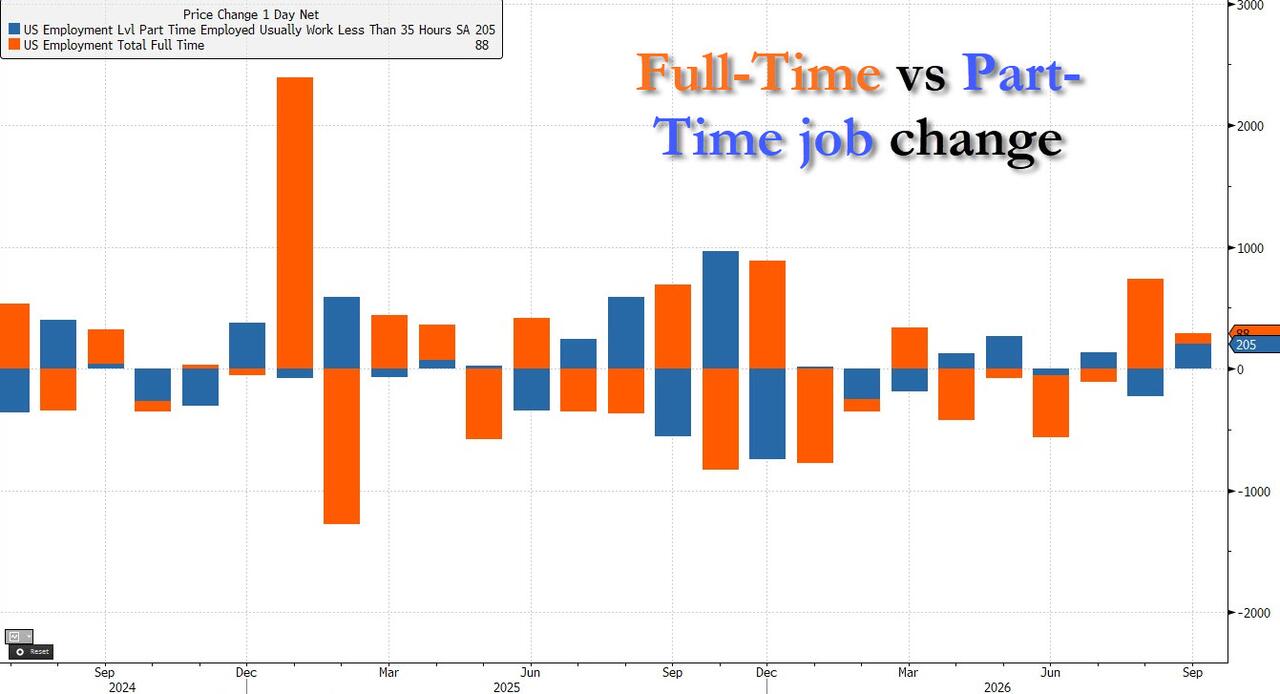
There were no major surprises below the surface, as part-time jobs rose by 205K to 28.746MM while full-time jobs rose by 88K to 134.376MM.

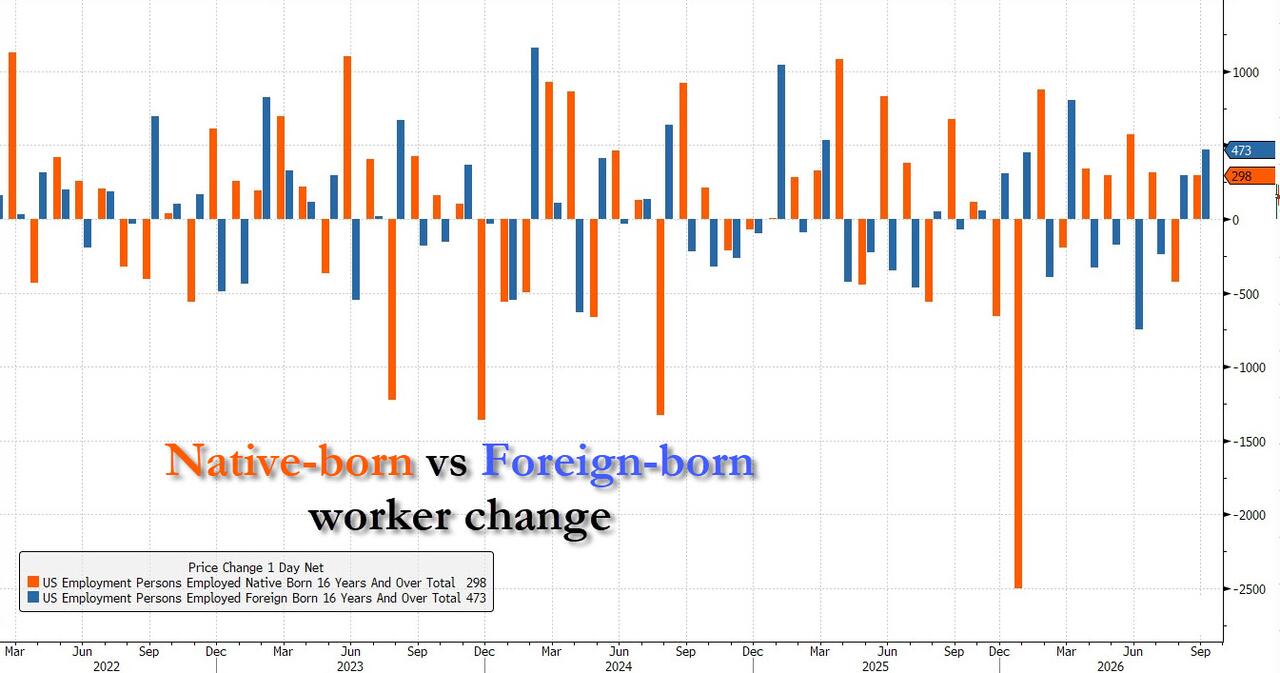
Finally, looking at the breakdown in native vs foreign-born, there were no surprises here too, as the number of US born workers rose by 298K while foreign-born workers surged by 473K, on other words, back to the old normal.

Overall, this was a mixed report, with the Household Survey painting a much stronger picture than Establishment (hence unemployment rate higher). But since the market - and by extension the Fed - are mostly swayed by the Payrolls part of the equation, it is not surprising that the market reaction today is one where bonds are getting massively short squeezed after the payroll print which missed all estimates.

Tyler Durden Fri, 10/02/2026 - 09:55

"Can We All Just Admit This Is Just Absurd?!"

"Can We All Just Admit This Is Just Absurd?!"

Thousands and thousands of people staring at screens. Not teenagers checking out TikTok, but highly educated, well trained professionals, staring at screens. Millions, even billions, maybe even trillions of dollars, yen, euro, etc., poised to move around based on the data that comes out at 8:30 am.

Then we get another mishmash of data, so different than expectations, with revisions bigger than the number itself, and are supposed to make something of the data?

As Academy Securities' Peter Tchir writes, "can we all just admit this is absurd!?"

Let’s pretend that data is valid and go through the motions under the assumption that this is anything other than a wild guess, using methods and technologies that should have been updated years ago, if not decades ago.

Only 29k jobs vs expectations of 90k. Ugh.

-60k of downward revisions after last month’s 55k. Ugh.

Only 46k in private payrolls, which also got revised down from the initial guestimate of 127k to 89k. Ugh.

Somehow the 3 month moving average is now 51k this month and last. Hooray??

Hourly earnings dropped, good for wage pressure inflation, bad for anyone trying to make ends meet.

The unemployment rate rose 0.1%, but largely due to an increase in the labor participation rate of 0.2%. I kind of like that, assuming it is remotely accurate, which seems like a silly assumption to make, but one that we are all forced to make. The underemployment rate actually ticked down, which again, if real, is good. All of this is based on the Household Survey which said we added 406,000 jobs in September. One is known to be more wildly inaccurate than the other hugely inaccurate number, but 406k sounds pretty darn good, if it was real, which it probably isn’t.

The birth/death model showed job losses of 190k.That is not seasonally adjusted, and I don’t now how much that subtracted (or possibly added) to the NFP headline number, but again (this time in a different direction), it seems “strange” that a “plug” (or calculation) is in the same order of magnitude of the number it is helping to “true up”.

We will get the obligatory rally in bonds (and the numbers are “tepid” enough) that the bond rally should help equities along, but there is a better chance of me breaking par, than that these numbers are truly useful in judging anything. We will use the numbers because “we have nothing better” but that increasing seems like a giant cop-out!

Seriously, if you were in a class and were told billions of dollars would be made or lost on a number that even the people looking at the number don’t believe, you’d shake your head in incredibility, that this really was going on. Not just for a month or two, but for years and years!

Can’t we use electronic paycheck data to get a pretty accurate number for all those who are getting paychecks? Wouldn’t that cover a big part of the economy. Wouldn’t knowing, with a high degree of exactness, how that part of the workforce (those who receive at least one check in a month) is evolving over time be useful? We could attempt to get the rest, but something that covered a vast swath of the economy, and was reasonably likely to be accurate and real-time, would seem a good goal.

Yes, I continue to hope to somehow land on a data task force committee, because this just seems more and more unbelievable all the time.

It is very good that Warsh in particular keeps telling us not to focus on any one month’s data, nor any one data series. That I’m in full agreement on, which is why I expect this initial reaction to fade.

You’d like to think ADP can capture some of what I’d like to see, and maybe last month’s 36k and this month’s 90k are more accurate? But who knows. But, also a reason not to fully trust today’s data.

Two pieces of data that I think are more difficult to “fake” or (more accurately, get absurdly wrong), are the JOLTS Quit rate which remains low at 1.9%.  People could be so happy with their current jobs they aren’t even thinking about another job (I know I am), but generically, I think it represents a “take this job and shove it” vibe, which increases when the perception is that equal or even better jobs are easy to find. The JOLTS Hires rate came in at 3.3% this month.  It has been stuck right around this level, which is a little lower than the 3.8% or so we typically saw in 2016 through 2019. Consistent with a no hire, no fire employment situation.

Bottom Line

We can examine data that the Fed may use to hike, pause or even cut, but the big drivers remain the same:

  • The Iran War.

  • The Price of Diesel.

  • Compute Spend. Including the threat of Cheap Chinese Compute.

  • Whatever is going on with European bond yields. The German 2 year bond yield has declined from 3.31% on Monday to 2.99% as of Friday morning. The French 2 year has moved from 3.62% to 3.77% in that same timespan. From 31 bps to 78 bps in a week is pretty ugly.

  • Some real weakness in credit spreads. I cannot remember the last time credit spreads seemed particularly interesting on the macro front, but they are again, with CDX moving from 50 to 60 in 2 weeks. Certainly not alarming but can’t help but look.

With the bond market shaky, and the excitement of this data like to fade as the morning wears on, we will all be back to placing bets on the above issues very soon.

Tyler Durden Fri, 10/02/2026 - 09:45

Tesla Delivers 486,432 Vehicles In Q3, Handily Beating Wall Street Forecasts

Tesla Delivers 486,432 Vehicles In Q3, Handily Beating Wall Street Forecasts

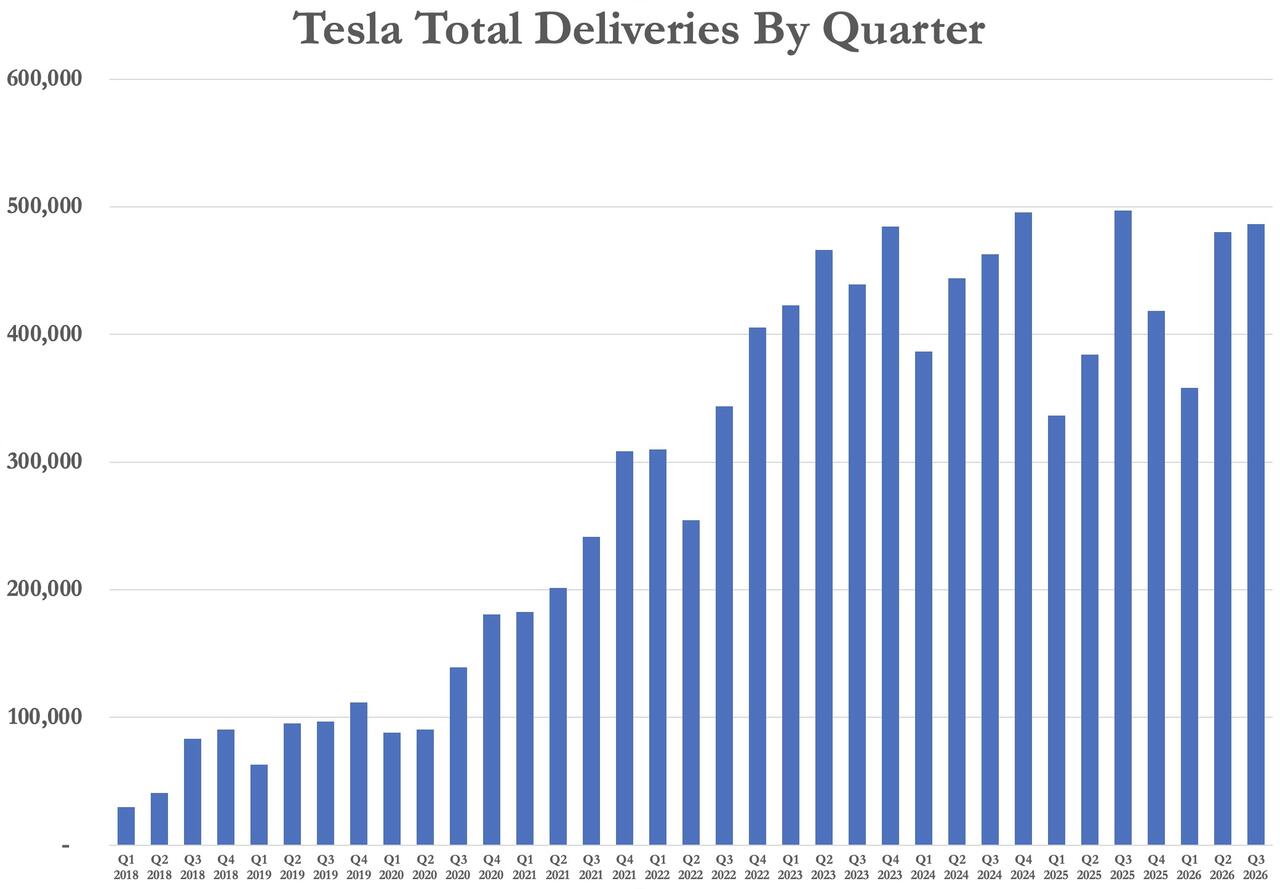
Tesla handily beat expectations on deliveries for Q3 this morning, handing the electric vehicle maker a sizable beat against Wall Street forecasts.

The company delivered 486,532 vehicles during the quarter, well above the roughly 461,000 units analysts surveyed by FactSet had been expecting. Tesla’s own compilation of sell-side estimates had put the consensus at 461,974 vehicles, meaning actual deliveries came in roughly 24,500 vehicles, or about 5.3%, above that figure.

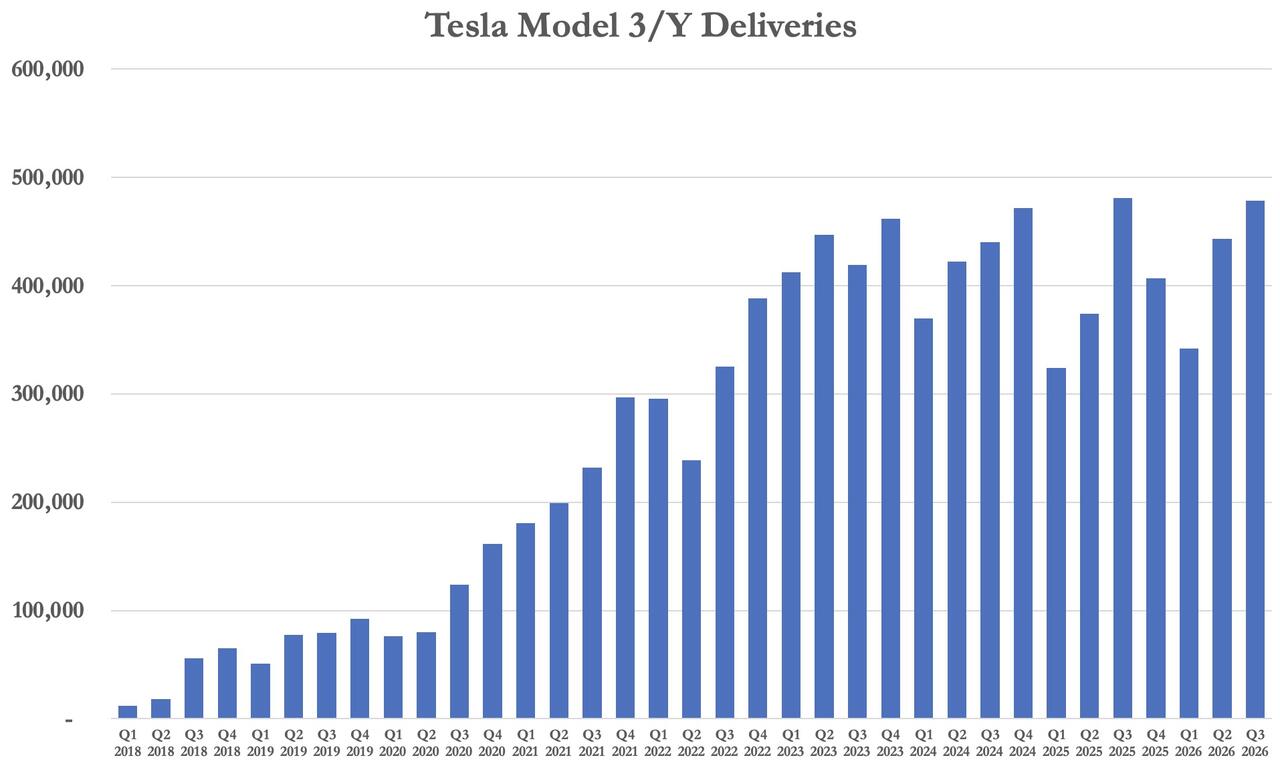
Of the 486,532 vehicles delivered, Model 3/Y accounted for 478,237 vehicles.

The better than anticipated result helped Tesla shares rise about 2% Friday morning.

Tesla’s quarterly delivery report remains one of the clearest measures of the health of its core business, even as Elon Musk has increasingly argued that the company’s long-term value will be determined by businesses that have little to do with selling conventional electric vehicles.

Musk has spent much of the past year directing investor attention toward autonomous driving, artificial intelligence and Tesla's Optimus humanoid robot. He has repeatedly described Tesla as an AI and robotics company rather than simply an automaker, while arguing that autonomous vehicles and Optimus could eventually become much larger businesses than vehicle sales.

Musk has also continued to emphasize Tesla’s planned Cybercab network and the expansion of its autonomous driving technology as central pieces of the company’s future.

For the time being, however, automobiles remain Tesla’s primary source of revenue and cash flow. That makes quarterly deliveries an important indicator of consumer demand, pricing conditions and utilization at the company’s factories in the United States, China and Germany. 

The result also arrives as Musk continues to divide his attention among several companies. His other major venture, SpaceX, recently recorded an important success with Starship's first orbital flight, moving the company closer to commercialization. 

Tyler Durden Fri, 10/02/2026 - 09:35

Trump Admits Diesel US Export Ban Could Raise Gasoline Prices

Trump Admits Diesel US Export Ban Could Raise Gasoline Prices

Authored by Tsvetana Paraskova via OilPrice.com,

A potential ban on U.S. diesel exports could have "a negative impact on gasoline," U.S. President Donald Trump said late on Wednesday, although he didn't rule out such a move from the Administration.

The President told reporters in the Oval Office that he and the Administration continue to discuss the pros and cons of a diesel export ban every day, "but it just seems that it would have a negative impact on gasoline."

Earlier this week, Goldman Sachs analysts also warned that a U.S. diesel export ban would push domestic gasoline prices higher as refiners could be forced to reduce processing rates.

President Trump on Wednesday appeared to be less inclined to ban diesel exports than a few days ago, but he has not yet ruled out the idea that emerged last month as retail diesel prices in the United States hit $6 per gallon nationwide average for the first time ever, and then $6.50 a gallon.

As a result of the jump in crude oil prices and a worsening global crunch for fuels, U.S. gasoline prices are also at a record high level for this time of year, even as demand is easing after the end of the peak driving season. At an average nationwide price of $4.43 per gallon, the price of regular gasoline is higher than the $4.08 from a month ago and way higher than $3.15 per gallon on this day in 2025.

Diesel prices have hit record highs in many economies amid refinery constraints in the Middle East and Russia, which refineries elsewhere cannot offset even if they run at maximum utilization rates, as is the case in the United States.

Refinery capacity is constrained in the Middle East due to Iranian strikes on refineries and the trickle of fuel flows through the Strait of Hormuz. Then there is also severely restricted capacity in Russia due to Ukrainian drone strikes at Russian refineries. Russia has just extended its ban on diesel exports through October 31.

Tyler Durden Fri, 10/02/2026 - 09:10

'Massive Short Squeeze': Yields, Rate-Hike Odds Plummet After Piss-Poor Payrolls Print

'Massive Short Squeeze': Yields, Rate-Hike Odds Plummet After Piss-Poor Payrolls Print

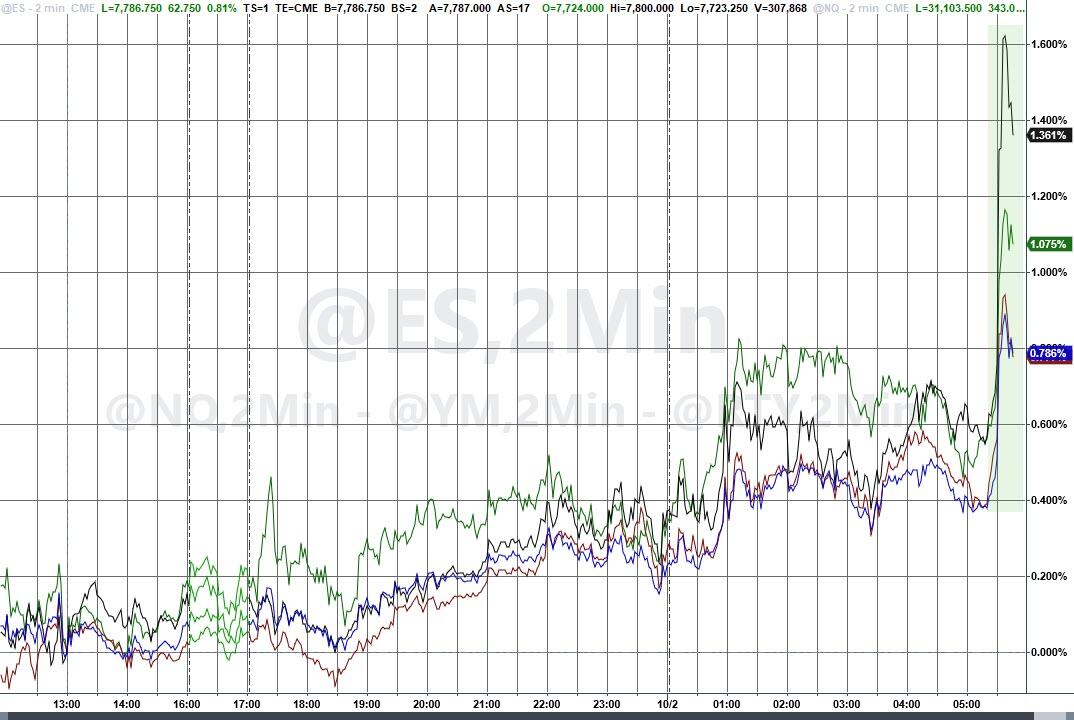
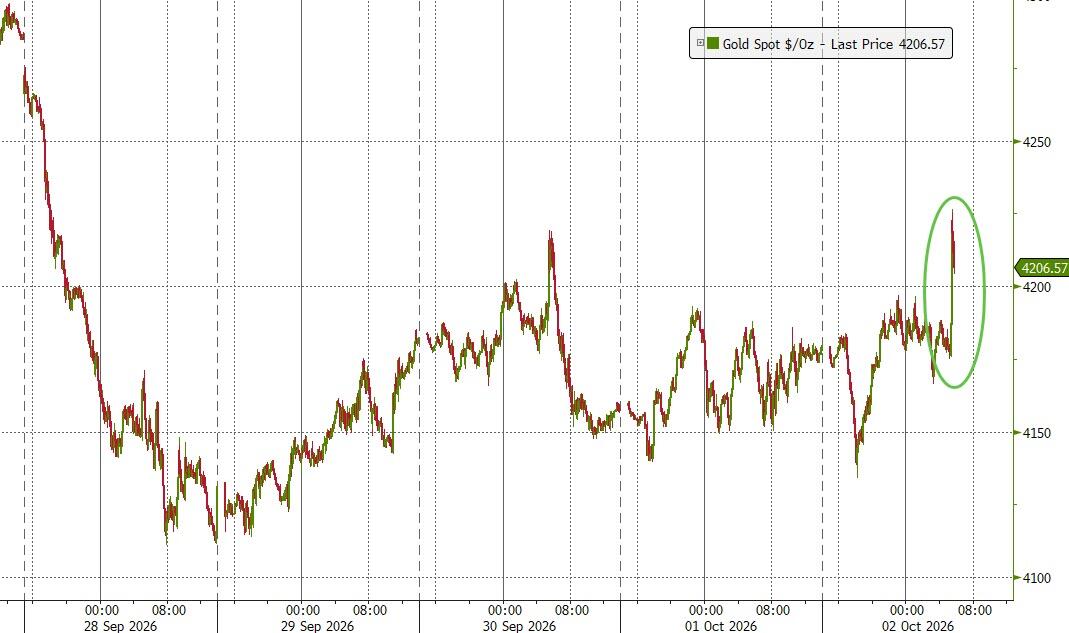
With nonfarm payrolls printing below even the weakest analyst's forecast, the market's reaction has been uniformly dovish with rate-hike odds plummeting, treasury yields tumbling, stocks soaring, dollar down and gold and crypto higher.

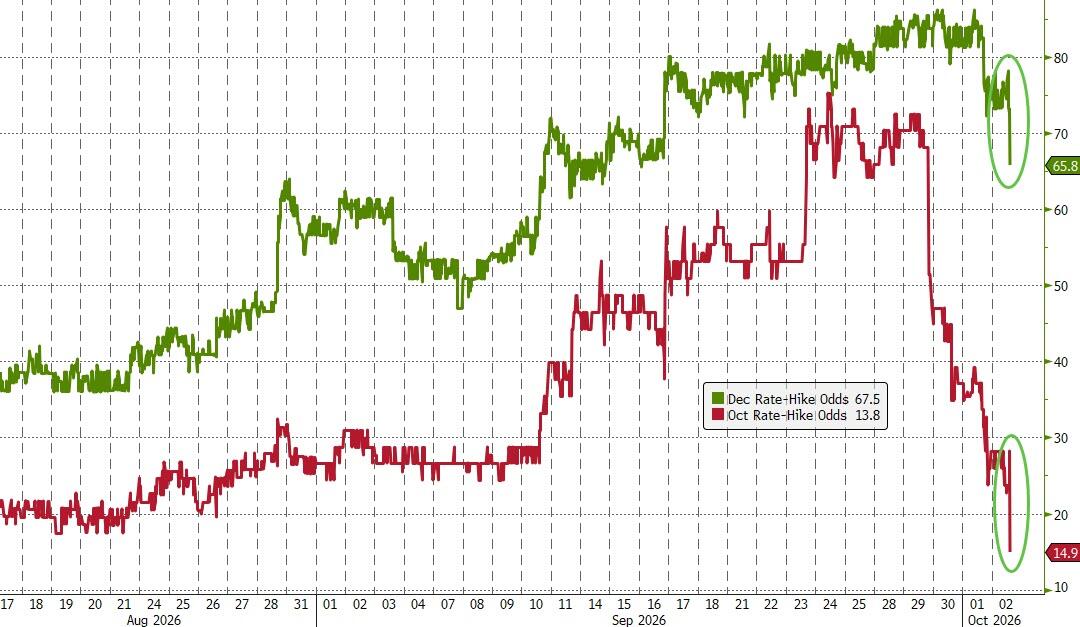
The biggest impact of the piss-poor payrolls print was the market basically pricing out a hike in October...

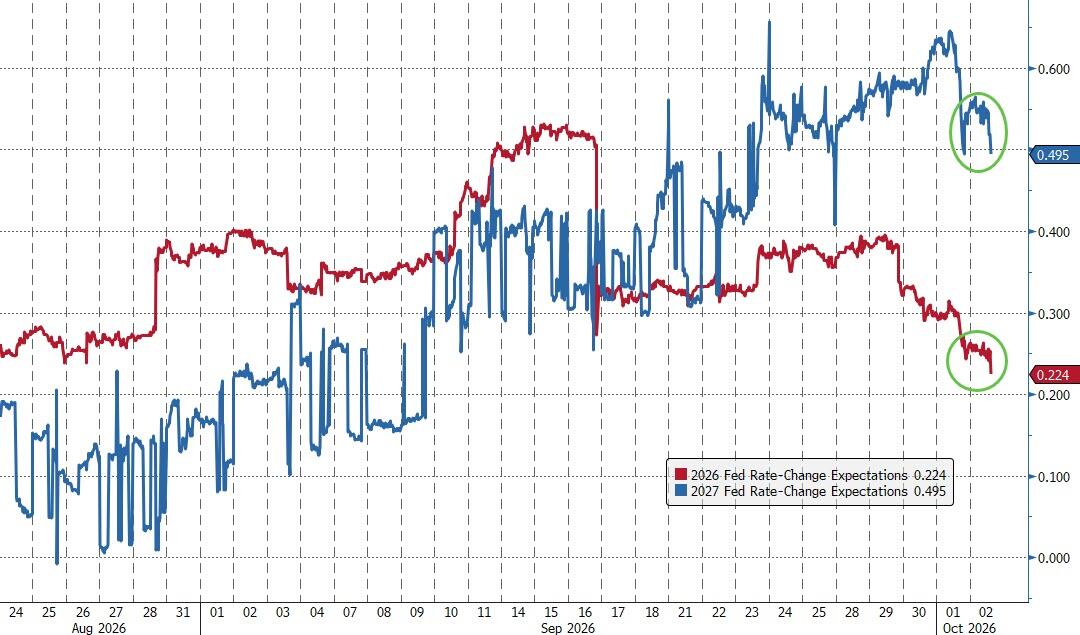
With less than one total hike (22.5bps) now priced in for 2026 (and only 2 more hikes in 2027)...

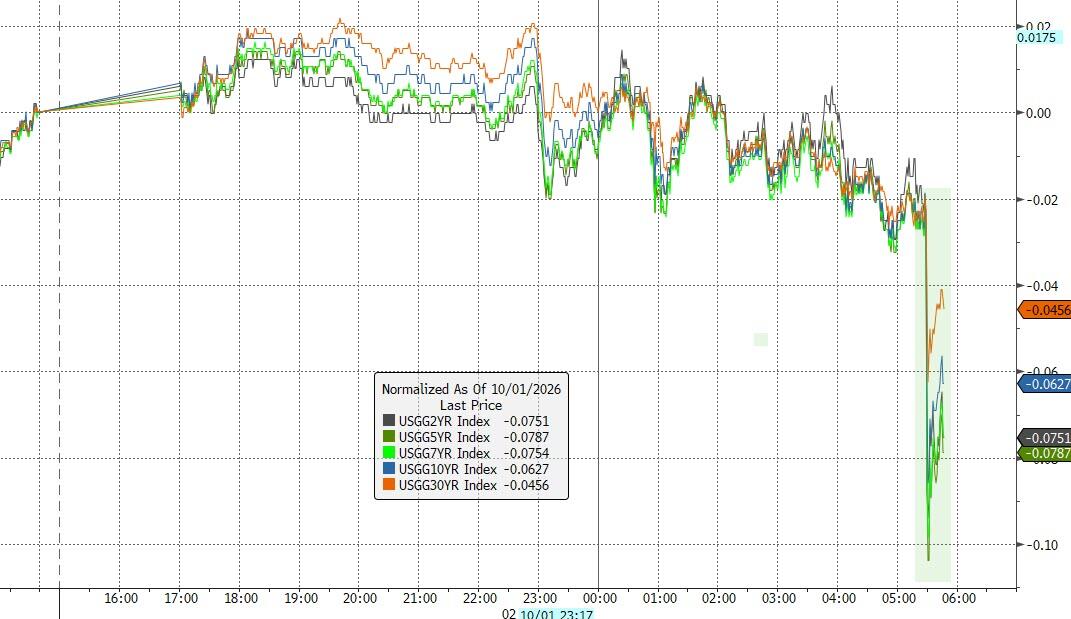
Yields are all down, led by the short-end...

Which makes sense given that heading into the print (as we previewed perfectly), Goldman's Brian Garrett says the bank's CTA model shows managers "extremely short global bonds (~$390bn notional)."

US 10Ys are at 99% of max short and 30Ys at 100%.

With systematic funds that short, a weak print, or even a 4.2% unemployment rate, could set off a massive short squeeze in bonds. 

Stocks spiked on the report, led by the most rate-sensitive names (Small Caps) and longest duration tech names...

And gold is rising (as the dollar dips)...

Tom Simons, chief US economist at Jefferies, said this payroll number “should be the nail in the coffin” for an October hike.

“We had been expecting that they would continue with successive 25 bp moves, but it now looks more likely that the policymakers emphasizing that they have some more time before another hike is needed will remain patient.”

With these revisions, employment in July and August combined is 60,000 lower than previously.

Makes you wonder if Warsh would have hiked at all if he had accurate data.

Finally, Christopher Hodge at Natixis doesn’t think these numbers move the Fed debate by a lot:

"This data won’t shift the broader decision making calculus for the Fed as inflation remains the supreme concern, but with wages lower and the jobs picture a bit less rosy, it certainly decreases the urgency to hike in October."

But with Jefferson and WIlliams already in the dovish/hold/wait-and-see camp, and the proximity to the Midterms, it seems October's hike is well and trul off the table (after topping 75% odds just a week or so ago).

Tyler Durden Fri, 10/02/2026 - 08:53

Futures Rise, Yields and Oil Drop Ahead Of Key Jobs Report

Futures Rise, Yields and Oil Drop Ahead Of Key Jobs Report

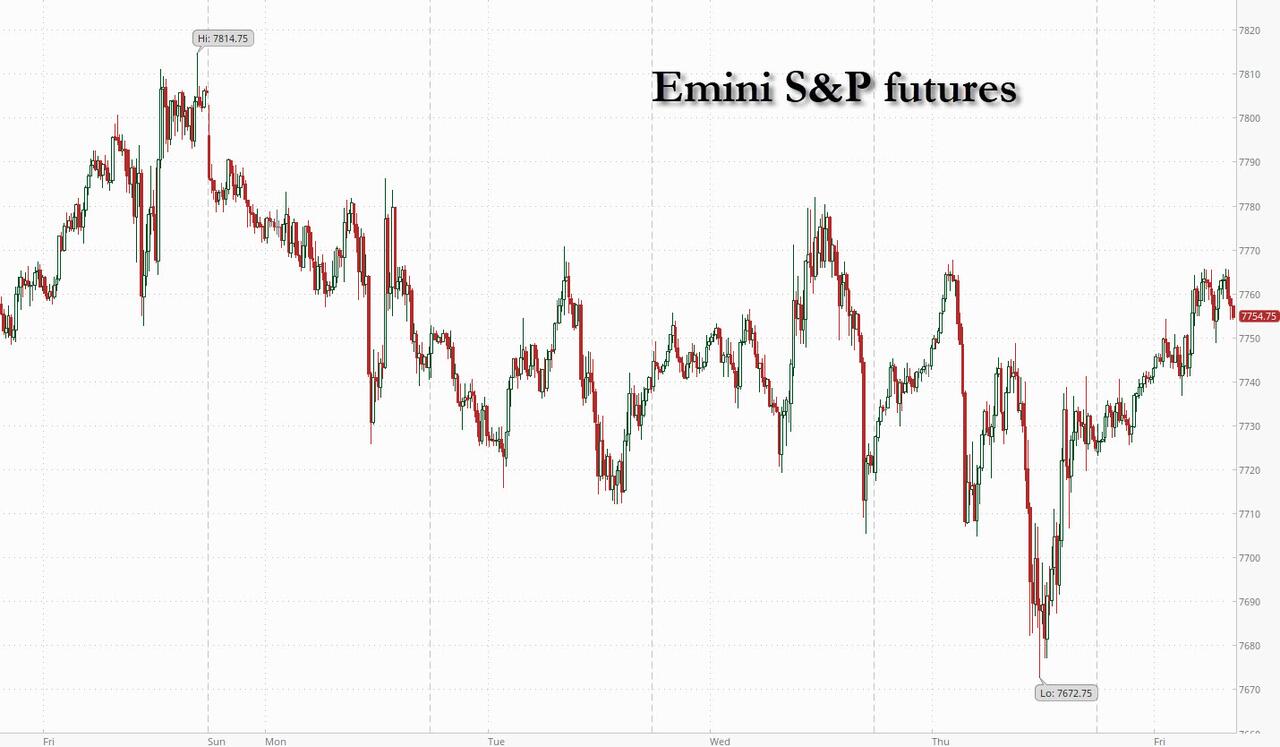
US futures climbed and bond yields reversed an earlier rise, as a drop in oil prices provides a tailwind in calm trading following a week in which markets were lashed by sharp swings in yields, with the US payrolls report still to come. As of 8:15am ET, S&P 500 futures were up 0.4% after Thursday’s close left the index headed for its worst week since August; Nasdaq 100 contracts have added 0.8%. In premarket trading, chipmakers rallied while all Mag 7 are higher, with NVDA (+1.7%) the outperformer. The stabilization in yields overnight, in addition to the Treasury rally yesterday, was supportive of risk assets. Overnight, there weren’t many new macro headlines, with investors waiting for NFP today. See Feroli’s preview below. Yet under the hood, tighter financial conditions are crushing equity breadth, which is now at levels last seen during the dot com bubble.  Bond yields are 1-2bp lower across the curve amid a -3.8% decline in oil. Treasuries gained across maturities with 10-year yields down 1 bp to 5.23% ahead of payrolls. While US rates were calm, Europe's debt crisis is getting worse as the premium on France’s 10-year yield over Germany’s hit its highest level since 2011 as unease over policy gridlock in Paris grew.  Gilts and bunds are rising in lockstep, with UK and German 10-year yields falling 6 basis points each. French bonds are lag peers, widening spreads further. Base metals fell 1-2%; precious metals were unchanged. The dollar snapped a four-day run of gains as it headed for a third weekly advance, which would be its longest under the current Presidential term. Bitcoin climbed. Today's US economic data slate also includes August factory orders 10 a.m. Fed speaker slate includes Dallas’s Logan (10 a.m.) and Chicago’s Goolsbee (12 p.m.)

In premarket trading all Mag 7 stocks are higher (Nvidia +1.7%, Alphabet +0.4%, Tesla +0.7%, Amazon +0.5%, Microsoft +0.9%, Meta Platforms +0.4%, Apple +0.2%)

  • Airbnb (ABNB) rises about 2% after KeyBanc Capital Markets upgraded the online travel company to overweight, seeing positive growth trends.
  • Edison International (EIX) falls 2% after Jefferies cut its recommendation on the utilities company to underperform on California wildfire liability risk.
  • Fair Isaac (FICO) falls 8% as the FHFA is planning to direct Fannie Mae and Freddie Mac within weeks to require lenders to pull credit data from two major credit reporting bureaus instead of three, according to a person familiar with the plans. TransUnion (TRU) falls 3% and Equifax (EFX) slumps 3%.
  • Nike (NKE) slumps 9% after the sneaker and sportswear maker’s revenue guidance for the full year fell short of consensus estimates.
  • Twilio (TWLO) rises 1% after S&P Dow Jones Indices noted that the stock will replace Warner Bros Discovery in the S&P 500 effective Oct. 6.
  • ON Semi (ON) climbs 8% after the chipmaker said it will buy Synaptics for $123 per share, revising their earlier all-stock deal to an all-cash transaction. Synaptics (SYNA) rises 15%.
  • Vylor (VYLR) climbs 3% after the Corteva Inc. seed spinoff was initiated with buy ratings on its growth profile.
  • Western Digital (WDC) falls 8% and Seagate Technology (STX) drops 12% after Nikkei reported that Toshiba would invest ¥60 billion to double its production capacity for hard disk drives.

In other corporate news RTX received a deal worth as much as $24.4 billion to accelerate production of a key anti-air and anti-surface missile for the US Navy;  Amazon is exploring a deal to shift about $8 billion worth of top-end Nvidia chips off its balance sheet into a special-purpose vehicle, according to the FT. Netflix reported a collaboration agreement with independent Spanish streamer Filmin.
Twilio will replace Warner Bros Discovery in the S&P 500, Vylor replaces Corteva in the S&P 500 and Moderna replaces Warner Bros Discovery in the Nasdaq 100. Nike is cutting jobs and embarking on a sweeping overhaul of its business as results deteriorate, a restructuring plan that it said will save $2.5 billion over the next five years. The FHFA is said to be planning to direct Fannie Mae and Freddie Mac within weeks to require lenders to pull credit data from two major credit reporting bureaus instead of three.

Sentiment was lifted after Brent fell below $100 a barrel as European countries were said to discuss the release of strategic reserves. The retreat took some pressure off the inflation outlook, helping traders pare expectations for US rate hikes to only one move this year. The odds of more than three over the next 12 months also receded.

Yet divisions are emerging at the Fed, with Lorie Logan wanting more hikes to cool inflation, while members of the central bank’s troika have been calling for patience to see how data unfolds over the coming weeks.

On that front, payrolls are first on the slate for today. The September jobs report is expected to show nonfarm payrolls increased 90k vs August’s 162k increase and unemployment rate steady at 4.1%; Bloomberg crowd-sourced whisper number for payrolls is currently 86 while Bloomberg Economics expects 55k, which would point to a labor market stuck in low-hiring mode with the drivers of job growth shifting. This mix — along with early tracking of cooler September core CPI — would do little to strengthen the case for another rate hike, according to Bloomberg (our full preview is here).  The US jobs report will be key at a time when resilient data are supporting riskier assets while giving the Fed room to fight inflation. 

“If we get a very high number or materially higher than 90,000, you could expect more pressure on yields from here,” said Sotirios Nakos, head of multi-asset portfolio management at Aviva Investors.  For Mabrouk Chetouane at Natixis IM, strong data will bode well for third-quarter earnings and see traders price “growth and Fed hikes accordingly.”

Andrea Tueni at Saxo Bank warned that a blowout report could put stocks at risk. “US equity markets have so far managed to cope with really elevated bond yields, but I’m not sure how high these can go from here before something breaks,” he said.

The S&P 500 Equal Weight Index is on track for its seventh-consecutive weekly loss, which would be its longest streak since May 2022. BofA’s Hartnett describes a market “trading long artificial intelligence” (Nasdaq 100), “short artificial irrelevance” (S&P 500 Equal Weight). US equities saw $2.7 billion exit in the last week of the quarter, according to BofA citing EPFR Global data, while global bond funds drew $18.8 billion. Flows provide evidence of investors shifting to the safest paper, with Treasuries enjoying the 14th consecutive week of inflows.

High oil prices, AI giants’ surging demand for capital and a crowded short base in Treasury futures have fueled a spike in bond volatility that has rippled across asset classes. Thursday brought an unusual divergence, with Treasuries rallying on haven demand while riskier debt came under intense selling pressure.

Meanwhile,high-grade debt has lost some of its haven appeal as spreads on global corporate bonds blew out this week to their widest in six months. Fresh evidence of building price pressures came from the euro area, where inflation quickened to a three-year high. At the same time, bond traders were nursing losses after Paramount’s debt issue, to fund the biggest Hollywood buyout ever, cratered in initial trading. Meanwhile, Broadcom’s Wall Street syndicate are starting to gather $60 billion of fresh AI chip financing to benefit Anthropic and other companies.

In politics, Trump predicted that Democrats would impeach him for a third time if they retake control of Congress, seeking to boost voter enthusiasm for Republican candidates, as his approval rating hits new lows. The US administration has diverted aid set for EMEA countries to conservative-leaning governments in Latin America, the Washington Post reported.

Separately, governments around the world are running out of room to shield consumers from higher energy prices, with fuel subsidies potentially costing more than $1 trillion this year, according to a United Nations study.

In Europe, the Stoxx 600 has climbed 0.7% after three days of losses, with technology stocks leading gains. Still, Europe is set for a weekly drop, the fourth in five weeks. as bond markets remained under pressure from inflation concerns. IG Group slumped after it issued an unscheduled third-quarter update. Here are the biggest movers Friday:

  • Universal Music Group shares rise as much as 3.3% after an upgrade to overweight at Barclays. The music label company’s stock is inexpensive for the first time after a period of underperformance, according to the bank
  • Hensoldt shares rise as much as 5.2% as the German defense firm is upgraded to buy from hold by Kepler Cheuvreux, which says earnings and order momentum are poised to accelerate
  • BT shares rise as much as 4.4% on Friday after the Financial Times reported that the telecom firm has opened talks with UK government officials over the possibility of buying TalkTalk
  • J D Wetherspoon shares rise as much as 8.9%, to the highest level since March 2022, as analysts are encouraged by robust current trading, boosted by favorable weather
  • IG Group falls as much as 27%, the most since 2016, after an unscheduled third-quarter update in which it cut its 2026 revenue growth outlook to the mid-single digits from 10%-15%
  • Sanofi falls as much as 4.6%, the most since July, as Citi flags skepticism surrounding the French drugmaker’s announcement yesterday of an expanded partnership with Regeneron
  • Kering falls as much as 6.5% as JPMorgan flags a tougher luxury backdrop and slower Chinese recovery for the French luxury-goods company after discussions with Kering’s investor relations team
  • European sportswear stocks are sliding this morning after US firm Nike fell in extended trading on Thursday, following weaker-than-expected quarterly sales and a disappointing outlook for full year revenue. Analysts at Vital Knowledge described the sales guidance as “pretty ugly”

For Europe, “the key issue from a monetary policy perspective is any adverse spillovers from higher energy prices,” noted Pia Fromlet and Marcus Widen at SEB. “The test for how strong this effect will be is still ahead of us. Up until October the narrative of little evidence of indirect effects remains.”

Asian stocks fell to head for their worst week since mid-July, pressured by rising yields and US troop deployment concerns in the Middle East. The MSCI Asia Pacific Index was down as much as 1% on Friday before paring some of the losses. The gauge is still on track to close the week down 1.1%, the most since the week ending July 17. The stock markets in Hong Kong and Japan slumped, while South Korea and Taiwan gained.    Hong Kong was the region’s worst-performer, down the most since March, as investors fretted over tech companies’ potentially higher borrowing costs. Alibaba, Tencent and Xiaomi were some of the lead decliners in the Hang Seng Index.  Asia’s bank stocks, including HSBC, were also trading lower, tracking moves in global peers amid concerns over higher yields and potential UK tax hikes targeting the sector.

In FX, the Bloomberg Dollar Spot Index is down 0.4%. The Japanese yen and Swiss franc are the best performing G-10 currencies, rising 0.3% each.

In rates, treasuries hold small gains in early US session led by intermediate- to long-end tenors, slightly flattening the curve. US 10-year yield is down about 2bp near 5.22% vs declines of 9bp and 7bp for German and UK counterparts; European government bonds rallied out the gate this morning and remain in the ascendancy as a drop in oil prices provides an additional tailwind.  French 10-year is about 3bp cheaper on the day.  Bunds and gilts outperform amid lower oil prices and haven bid as French bonds weaken. IG dollar issuance slate is blank so far and expected to remain quiet. Weekly volume stands at about $33 billion vs dealers’ $50 billion projection; they anticipate $100 billion of supply in October. US session features September jobs report at 8:30 a.m. New York time. 

In commodities, Brent crude futures have fallen 3% to around $99 a barrel while WTI crude oil futures, down nearly 4%, support European bonds as France proposed developed nations release strategic reserves to ease surging prices at the pump. Precious metals are heading higher while Bitcoin has added 2%.

Today's US economic data slate also includes August factory orders 10 a.m. Fed speaker slate includes Dallas’s Logan (10 a.m.) and Chicago’s Goolsbee (12 p.m.)

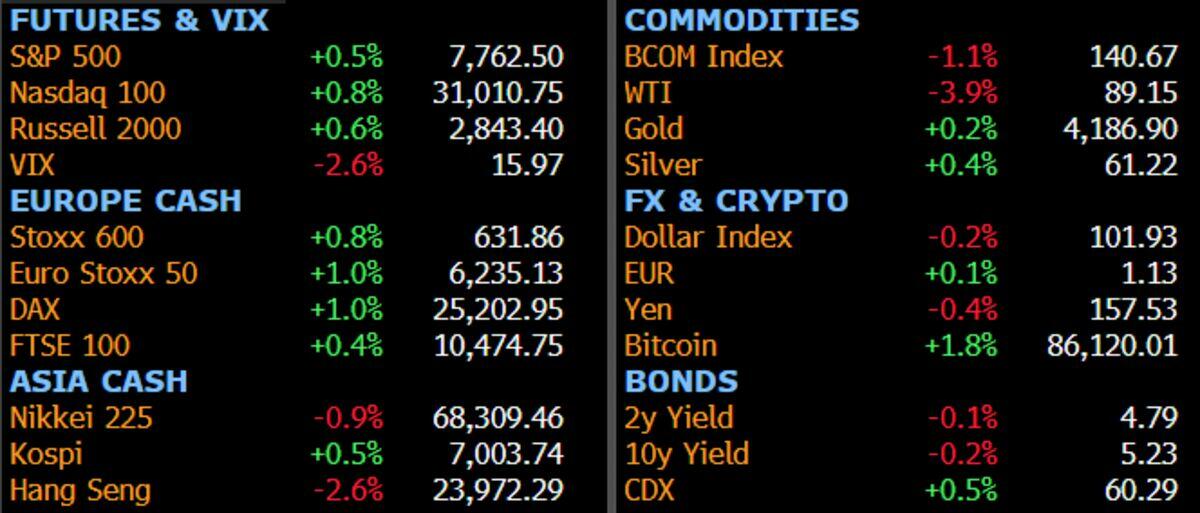
Market Snapshot

Top Overnight News

  • Iran is preparing a broader and more forceful response if the United States resumes large-scale military attacks, sources said, while continuing a diplomatic push that Iranian officials privately see as unlikely to succeed. RTRS
  • Vladimir Putin has instructed his military leaders to abandon the rules of war, prompting a steep increase in strikes on civilian targets amid a major push to regain the advantage in the conflict, according to intelligence intercepted by Kyiv. FT
  • Governments around the world are running out of room to shield consumers from higher energy prices resulting from the Iran war and other crises, with fuel subsidies potentially costing more than $1 trillion this year, a United Nations study found. BBG
  • World food prices rose in September, as transportation disruptions and weather concerns limited supplies and lifted prices for several crop-based commodities, the United Nations’ Food and Agriculture Organization said. WSJ
  • Amazon’s exploring a deal to shift about $8 billion of high-end Nvidia chips into a sale-leaseback SPV vehicle backed by outside investors to help strengthen its balance sheet. FT
  • European countries are in crisis talks over the release of diesel stocks, as the US threatens them with a diesel export ban unless they release strategic reserves of the oil product. FT
  • Tokyo’s key inflation gauge rose sharply as the effects of some temporary government measures faded, backing the Bank of Japan’s stance on continuing to raise the benchmark rate after authorities accelerated the pace of policy normalization. BBG
  • Eurozone CPI for Sept ran hot on the headline (+3.8% vs. the Street +3.7% and vs. +3.2% in Aug) and was inline on core (+2.5% vs. +2.4% in Aug). BBG
  • Trump posted "Republicans in the Senate have to get moving on what I call the “No More Changing of Clocks Act,” officially known as The Sunshine Protection Act".
  • Goldman estimates nonfarm payrolls rose by 80k in September, slightly below consensus of +88k. On the positive side, the level of layoffs remains low and big data indicators of job growth picked up sequentially. On the negative side, September payroll growth has tended to underperform its recent trend when Labor Day is later in the month—like it was this year—and last month’s sharp increase in nonfarm payrolls was boosted by outsized increases in leisure and hospitality and local educational services payrolls that we do not expect to repeat. GS Research
  • BofA Flow Show (w/e 30th September): USD 18.8bln to bonds, 15.8bln to stocks, 0.9bln to crypto, 0.7bln to gold, 118.0bln from cash on quarter-end; Bull and Bear indicator 8.8 (prev. 9.3).

A more detailed look at global markets courtesy of Newsquawk

APAC stocks traded mixed following the ultimately choppy performance stateside as oil prices climbed, yields pulled back, and participants digested a slew of data, while all eyes turn to the looming NFP report. ASX 200 mildly gained, with the index led by strength in tech and energy, albeit with further upside capped amid a lack of fresh catalysts and with real estate and healthcare at the other end of the spectrum. Nikkei 225 retreated as participants digested the latest data releases, including a surprise uptick in the Unemployment Rate and the hotter-than-expected Tokyo CPI data, which was said to be driven by an unwinding of price suppression effects from targeted government subsidies. KOSPI traded indecisively following the somewhat mixed South Korean CPI data, in which the Y/Y reading slowed to 2.9% from 3.1%, as expected, but remained above the central bank's 2% target. Hang Seng underperformed on return from the holiday closure, with Stock Connect trade remaining shut owing to the week-long closure in the mainland, while pressure was seen in auto names following monthly sales updates and with casino stocks in the red after Macau casino revenue declined last month.

Top Asian News

  • Japanese Economy Minister Kiuchi said Japan is no longer in deflation, so there is no need for excessively loose monetary policy that favours higher inflation, while he added that the Takaichi administration's policy is different from reflationary policy that aims to pull Japan out of deflation, and is different from Abenomics in that it seeks to achieve both a strong economy and fiscal discipline and focuses on boosting Japan's supply capabilities.
  • Japanese Tokyo Core CPI (Sep YY) 2.7% vs. Exp. 2.4% (Prev. 1.8%).
  • Japanese Tokyo CPI (Sep YY) 2.7% vs. Exp. 2.5% (Prev. 1.9%).
  • Japanese Tokyo CPI Ex Food and Energy (Sep YY) 3.0% vs. Exp. 2.5% (Prev. 2.0%).
  • South Korean CPI (Sep YY) 2.9% vs. Exp. 2.9% (Prev. 3.1%).
  • South Korean CPI (Sep MM) 0.3% vs. Exp. 0.4% (Prev. 0.2%).

European bourses (STOXX 600 +0.9%) are firmer across the board as they pare back some of Thursday's losses. A pullback in energy prices seems to be supporting equities, with recent Reuters reporting that France is proposing to release 50mln barrels of diesel from Europe and 50mln barrels of crude oil across IEA members, further weighing on the crude complex. Sectors highlight the clear positive bias. Tech leads sectors higher, with Basic Resources and Travel & Leisure following suit, while Health Care is the sector laggard.

Top European News

  • BoE Decision Maker Panel (Sep): Year-ahead CPI inflation expectations 3.1% (prev. 3.1%), Three-year-ahead CPI inflation expectations 2.8% (prev. 2.8%), expected wage growth remained at 3.4%.
  • UK PM Burnham is reportedly leaving the door open to a snap general election next year, according to The i Paper.
  • Moody's said France's ability to tackle key policy difficulties despite political fragmentation is a key factor for the resolution of the negative outlook.
  • European HICP (Sep YY) 3.8% vs. Exp. 3.6% (Prev. 3.2%); Services 3.2% (prev. 3%).
  • European HICP (Sep MM) 0.6% (Prev. 0.4%).
  • European Core HICP (Sep YY) 2.2% (prev. 2.1%).
  • European HICP Ex Food, Energy & Tobacco (Sep YY) 2.5% vs. Exp. 2.5% (Prev. 2.4%).

FX

  • G10s are broadly firmer against the USD, which has been pressured alongside pressure yields and pressure in the energy complex. That was facilitated by reports that France has proposed plans to release 50mln barrels of diesel from Europe (vs the US request of 120mln over 180 days), and perhaps more pertinently 50mln barrels of crude oil across IEA members – this would include the US.
  • Given the recent pressure in yields, the index is under mild pressure this morning and currently holds towards the lower end of a 101.79 to 102.13 range – but still around the prior day’s peak. A material bout of pressure for the USD would likely require significant progress between US-Iran and/or confirmation of a crude stock release. Bar that, the index will likely trade tentatively around the current range as markets await US NFP later today. The US economy is expected to add 90k nonfarm payrolls in September. Analysts note that the August data, where 162k payroll additions were reported, may have been subject to favourable seasonal adjustments, and will be watching to see if the data is revised lower in September. The unemployment rate is expected to hold at 4.1%, an expectation supported by the Chicago Fed’s flash real-time unemployment rate forecast. (A full preview can be found in the Newsquawk Research Suite).
  • CHF is the outperformer across G10s this morning, extending on recent gains. There appears to be a bit of an unwind of the recent carry trade that the CHF was subject to, with net positioning of long-shorts at c. -16.45k over the past 3 months. Further helping is some haven-related demand stemming from the French fiscal situation.
  • Elsewhere, JPY also holds towards the top of the G10 pile, also buoyed by the yield situation. Domestically, Tokyo CPI accelerated in September, and broadly topped expectations. A report which will no doubt boost calls for the BoJ to hike; it seems like the BoJ is now dealing with waning sentiment across Japanese businesses (evidenced in the latest Tankan survey), and rising inflation in a key leading indicator.
  • EUR is a touch firmer this morning, with focus ultimately on the region’s inflation report. Headline Y/Y printed at 3.8% (exp. 3.6%, prev. 3.2%), and Services also rose from the prior. Pertinently, Core HICP moved only a touch higher to 2.2% (prev. 2.1%), which will be welcomed for policymakers, since there is still little evidence of second-round effects. Nonetheless, woes of rising inflation remain – and this data will only further cement calls for another hike later this year

Fixed Income

  • A modestly firmer start to the day has extended into one of marked gains across EGBs and Gilts, with the bulk of the move following a constructive report on energy supplies.
  • However, while a touch firmer, USTs have not really budged from the unchanged mark, into an afternoon dominated by the September NFP report. In brief, the headline is seen at 90k while the August figure of 162k could be subject to a downward revision after potential distortion from seasonal adjustments. For the Fed, the data isn’t expected to have a significant impact as long as it doesn’t change the broad description of a stable and close to full employment labour market, with inflation very much the focus point.
  • Back in Europe, Bunds peaked at 121.37, notching a new high for the week and on track to close the week out with gains of c. 150 ticks (100 of that is from today, at the time of writing), the first positive weekly return since August. While the reported energy stockpile releases will be welcome in the immediacy, it does not change the US-Iran picture, supply risk through Hormuz and the usage of stockpiles now could have a knock on effect during winter. Though, the El Nino will see warmer weather may push any cold spell to later in the season, potentially giving the region some stockpile breathing room.
  • EGBs generally trade with the above. For France, OATs hit a 108.76 peak, firmer by 36 ticks at best, but at the lower-end of the WTD 108.02-110.36 band, after the poorly received draft budget. This morning, Moody’s updated on the draft plan and highlighted the clear fiscal and political risks facing France, points that dominate thinking in the French bond space. Reflecting this, the OAT-Bund 10yr yield spread peaked at 146bps this morning, vs 110bps at the start of the week. No real move to the September Flash HICP, with energy once again driving the upside but no overt signs of second round effects as the core components remain at acceptable levels; though, the absolute level means further tightening remains a valid call.
  • Gilts also benefit from the energy moves. At an 84.81 session high, firmer by c. 100 ticks at best and set to end the week at highs.
  • Australia sells AUD 1.2bln 4.50% April 2033 bonds: b/c 3.00x, avg. yield 5.108%.

Commodities

  • WTI Nov and Brent Dec futures are sharply lower after yesterday’s rally, with pressure intensifying during the European morning on reports France proposed releasing 50mln bbls of diesel from Europe alongside 50mln bbls of crude across IEA members. The proposal would be conditional on a US commitment not to impose a unilateral diesel export ban and follows Washington’s request for major European countries to release diesel reserves. WTI fell from USD 90.80/bbl to USD 89.88/bbl on the report, while Brent fell from USD 100.90/bbl to USD 99.76/bbl. European gasoil futures fell over 4% on the reports. Prior to this, the complex was already under pressure despite continued US-Iran tensions, with Trump reportedly telling aides he expects bombing of Iran to resume in November and the Pentagon sending a third carrier strike group to the region. WTI and Brent currently trades at session lows, with the former briefly falling below the USD 89/bbl mark while the latter touches the USD 99/bbl handle.
  • Dutch TTF is also softer despite continued European energy-security concerns heading into winter, with attention dominated by discussions around coordinated energy-stock releases. TTF trades towards the lower end of a EUR 71.05-73.61/MWh range.
  • Precious metals are firmer ahead of US NFP, helped by the pullback in oil prices and some reprieve in global yields. Spot gold trades towards the upper end of a USD 4,134-4,197/oz range, having recovered further from yesterday’s USD 4,139/oz low, while spot silver is similarly firmer within a USD 60.22-61.56/oz range.
  • Base metals were subdued overnight with mainland China still absent for the week-long holiday, but have since clambered into the green on the aforementioned pullback in energy and subsequent boost to risk. 3M LME copper trades in a USD 14,243.03- 14,380.38/t range at the time of writing.
  • EU countries discussed a French proposal to release 50mln barrels of diesel from Europe and 50mln barrels of crude oil across IEA members, in response to the US' threat of a diesel export ban, Reuters reported citing sources. The report added that any agreement on further stock releases should include a US commitment to avoid a unilateral diesel export ban.
  • France's Elysee said President Macron spoke with US President Trump about energy and fuel prices.
  • European Commissioner Jorgensen said the EU is discussing with all IEA members, not only the US, when it is time to release diesel stocks.
  • Ukrainian Agricultural Minister said that the area planted to winter wheat in 2027 could decline about 17%.

Trade/Tariffs

  • US President Trump said the trade deficit with China has dropped to the lowest in 44 years and that he gets along great with Chinese President Xi, while he added that China used to rip the US badly and that Canada is ripping the US badly.

Central Banks

  • Fed's Logan (2026 voter) said the policy rate needs to increase an additional 50bps or more and that without higher rates, inflation will not get to the 2% goal, while she added that policy is not sufficiently restrictive and needs to become modestly tighter. Logan said price stability must be restored and at a minimum, several further rate hikes would reverse last autumn’s cuts. She also stated that it remains uncertain how high the policy rate must go to bring inflation back towards 2%.
  • Fed's Bowman (voter) said she sees no urgent need for more rate moves this year, while she touted benefits of a Fed capital plan tied to treasuries.
  • ECB's Rehn told Econostream that ECB forecasts are facing extremely high and widespread uncertainty and that the energy surge is nearer to the adverse scenario. Rehn added that one uncertainty is that market sentiment toward AI could reverse suddenly, while higher long-term rates will slow economic growth and reduce the pass-through of energy shocks to prices and wages.

Geopolitics: Iran

  • US President Trump reiterated that Iran will never have a nuclear weapon and has no navy or army, while he stated that Iran has not been able to get one of its vessels through the Strait of Hormuz for months. Trump also said huge quantities of oil have passed through the Strait of Hormuz and the US is taking out millions of barrels of oil, claiming that in some cases, it is more than before the war.
  • US President Trump said the Iran war will be ending soon, one way or the other, and that it looks like Iran was involved in the UK base incident. Trump warned that Iran will be hit very hard if it is behind the copilot who tried to crash a flight to Israel, while he separately commented that based on what he heard, Iran was connected to the attempted attack on the plane.
  • The Iranian National Security Commission said that Iranian management of the Strait of Hormuz will be applied. Ships to Zionist or hostile regimes will not be able to pass through the Strait, others will have to get permission. Bill is queued for parliament.
  • IRGC said three UAE-linked tankers attacked recently in the Strait of Hormuz were on the PGWA's non-compliance list, and had transited the Strait repeatedly over the past two months.
  • Saudi‑led coalition intercepted and destroyed ballistic missiles launched by Yemeni Houthis towards Khamis Mushait.

Geopolitics: Other

  • Russia's Kremlin said Russia will continue operations to completely stop supply of weapons and fuel for the Ukrainian military via the Black Sea.
  • Russia's Defence Ministry said they struck a vessel in the Black Sea and an industrial production complex at the port of Izmail in Ukraine’s Odessa region overnight, according to IFX.
  • South Korean President Lee said they will take additional measures if Ukraine continues to deny the agreement on North Korean prisoners of war repatriation, while he called on Ukraine to acknowledge the agreement and apologise.

US Event Calendar


DB's Jim Reid concludes the overnight wrap

Markets stumbled yesterday as we began Q4, with mounting signs of financial stress focused on Europe. In fact, the daily moves were reminiscent of the Euro crisis in many respects, with sovereign contagion a big talking point. For instance, the Franco-German 10yr spread (+13.9bps) saw its biggest daily jump since March 2020 at the height of the Covid turmoil, the same day that ECB President Lagarde said “we are not here to close spreads”. And over in Italy, the 10yr spread to bunds (+15.9bps) saw its biggest daily jump since July 2022, the day that the ECB delivered their first rate hike in over a decade. Moreover, the impact cascaded across different asset classes, with the Euro (-0.76%) posting its worst day against the dollar since June, whilst the STOXX Banks index (-3.90%) had its worst day since March.

The interesting thing about yesterday’s moves was that there wasn’t a single catalyst driving them. Initially, the day began with a genuinely global bond selloff, driven by higher oil prices and a hawkish batch of US data. Indeed, the 10yr US Treasury yield hit its highest intraday level since 2002, at 5.34%. But as the session went on, it then morphed into a classic risk-off move, with bunds and US Treasuries starting to rally, whilst others like French OATs and Italian BTPs sold off. That went hand in hand with mounting stress for risk assets too, particularly in the affected markets. So France’s CAC 40 (-1.62%) hit a 6-month low, and Italy’s FTSE MIB Index (-2.21%) hit a 3-month low, underperforming the Europe-wide STOXX 600 (-1.30%). French banks came under pressure, with Société Générale (-5.00%), Crédit Agricole (-3.70%) and BNP Paribas (-3.64%) losing significant ground, and this was broadly in line with the broader STOXX Banks (-3.90%) as contagion spread through European markets. Credit took a big hit as well, with European HY spreads (+18bps) seeing their worst session since the start of the Iran war, reaching their widest level in six months.

That financial stress led to growing doubt whether central banks like the ECB could hike rates as aggressively as thought. After all, tighter financial conditions would do some of the work for them in bringing down inflation, and the selloff also raised doubts as to whether the economy could cope with another hike. So when it came to ECB pricing, the number of further hikes priced by December’s meeting fell -6.1bps on the day to 23.5bps. Or in other words, another ECB hike is no longer fully priced by year-end. So that led to a huge collapse in front-end German yields, with the 2yr German yield (-14.2bps) falling back to 3.07%, its biggest drop since April. Meanwhile, the 10yr bund yield (-7.8bps) also fell back to 3.51%.

For Europe, those issues were exacerbated yesterday by the latest rise in energy prices, which hit the continent more given it’s an energy importer (unlike the US nowadays). So Brent crude was up +4.37% by the close to $102.31/bbl, whilst European natural gas futures were also up +2.18%. In part, that followed comments from President Trump, who said in a Time interview that it was “possible” he would resume bombing Iran once the midterm elections had passed. In addition, there were further reports about US military deployments in the Middle East, with Bloomberg reporting the US was sending an additional aircraft carrier, along with 10,000 sailors and Marines to the Persian Gulf. So coupled with the absence of any progress towards a deal, this led to growing pessimism that free shipping via the Strait of Hormuz would resume anytime soon. And in turn, that pushed longer-dated oil futures higher once again, with the June 2027 Brent future up to a new high yesterday of $88.03/bbl by the close.

Whilst European assets struggled yesterday, there was a very different tone in the US. Initially, it looked like Treasury yields would hit new highs, and we did see the 10yr yield hit its highest intraday level since 2002 yesterday, at 5.34%. But that turned in the afternoon, with the 10yr yield ultimately down -4.4bps on the day to 5.24%. Moreover, US equities recovered from their earlier sell-off, with the S&P 500 (+0.19%) ending a run of three consecutive declines, whilst futures for the index are up another +0.27% this morning.

In part, those moves were aided by more dovish commentary from FOMC officials, which added to the sense that officials weren’t in a rush to hike again. So that meant the 2yr Treasury yield (-9.6bps) saw its biggest daily decline since July, closing at 4.79%. Those comments included Vice Chair Jefferson’s, who suggested that deciding on future rate hikes “may take more time”, while Governor Bowman (one of the more dovish voices on the FOMC) said she did not “currently see an urgent need for further action”. That left an October Fed hike just 30% priced by yesterday’s close, down from 37% on Wednesday and 70% on Monday before NY Fed President Williams similarly signalled no urgency for the next hike.

What was also striking was how the financial stress and the Fed commentary outweighed a hawkish batch of US data, which initially put upward pressure on Treasury yields earlier in the day. Collectively, that data painted a picture of ongoing resilience in the US economy, alongside plenty of price pressures, so it was very much in line with the prints of recent weeks. Among others, the weekly initial jobless claims fell to a 10-week low of 197k in the week ending September 26 (vs. 200k expected). Then the continuing claims for the previous week fell to a three-and-a-half-year low of 1.701m (vs. 1.725m expected). And just 90 minutes after that, the ISM manufacturing print came in at 54.5 in September (vs. 55.0 expected), but the prices paid subcomponent surged more than expected to 77.9 (vs. 73.0 expected) and the employment component rose more than anticipated to 52.7 (vs. 52.0 expected). So initially that drove yields higher, but the wider risk-off move then saw that reverse course.

With all that in mind, today’s focus will now turn to the US jobs report for September, which is out at 13:30 London time. Clearly, the monthly jobs reports are always a macro highlight, but this is an important one, as the continued data resilience has been a huge factor supporting US risk assets, and it’s also given the Fed space to start hiking rates. Indeed, last month’s report was very strong, with payrolls up +162k alongside positive revisions to the previous two months. So that added to the hawkish momentum leading up to the Fed’s September meeting a couple of weeks later. This time around, our US economists are expecting payrolls to come in at +60k, with the unemployment rate holding steady at 4.1%.

Ahead of that jobs report, Asian markets have also generally lost ground overnight, with the Hang Seng (-2.64%) sharply lower as it returns after the previous day’s holiday. Then in Japan, the Nikkei is down -0.94%, which comes as the Tokyo CPI data for September was faster than expected. That showed headline CPI rising to +2.7% (vs. +2.5% expected), whilst the core-core measure reached its fastest in over a year, at +3.0% (vs. +2.5% expected). Otherwise in South Korea, the KOSPI is up +0.26% this morning, and the country’s CPI eased to +2.9% in September, in line with expectations. In mainland China, markets are still closed for a holiday.

Looking at the day ahead now, the data highlights will include the US jobs report for September, and the Euro Area flash CPI print for September. From central banks, we’ll hear from the Fed’s Logan, and the ECB’s Moulin, Cipollone, Rehn, Sleijpen, Vujcic and Nagel.

Tyler Durden Fri, 10/02/2026 - 08:27

UK Arrests British Iranian Dual National Over Security Incident Near Airbase

UK Arrests British Iranian Dual National Over Security Incident Near Airbase

Authored by Ryan Morgan via The Epoch Times,

Authorities in the UK have arrested a dual national of the UK and Iran in connection with a security incident near the Fairford Royal Air Force base in Gloucestershire, England, on Sept. 27.

In an Oct. 1 update, the UK's Counter Terrorism Policing identified the arrested British Iranian dual national as a 25-year-old man. He was arrested on suspicion of preparing to commit terrorist acts.

Counter Terrorism Policing also confirmed searches at a pair of properties in connection with the ongoing investigation into the RAF Fairford security scare.

RAF Fairford hosts U.S. Air Force elements and is a key forward operating location for U.S. bombers such as the B-52 Stratofortress and B-1B Lancer.

In a Sept. 30 interview with the BBC, British Prime Minister Andy Burnham said there are strong indications the recent security incident near RAF Fairford is linked to Iran.

UK Senior National Coordinator for Counter Terrorism Policing Vicki Evans said on Oct. 1: "The investigation into circumstances surrounding events in Gloucestershire is hugely complex, and our specialist teams are interrogating multiple lines of enquiry.

"As we've made clear, we're looking at all possible angles - including possible foreign state involvement."

Authorities initially arrested five men in connection with the security incident near RAF Fairford but released them on police bail soon after. In their latest update, Counter Terrorism Policing said these five individuals remain on bail.

In a previous update on the investigation, Counter Terrorism Policing said it arrested the first five men on suspicion of committing offenses under the UK's Explosives Act. After searching multiple vehicles in connection with the Sept. 27 security incident, authorities said they found no explosive devices but did recover some gasoline.

Tehran has continued to deny any involvement in the incident.

"You're barking up the wrong tree," Iranian Foreign Minister Abbas Araghchi said on Sept. 30.

On Oct. 1, Iran's Ministry of Foreign Affairs said it had summoned British Ambassador to Iran Hugo Shorter to reiterate its criticism of Burnham's recent comments about the ongoing investigation, which the ministry described as "baseless and ridiculous."

"The British ambassador emphasized that he will convey the Islamic Republic of Iran's protest to London," the Iranian Foreign Ministry said in a press statement.

In July, Iran's Islamic Revolutionary Guard Corps said it would treat any bases used to launch strikes on Iranian territory as legitimate targets for retaliation.

The British government has authorized U.S. forces to use some of its bases, including RAF Fairford, to launch strikes on Iranian missile sites that have targeted international shipping.

Reuters contributed to this report.

Tyler Durden Fri, 10/02/2026 - 08:05

How Jamaica Continues to Ruin Its Brand With Reparations

How Jamaica Continues to Ruin Its Brand With Reparations

Authored by Lipton Matthews via American Greatness,

Sentiment and economic development are not the same currency, and confusing them costs a small country more than it can afford.

Washington has quietly begun cancelling the visas of prominent Jamaican officials, and the reason is no mystery. American law enforcement partners have grown frustrated with how Kingston handled a cocaine scandal inside its own police force. Operatives cited by the Sunday Gleaner on September 6, 2026, say the revocations "include public officials within the government and the security forces" and that the cancellations amount to a deliberate signal of Washington's displeasure with the affair.

At the center of that affair sits the now-disbanded Counter Terrorism and Organized Crime division, known as C-TOC. U.S. authorities suspect that police officers assigned to the unit significantly understated the amount of cocaine they confiscated during an operation in Green Island, Hanover, in 2025. An internal audit later turned up two illegal parcels of cocaine sitting inside C-TOC's own storage facilities, a discovery that triggered the unit's collapse. Commissioner Kevin Blake transferred more than 40 officers out and effectively dissolved the eleven-year-old division. A police inspector who was attached to C-TOC was arrested and charged after cocaine was allegedly found in his private vehicle, and that arrest is what set the audit in motion. Investigators have since expanded their probe to nearly a dozen high-ranking police and former army personnel, and searches have been carried out at the homes of senior officers once tied to the unit. Whatever the eventual findings, the optics could hardly be worse for a country trying to convince the world it can police its own coastline.

Add to that a second embarrassment, smaller in scale but telling in what it says about institutional discipline. Thousands of Jamaican students failed to show up for this year's regional CXC examinations, leaving taxpayers facing a bill that could reach several million dollars for mathematics and English papers that were subsidized but never sat. Widen the lens to every subject the government helps fund, and the waste grows larger still. A country running a security deficit and an exam-attendance deficit in the same news cycle is not projecting the image of a nation on the rise.

None of this means Jamaica has stood still. Quite the opposite. Police intelligence now counts fewer than one hundred active gangs, down from a peak of 350 in 2016, a decline the government credits to sustained, intelligence-led operations rather than one-off sweeps. In July, Prime Minister Andrew Holness traveled to San Diego to accept the Esri President's Award on behalf of the Jamaican government, Esri's highest honor and one personally selected by the company's founder. The award recognized Jamaica's use of geographic information systems to build an integrated national geospatial infrastructure, the same system that helped coordinate the country's drone and emergency response during Hurricane Melissa. Esri is the dominant name in GIS software and location intelligence worldwide, and having a small island nation singled out among its global user base is a genuine credential, not a participation trophy.

The prime minister understands that reputation is a strategic asset. His government has already engaged an international consulting firm to refresh what he calls Brand Jamaica, hoping to push the country's image beyond sun, sea and sand toward safety, sustainability, and technological competence. That is the correct instinct. So it is worth asking why, in the same season that Jamaica is trying to sell itself as a serious, forward-looking economy, its government sent a delegation to London to petition King Charles over slavery reparations.

The petition is a frivolous use of a developing country's time and money. It asks the king, as Jamaica's head of state, to refer three questions about the transatlantic slave trade to the Judicial Committee of the Privy Council, the island's highest court of appeal, in the hope that royal involvement lends weight to a claim that has been dismissed and re-dismissed for over a decade. Culture Minister Olivia Grange, who led the delegation, has called it a milestone moment built on five years of legal groundwork. Five years spent building a case that a man who once sat on the Privy Council itself calls empty. Lord Sumption, the former Supreme Court justice, told the BBC that Jamaica was relying on a Britain that has grown "riven by self-doubt and guilt" and dismissed the entire legal push as, in his words, "a bit of nonsense." Reading the public commentary that has followed online, much of it agrees with him, and much of it is far less polite. People say Jamaica should focus on its drug problem instead of chasing the Crown for money, or they make the condescending suggestion that the country is too poor to do anything but beg. That is the return on investment this petition has bought: ridicule, not investments.

None of that petitioning does anything to make Jamaica look like a place where an investor should park capital or where a skilled professional should build a career. Sentiment and economic development are not the same currency, and confusing them costs a small country more than it can afford. Consider the alternative use of that same delegation's time and budget. Imagine a Jamaican mission to London built around studying the city's technology sector instead, meeting with founders, venture investors, and policymakers who have made Britain's capital one of Europe's leading tech hubs. That kind of visit signals ambition rather than grievance. It tells the world Jamaica wants a seat at tomorrow's table, not compensation for yesterday's wrongs.

Austria offers a useful model here. It is a considerably wealthier country than Jamaica, yet it still felt the need to station a dedicated tech ambassador in Silicon Valley, first appointed in 2020 under the Open Austria initiative, specifically to build relationships with the frontier companies shaping the next economy. Jamaica has no equivalent presence anywhere near San Francisco or London's tech corridors. If a country as developed as Austria judges that kind of outreach as essential, a developing nation with Jamaica's ambitions should judge it as extremely important.

There is precedent for this kind of strategic humility. When Japan sent the Iwakura Mission to Western Europe and North America in the 1870s, its purpose was not to re-litigate old grievances with the powers it had once been forced to deal with on unequal terms. It was to learn, deliberately and systematically, how industrializing nations built their institutions, their industries, and their infrastructure, then bring that knowledge home. The mission helped lay the groundwork for Japan's transformation into a global industrial power within a generation. Jamaica does not lack the talent or the imagination to attempt something similar. What it currently lacks is the discipline to choose that path over the more emotionally satisfying one.

Sentimental projects carry a real appeal. They offer a sense of moral vindication that a spreadsheet never will. But feeling righteous and being prosperous are not the same achievement, and a country of Jamaica's size cannot afford to spend its limited diplomatic capital chasing the former while starving the latter. The episode also exposed the practical limitations of the campaign: Jamaican officials spent taxpayer money traveling to London with a formal petition on reparations, yet King Charles declined to meet them. Royal officials indicated that his schedule made a meeting impractical while also stressing that the King does not have the constitutional authority to make a decision on reparations himself. Any such decision would ultimately have to be made by the British government, rather than the monarch.

If the delegation had instead been traveling to London to learn from one of the world's leading technology hubs and to meet entrepreneurs, investors, and technology companies, the country could at least have come away with something tangible. It could have generated favorable international press, strengthened business relationships, and helped present Jamaica as an emerging technology player. That would fit far more naturally with the brand of Jamaica that the Prime Minister appears to envision, a modern, ambitious, investment-friendly country positioning itself for growth rather than defining its international identity primarily through historical grievance.

Tyler Durden Fri, 10/02/2026 - 07:20

Nike Plunges On Slashed Outlook As UBS Warns Against Catching A Falling Knife

Nike Plunges On Slashed Outlook As UBS Warns Against Catching A Falling Knife

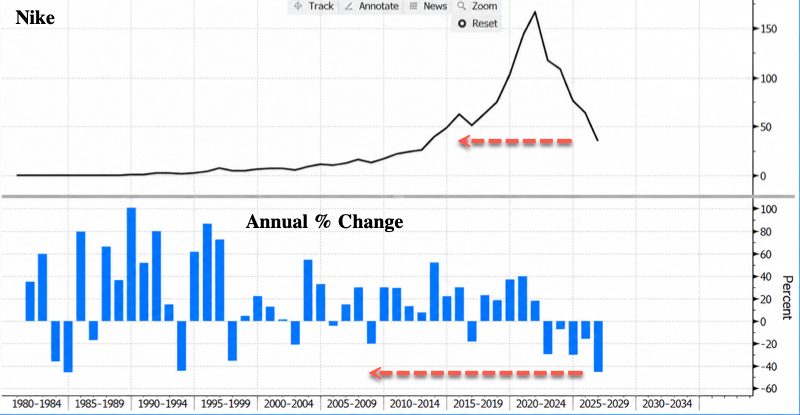
Nike shares are down nearly 10% in pre-market trading in New York after the struggling athletic footwear and apparel company warned its sales slump will deepen and unveiled a restructuring that will eliminate jobs.

As of Thursday's close, year-to-date performance had been absolutely abysmal, with shares down 45%. The extended decline could now put the stock on track for its worst annual loss on record.

The decline follows the sportswear giant's earnings release after hours on Thursday, when it stated that it now expects revenue to decline by a high-single-digit percentage this fiscal year, substantially worse than the 2.4% drop analysts tracked by Bloomberg forecast.

Nike spent years catering to woke culture while neglecting to stay ahead of the industry as competitors ate into its market share. It now plans to fold its Greater China unit into its broader Asia Pacific division and combine Latin America with North America.

This restructuring is expected to deliver $2.5 billion in savings over five years while generating roughly $1 billion in pretax charges.

CEO Elliott Hill wrote in a memo to investors that this restructuring "will require fewer roles over time."

Hill, approaching his third year as CEO, has focused on rebuilding retail relationships and organizing Nike around individual sports.

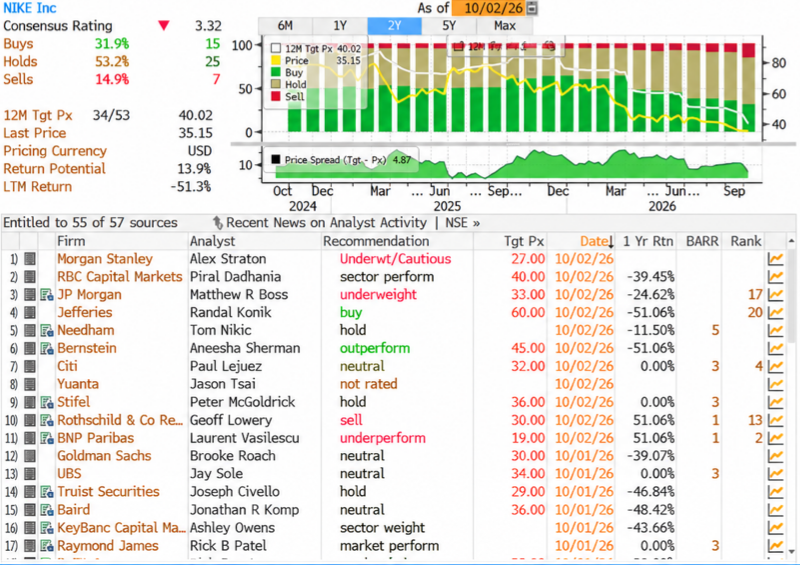
The ugly guidance on Thursday comes after BofA retail analyst Lorraine Hutchinson downgraded the stock last week and warned that its "turnaround is taking longer" than expected.

UBS retail analyst Jay Sole wrote in a note shortly after earnings about "why it's still not time to buy Nike" and maintained a "Neutral" rating on the stock, lowering his 12-month price target to $34 from $42.

Sole explained:

The key downside risk is Nike's downward EPS revision cycle may persist:

The pivotal Nike question remains "Is all the 'bad news' now priced in?" Despite the pullback in Nike's stock price, we still don't see a good entry point. Nike's stock price is still not cheap at ~28x our FY27 EPS estimate, in our view, and this suggests a solid rebound remains priced in. We continue to see a balanced upside/downside skew. The main upside risk is Nike's November Analyst Day convinces the market the stock's downward earnings revision cycle has ended and investors are willing to put a peak multiple on their FY27 EPS outlook. The main downside risk is the rebound takes much longer than the market anticipates and therefore the downward earnings revision cycle may not be over.

We see 3 reasons NKE's downward EPS revision cycle may not be over:

  1. The market may be underestimating the negative impact on unit demand as Nike tries to reduce discounts. Nike's FY27e gross margin likely hits a 20-year low. To drive a gross margin recovery, Nike would have to significantly reduce discounts. We believe the elasticity of demand in this situation could be greater than 1. However, we don't think Nike's -HSD% FY27 revenue guidance incorporates this. We believe the sales guide reflects weak demand, elevated inventory levels and a major China pullback. Thus, we see risk pulling back on promotions drive another big drop in sales in FY28.
  2. The market may be underestimating the negative impact on sales from Nike having to reset its Sportswear and Jordan businesses. Nike brand Sportswear plus Jordan Streetwear equates to roughly 60% percent of NKE revenues. 1Q27 sales in these categories fell at least -LDD% y/y. We believe fashion trend shifts and a lack of brand momentum are hurting Nike in a major way. The risk is Nike can't impact these trends soon and this leads to more pressure well into FY28.
  3. The market may be underestimating the negative impact on margins if sales slow. Nike announced its 3rd big cost adjustment program since 2020. The concern is Nike may not have very many easy cost reductions left to make and will need to ramp up investment in order to grow. If so, more downside revenue surprises could pressure margins more than we and the market expect.

We lower our FY27-FY29 EPS estimates ~4-6%, respectively:

We lower our FY27 and FY28 revenue growth forecasts related to Nike's reset of its Jordan and Greater China businesses. We note Nike mgmt. expects these actions to weigh on revenues over FY27 and into FY28. Additionally, we now anticipate greater fixed cost deleverage driven by our weak topline forecasts. Lastly, we now model a higher share count given lower than expected buybacks during Q1 and expected going forward given our reduced FCF forecasts. This is partially offset by a reduced SG&A forecast given Nike's newly announced Pace cost savings initiative. These factors are the main drivers of the 4-6% reduction in our FY27-FY29 EPS estimates, respectively. Please find much more forecast detail inside.

Valuation: We lower our PT 19% to $34 and remain Neutral:

Our $34 PT is based on 18x our $1.90 FY29 EPS estimate. Our prior was based on 21x our old $2.00 FY29 EPSe. We lower EPS estimates and the P/E used to value NKE given our view fundamental trends in China and Nike's Jordan business are weaker than previously thought. Our multiples analysis indicates a $34 PT puts NKE's valuation in-line with peers in terms of P/E, P/Sales, & FCF yield (Fig. 6). Our DCF analysis also supports a $34 valuation (Fig. 9).

Other Wall Street analysts offered their first take assessments, courtesy of Bloomberg:

Morgan Stanley (underweight, PT $27 from $31)

  • Nike's 1Q print "did little to change" our underweight rating, "with negative EPS revision & valuation de-rating risk remaining intact," analyst Alex Straton says
  • "The Investor Day is the next key catalyst, with our focus on the magnitude of further topline right-sizing"

Guggenheim (buy, PT to $50 from $60)

  • "With yet another downward revision, the questions remain when guidance cuts will represent the band-aid rip versus slow bleed as they continue to debate the path potential stabilization ahead," analyst Simeon Siegel says

Vital Knowledge

  • Analyst Adam Crisafulli says Nike's first-quarter numbers were fine, but the guidance "is pretty ugly"
  • Expectations "were very low" after earlier results from peers Dick's Sporting Goods and JD Sports, but the inability of management to get a handle on the business "is going to grate on investors (and might even start spurring talk about potentially changing the CEO position, even though Hill has only been in the role for ~2 years)."

CFRA (buy, PT $62)

  • "We are disappointed with the results and expected better full-year EPS guidance," writes analyst Zachary Warring
  • Says growth in North America was more than offset by continued deterioration in Greater China and a sharp ongoing decline at Converse

According to Bloomberg data, 15 analysts are "Buy" rated on the stock, another 25 with "Holds," and 7 "Sells." The average 12-month price target is $40. 

UBS Sole makes a great point: the stock is still not at the bottom.  

Tyler Durden Fri, 10/02/2026 - 06:55

London Mosque Pushes Wife-Beating, Throwing Gays Off Tall Buildings

London Mosque Pushes Wife-Beating, Throwing Gays Off Tall Buildings

Authored by Steve Watson via Modernity.news,

A London mosque with charitable status is under investigation for posting sermons that tell husbands to hit disobedient wives and setting out execution methods for gay men, including being thrown from tall buildings.

The lectures were not smuggled out of a private meeting. They sit on the Hackney Islamic Community Centre's own YouTube channel, delivered from the mosque also known as Masjid Daar Al-Hadeeth. The National Secular Society referred the material to the regulator. The Daily Mail published the tapes. Britain's official response is a case file.

The Charity Commission has opened a regulatory compliance case. It has not, so far, taken the charity's status away.

Yasin Munye, described as an ustaadh at the centre, reads in one lecture from Manthumatu al-Kaba'ir, a poem listing what the tradition treats as major sins. One of them, in his words, is "disobeying the husband, leaving the house without his permission, and disobeying the husband when it comes to calling her to bed, when it comes to calling her for intimacy, when she says 'no' without any excuse."

The remedy he sets out is not a row and a solicitor. "Advise her, and boycott her in bed, don't touch her in bed - and discipline them physically as well, by lightly hitting them to show them who is in charge."

If she still refuses, he says husbands "don't have to give her a house anymore." He adds: "If a person has multiple wives, then he doesn't have to stay with her; he can abandon her and stay with the other wife until she becomes obedient again."

The same lecture turns to sex between men. Munye calls it "one of the most evil acts" and "a crime" that sees both participants "executed in the Sharia." On the method, he is specific. "Scholars, they differ on how the execution occurs. Some of them say he is executed through the sword, like every other normal execution. Others say that they are thrown off of a tall building and rocks are thrown after that on top of them."

The National Secular Society says the videos were published on the charity's YouTube account in 2023. They were still there when campaigners and reporters went looking this week, but have since been made private.

A separate lecture praises a state that still kills people accused of witchcraft. "Sihr (magic) is real, it is true," Munye says. "In Saudi Arabia, they are killed, alhamdulillah (praise be to God), bless that, because a lot of Muslim countries today you don't find this ruling applied. Alhamdulillah, in that country, that punishment is still applied."

A community elder at the same mosque, Abu Sa'ad Muhammad Al-Iraqi, treats the British police as the problem. If a husband "is not nice to you and mistreats you," he says, "there is a way: you bring your family, speak to his family, to teach him a lesson. But you have to give his right, otherwise don't be his wife."

He goes on: "Women think these days, our sisters think, that you only be kind to him if he's been kind back... it doesn't work like that." Then the line that should have ended the tax exemption on the spot. "In another country they can't do that, they won't. But it is an unfortunate reality of this country that they turn wife against husband. They know if you slap them once, they'll call the police for you. They don't fear Allah."

The centre has been a registered charity since 2006. It re-registered as a charitable incorporated organisation in April, a change that separates trustees from the charity's debts and lets it hold property under charity law. Its objects include advancing the Islamic faith. In the year to March 2025 it took in £191,097, almost £155,000 of it in donations, and paid no tax on any of it.

Megan Manson, head of campaigns at the National Secular Society, called the renewal alarming. The charity, she said, has hosted "lectures which promote violence against women, say women cannot refuse their husbands sex, and condone the death penalty for gay men and those accused of 'witchcraft'."

"Hackney Islamic Community Centre is just one of many charities promoting misogyny, homophobia and other harmful ideologies through the charitable purpose of 'the advancement of religion'," she said. "This charitable purpose must be urgently reviewed. It is evidently facilitating the advancement of ideas which, far from benefiting the public, could fuel discrimination, division and abuse."

The Charity Commission provided a stock reply, noting that the commission "has clear expectations that all charities, regardless of their purpose, must operate for the public benefit and provide a safe and trusted environment for all."

It added that concerns had been raised "about alleged sermons and social media content linked to Hackney Islamic Community Centre and we have opened a regulatory compliance case to further assess these. This will determine any next steps."

A compliance case is not a statutory inquiry. Earlier this year a preacher at Hatch End Islamic Centre, Ahmed Shah, told worshippers it was mandatory for women to do the housework and serve their husbands. The sermon came down. The commission offered advice and guidance, but the centre's charity status remained in place.

None of this arrives in a vacuum. In July the Home Office was still handing Skilled Worker sponsorship licences to Islamic bookshops stocking jihad texts and a guide that includes wife-beating. Reform MP Lee Anderson called it "a perfect illustration of 14 years of Tory failure: rather than doctors and engineers, we brought in staff for Islamic shops selling books on jihad."

In August, West Midlands Police invited non-Muslim staff to fast for a day in Ramadan as solidarity. Shadow justice secretary Nick Timothy said the police "should be a national force for all of us, observing the same standards regardless of creed," and that encouraging non-Muslim staff to observe Ramadan was "wholly inappropriate."

The same month a retired officer, Stephen Gray, 65, was convicted under the Communications Act for resharing a bacon meme about Islam. He was fined more than £1,000. "I made a joke, an ironic joke, about Islam. That is all it was at the end of the day. A joke," he said. Lord Young of the Free Speech Union called it "a new low. No one making a similar joke about Jesus would face prosecution."

Last month, Barnet Hill Academy in West Hendon moved onto the state payroll as a voluntary-aided Islamic primary, with a compulsory white hijab for girls from Year 3. Stephen Evans of the National Secular Society said it was "appalling that taxpayers are being asked to fund a school that forces girls as young as seven to wear the hijab."

A recent YouGov survey for King's College London found 34 per cent of British adults believe London already has no-go areas where Sharia dominates and non-Muslims cannot enter.

On the one hand, a former police officer can be fined for a joke about Islam. On the other, a Islamic preacher can tell men to strike their wives, abandon them for a second wife, and advocate for gay men being thrown from buildings, yet retain charity status.

Is there a clearer example of a two-tier state? Mock the creed and the courts come for you. Preach beating and killing, and nothing happens.

Tyler Durden Fri, 10/02/2026 - 06:30

UK Officials Are Keeping A List Of Brits Who Question Government Policy

UK Officials Are Keeping A List Of Brits Who Question Government Policy

Authored by Steve Watson via Modernity.news,

The British state is compiling a list of people who criticise its own counter-terror programme. Ordinary X and Reddit users who questioned Prevent training, flagged a one-sided focus on the "far Right," or simply criticised it have had their posts logged, stored and "investigated" by a Home Office-linked unit most of them have never heard of.

Officials spent more than a year trying to keep that database secret. They only released it after an appeal to the Information Commissioner's Office. The public was never told their feeds were being trawled.

The Standards and Compliance Unit, or StaCU, was set up in February 2024 as an "opaque" body to handle complaints about Prevent, the safeguarding scheme sold as a way to stop people becoming terrorists. Documents obtained by The Metro and released by Rights & Security International show StaCU did more than wait for formal complaints.

Between March 2024 and February 2025 it made 77 "observations" of critical online comments, most of them from X, with others from Reddit and even articles in the Guardian and the Telegraph.

Jacob Smith, Freedom of Expression and Belief Team Leader at Rights & Security International, fought for a year to force the Home Office to publish the material.

"It is shocking that the government has been trawling X and Reddit to find out who has been critiquing Prevent - and then storing that information," he said. "You should be allowed to criticise government policy without being put on a list."

He added: "People should be able to express their views on social media without that being catalogued in government databases."

Many of those logged, he said, had posted without thinking "that the government might be looking at their feed and taking that data. It is in an almost private setting."

His conclusion was blunt: "It's a stark reminder that, in the government's eyes, anything you share online is fair game and could go into a file forever."

A large share of the logged posts accused Prevent training of treating the "far Right" as the main threat while skating over Islamist extremism.

One X user was recorded after calling the training "complete bullshit." They wrote: "Anyone's who done the prevent training knows it only talks about the far Right. Islam extremism isn't even mentioned."

Another poster said they "sat through Prevent training at work ... and the narrative was very much that the far Right is the biggest threat." They added: "I kid you not!"

StaCU says it tries to independently verify claims about Prevent. It managed that for only 10 percent of the posts. The unit's parent body, the Commission for Countering Extremism, sometimes replies in public, inviting the user to submit a formal complaint.

In one case, after a post accused Prevent training of "turning a blind eye to Islam," the Commission wrote: "Hello, we process and investigate complaints about Prevent and are interested in finding out more about the training referenced above. Please feel free to DM us, tweet us back, or make a formal complaint using this link."

What that reply does not say is that the user's post has already been stored in an internal government list.

It was not only anonymous accounts. Open Rights Group had a tweet recorded that said: "How data is managed and stored under the Prevent programme lacks transparency."

Sarah Lasoye, the group's Programme Manager for Pre-Crime, told The Metro: "Prevent has expanded far beyond its stated aim of identifying people considered 'vulnerable to radicalisation', and has increasingly been used to justify extensive surveillance."

She added, "It is deeply concerning to see the Prevent duty being used to enable the monitoring of people and organisations simply because they are critical of the programme. That raises serious questions about freedom of expression and the right to dissent and protest."

"There is also a troubling lack of transparency about what happens to the information gathered through this social media monitoring: how long it is retained, who it is shared with, and ultimately what the Government is using it for," Lasoye urged.

Rights & Security International says organisations including Hope Not Hate and Maslaha also appear in or around the observations. The Campaign Against Antisemitism had a post logged that did not even name Prevent. It criticised police for failing to take a Hezbollah vigil seriously. A spokesperson said: "We aren't sure whether to be flattered or concerned that StaCU has picked up a post of ours."

The group added, "If it's because we've dared to be critical of law enforcement's lax attitude toward Islamist extremism in this country, we stand by what we said and would reiterate it for as long as it takes to bring about change. But if our post was flagged because StaCU agrees with us that police forces have failed to train their officers on what Islamist terrorism looks like and which organisations are banned, we hope that the message is being received and change is coming."

That last point tracks a long-running complaint. Sir William Shawcross, in his 2023 review of Prevent, wrote: "The bar for what RICU includes on Islamism looks to be relatively high, whereas the bar for what is included on the extreme Right-wing is comparably low."

Home Office figures for the year to September 2025 showed 10,293 Prevent referrals. Twenty percent were recorded as extreme right-wing ideology. Eight percent concerned Islamist extremism.

A Home Office spokesperson said: "Prevent does not track people who may have criticised the programme, and nor does it target any particular community." The department added that keeping the public safe is "our number one priority" and that Prevent has "moved more than 6,000 people away from violent ideologies since 2015."

The documents say otherwise on the first claim. StaCU collated the posts as "open-source complaints," stored them internally, and the Home Office refused to release the list until the Information Commissioner forced its hand. Nobody outside the unit can say who else sees the file, how long it is kept, or whether it is shared with police, platforms or other departments.

This is not an isolated compliance desk. It sits inside a growing stack of state machinery built to police speech, "narratives" and online anger.

In June, we laid out how the Home Office's Research, Information and Communications Unit has been used to manage the mass-migration story - briefing police to cast concerned citizens as "unsympathetic thugs," shaping family statements after migrant-linked killings, and running a higher bar for Islamism than for the so-called extreme Right.


The same week, ministers moved to give Ofcom faster powers to block "false information" during so-called crisis events - a phrase wide enough to cover any unrest the government would rather you not describe accurately.

London Mayor Sadiq Khan had already demanded a central government social-media "disinformation" unit, complaining of an "outrage economy" while knife crime, robbery and theft climbed on his watch. "If platforms fail to act, the state must have the tools to make them," he said.

Last week Prime Minister Andy Burnham used his first United Nations speech to announce a National Centre for Information Defence - a new machine to "detect, attribute and disrupt" what ministers call hostile information attacks and to stop a "distorted and untrue narrative about Britain."

He wrapped it in Russia, bots and "community cohesion." Nigel Farage called it a Ministry of Truth. "Never ever trust this authoritarian Government," he said. Defence Secretary Wes Streeting insisted: "We're not interested in policing domestic political dissent." Labour's record is why that promise is already worn thin.

Police have their own version. The National Internet Intelligence Investigations team, stood up after the 2024 Southport riots, has referred more than 100 "suspicious" posts to local forces, including dozens tied to protest-related activity.

Officials describe it as "a dedicated function at a national level for exploiting internet intelligence." Reform UK leader Nigel Farage called it "the beginning of the state controlling free speech."

The arrest figures sit underneath all of it. Between 2021 and 2025 at least 62,199 people were arrested in Britain on suspicion of communications offences - section 127 of the Communications Act 2003, the Malicious Communications Act 1988, and the Online Safety Act's false-communications offence.

That is roughly 34 arrests a day. Big Brother Watch director Silkie Carlo said speech policing is "out of control" and called the result an "Orwellian mess." Lord Toby Young asked why authorities spend so much time "policing our tweets when they could be policing our streets."

Prevent is sold as safeguarding. The logged posts are not bomb plots. They are workers calling official training biased, campaigners asking how data is stored, and a Jewish group complaining that police treat a banned terrorist organisation too lightly.

If that is enough to enter a Home Office database, the category of "acceptable" speech is already whatever officials decide it is on a whim.

Britain does not need another unit to hunt "untrue narratives." It needs a government that can survive being questioned without opening a file on the questioner.

Tyler Durden Fri, 10/02/2026 - 03:30

Hegseth Reveals "AutoWarCom" As $74 Billion Drone Splurge May Ignite This Stock

Hegseth Reveals "AutoWarCom" As $74 Billion Drone Splurge May Ignite This Stock

Beyond nuclear, the "powering up America" theme, AI, and the more recent "own the bottlenecks" theme, we have also outlined incoming tailwinds for drone and counter-UAS companies as the Department of War adapts to the wars in Ukraine and the Gulf area. That requires massive drone stockpiling and the development of conflict-free supply chains.

To do this, Defense Secretary Pete Hegseth is creating a four-star combatant command for autonomous warfare, seeking to accelerate the DoW's purchases across all categories of drones, robotics, and AI to prepare the military for warfare that has forever changed - that inflection point arrived in March. 

The Autonomous Warfare Command, dubbed "AutoWarCom," is set to become operational in the fall of next year, according to a new Wall Street Journal report.

The WSJ quoted Hegseth as saying in a speech earlier at US Marine Corps Base Quantico, Virginia, that this effort will be "the fastest peacetime shift in modern military history."

The key is the massive rearmament supercycle set to kick off, if it hasn't already. It will provide massive tailwinds for drone companies as the military begins stockpiling all categories of drones and counter-UAS technology while fortifying military installations around the world. 

To do this, the US supply chain must be built out to produce millions of one-way attack drones with components made domestically or in conflict-free areas. In other words, drone engines, blades, sensors, and other components must be sourced outside China.

Owen West, a former Marine, assistant defense secretary, and Goldman Sachs trader, will initially lead the effort alongside Navy SEAL test pilot Max Strasiser, according to the outlet.

"Once we apply sustained budget to changed doctrine, we will outperform the world," said West, who has been leading the Pentagon's Defense Innovation Unit. "And by snapping in AI, we will be ahead of the world, because we are the leaders in AI."

To understand the tailwinds coming to the drone industry, the report notes that the DoW has sought to triple spending on autonomous warfare, proposing $74 billion for drone and counterdrone technology in its largest-ever budget request.

Our drone theme began in late January, when we warned (read report) that every data center needs a kinetic interceptor (read here). The worst-case scenario materialized a month later when Iran attacked several data centers in the Gulf with one-way attack drones. Our pick in the space is Ondas.

Our reporting from last weekend shows that the DoW nearly doubled the value of a contract for Ondas' ULTRA platform, which appears to be a lower-cost Group 5 drone that could complement the MQ-9 Reaper and eventually assume some of its ISR missions (read report).

Follow the money. 

* * *

Tyler Durden Thu, 10/01/2026 - 23:00

Counter-ISIS Mission In Iraq Comes To An End

Counter-ISIS Mission In Iraq Comes To An End

Authored by Patty Nieberg via Task & Purpose,

The U.S. military-led mission to counter the Islamic State in Iraq has officially come to an end.

Counter-ISIS Mission In Iraq Comes To An End. Operation Inherent Resolve will continue with a new hub in Jordan to counter ISIS in Syria.

U.S. Central Command (CENTCOM) announced Wednesday that the "orderly departure" of U.S. personnel and equipment from Erbil Air Base in northern Iraq was officially complete. Officials said the withdrawal marked the end to Operation Inherent Resolve in Iraq, the U.S. military's counter-ISIS mission in the country.

The Erbil Air Base had served as a central hub for the Combined Joint Task Force-Operation Inherent Resolve mission since U.S. forces had been invited back by the Iraqi government to fight ISIS insurgents in the country.

The U.S. invaded Iraq in 2003 to topple Saddam Hussein, and by 2011, American forces left the country. As ISIS insurgents took hold of broad swaths of the country, Iraqi authorities invited a smaller contingent of U.S. forces to help counter the growing threat. Operation Inherent Resolve, a U.S.-led international coalition of military partners, was then established in 2014.

A majority of the 1,500 American and coalition partners supporting these operations worked out of Erbil. The mission will now be headquarters based in Jordan for U.S. forces to continue its mission focused on Syria, officials said.

"As we step back and hand full primary responsibility for Iraq's security to the Government of Iraq and the brave people of Iraq, U.S. and Coalition forces stationed across the region will remain ready to respond to any ISIS threats that arise," Adm. Brad Cooper, CENTCOM's commander, said in a release. "Maintaining our vigilance and readiness is essential to protecting the U.S. homeland and strengthening regional security."

For more than a decade, U.S. troops have trained and assisted Iraqi partner forces to fight ISIS in Iraq and Syria. In 2024, the U.S. and Iraq reached an agreement for a new bilateral security partnership, which ended the coalition's work in the country and moved the U.S. towards more of an "advisory" and "capacity-building" role for Iraqi security forces.

"ISIS no longer poses a systemic threat to Iraq's national security and Iraqi security forces, including the Peshmerga and other Iraqi Kurdistan Region security forces, now possess the capacity, leadership, and operational independence to unilaterally manage threats to their homeland," Cooper said.

When the new security partnership with Iraq was announced in 2024, U.S. officials would not say how many of the roughly 2,500 troops in Iraq would ultimately withdraw or stay behind. Department of Defense officials said in a release Wednesday that local security forces would lead counter-ISIS efforts in the country but that the U.S. would continue providing "targeted training and intelligence support to our Iraqi partners."

In response to inquiries about how many American troops would be in Iraq going forward, a U.S. official declined to comment, citing operational security.

The withdrawal comes as the U.S. war with Iran enters its eighth month. The U.S. withdrawal prompted mixed feelings among Iraqis about the departure of American forces in the country after decades of war, and concerns from Kurdish officials who worry that the removal of U.S. air defense equipment will leave the Kurdistan region vulnerable to Iranian drone and ballistic missile attacks.

Tyler Durden Thu, 10/01/2026 - 22:35

Trump Explains Why He's Okay With North Korea Having Nukes, But Not Iran

Trump Explains Why He's Okay With North Korea Having Nukes, But Not Iran

Here's what White House spokesperson Anna Kelly said a mere week ago on the rationale for the US attacking Iran: "The President is courageously ensuring that such an evil country never possesses a nuclear weapon, which will make the entire world safer and more stable," she said.

This week President Trump was asked why he seems OK with a deeply totalitarian state like North Korea and its dictator Kim Jong Un having nuclear weapons, and not Iran.

Trump's blunt response really deflates the sham talking points of the war's cheerleaders among Conservatism Inc, the FoxCon crowd, and NeoCon pundits and "intellectuals". So much for the whole defeat the "mullahs because they're evil!" fake morality tale...

"Ahh, because you had a different president. Kim Jong Un. He’s a friend of mine. He likes Trump. I like him," Trump said when a reporter pressed him.

"As long as I’m around, he’s going to be fine," Trump continued. "You know why? He respects me."

By this strange logic, Pyongyang - which has on many more occasions (than Iran) directly threatened the United States going back literally decades  - possessing nukes is just fine. Or in other words Kim="friend"/Good, Ayatollah= Rogue Bad Guy, according to the simplistic equation. The inconsistency of the obviously self-defeating 'moral high ground' narrative advanced by the administration is baffling.

On a more serious note, the above exchange highlights something deeper: nation-states most often seek nukes precisely in order to get respect especially when facing destruction at the hands of a more powerful enemy.

The US and Israel have long claimed that Tehran is bent on annihilating Israel, and that its leaders will pull the trigger the moment they develop an atomic weapon (a pursuit the Iranians have over many years denied). Essentially, this is the mad mullahs myth, based on the NeoCon axiom that every Iranian leader is an irrational actor fundamentally bent on ushering in nuclear apocalypse against the Jews, self preservation or any other domestic consideration be damned.

When Trump said of Kim, "he respects me" - the irony here is in reality it is Washington that's forced to 'respect' North Korea because it possesses dozens of nukes and has the military tech to deliver them. Countries like Iran want this 'respect' too.

On the level of strategic realism, it's just the way the world works (ask Gaddafi)-->

From the perspective of its beleaguered leaders who've been under US bombs and blockade for seven months, Iran has two choices. It must choose one:

1. Become Libya

2. Become North Korea

"We Came, We Saw, He Died." — Hillary Clinton

Below: On the 'moral mythmaking' of Neocons & Liberal Interventionists VS. strategic realism in international relations, an important conclusion:

"These leaders need to be treated as rational actors that, in turn with other members of their government, act based on strategy."

Rajan Menon, professor emeritus of international relations at the City College of New York, told Newsweek: "If you stand for nonproliferation, you can't say it's OK because they already have them." And the reality is, Menon continued, "there’s no reasonable way to undo the fact that North Korea is a nuclear-armed state."

*  *  *

An archived interview where retired diplomat Jim Jatras talks nukes and 'rogue' actors getting 'respect'...

Tyler Durden Thu, 10/01/2026 - 22:10

Australia's Tobacco Taxes Have Fueled A Massive Black Market For Cigarettes

Australia's Tobacco Taxes Have Fueled A Massive Black Market For Cigarettes

One lesson governments never seem to learn is that when taxes push the legal price of something high enough, a black market will eventually show up to collect the difference.

Australia is now getting a particularly ugly demonstration of that principle. After more than a decade of relentlessly increasing tobacco taxes in an effort to crush smoking, the country has created an enormous price gap between legal and illegal cigarettes, and organized crime has rushed in to fill it, according to the Financial Times.

A legal pack of cigarettes now costs close to A$60, or roughly US$42, making Australian cigarettes the most expensive in the world. Excise taxes account for more than 70% of that price, and the cost of legally purchased tobacco has roughly tripled since the end of 2016. Meanwhile, contraband cigarettes can be bought for around one-fifth of the legal price.

Charts: Financial Times

Not surprisingly, smokers have migrated to the underground market. Australia's tobacco regulator estimated that illegal cigarettes accounted for roughly 55% of the market last year, although other government estimates suggest illicit tobacco's share of consumption may be considerably higher.

Criminology professor James Martin estimates Australians spend about A$8.5 billion each year on illegal cigarettes and vaping products, roughly twice what the country spends on cannabis, cocaine, ecstasy and heroin combined. In practical terms, criminal organizations have become major tobacco distributors.

FT writes that the consequences are no longer limited to lost tax revenue or smokers buying cheap cigarettes under the table. The business has become lucrative enough to produce violent competition between criminal groups, including extortion, robberies and a wave of firebombings in Melbourne and Sydney. A recent Senate report cited three deaths connected to the violence, while the convenience-store industry says there have been roughly 300 arson attacks associated with the tobacco trade.

The Senate report described the situation as reaching a breaking point and recommended halting further excise increases while substantially reducing tobacco taxes. The government has resisted, maintaining that expensive cigarettes remain an effective deterrent. There is evidence for that argument: the smoking rate among Australians over 14 reportedly fell from 8.3% to 5.6% between 2023 and 2025.

Charts: Financial Times

But nicotine consumption tells a less straightforward story. Wastewater measurements from the Australian Bureau of Statistics indicate that nicotine consumption increased by almost 40% between 2017 and 2025, with illicit tobacco driving much of the increase. Illegal vaping products have also captured an overwhelming share of their market.

The fiscal side of the experiment has deteriorated just as dramatically. Tobacco excise revenue reached about A$16 billion in 2020, fell by more than half by 2025 and is projected to sink toward A$2 billion by 2030.

Authorities have committed A$365 million since 2024 to fighting the illicit trade, including efforts against smugglers and retailers. One recent joint operation with Chinese authorities intercepted roughly 60 million cigarettes shipped from Shanghai to Sydney, valued at about A$92 million. But the market continues to spread, with contraband reportedly sold online, from parking lots and through ordinary businesses such as barbers and fruit shops.

Australia's tobacco experiment has therefore arrived at a strange destination. Legal cigarettes have been taxed to extraordinary prices, government revenue is collapsing, billions of dollars are flowing through an underground economy, and criminal groups are fighting over the proceeds. Whatever public health benefits higher taxes initially produced, policymakers are now confronting what happens when the legal price of a widely demanded product becomes disconnected enough from its black-market price to make breaking the law enormously profitable.

Tyler Durden Thu, 10/01/2026 - 21:20

How The Iran Conflict Opened A New Threat To The Global Monetary System

How The Iran Conflict Opened A New Threat To The Global Monetary System

Authored by Milan Adams via Preppgroup,

Midnight fell differently on February 28, 2026. Across trading floors from Singapore to Chicago, monitors flickered with data streams that would soon curdle into panic. At 0400 hours Tehran time, American B-2 Spirit bombers and Israeli F-35I Adir fighters crossed into Iranian airspace, unleashing Operation Epic Fury. Nine hundred strikes in twelve hours. Ali Khamenei, Supreme Leader of the Islamic Republic, perished in the initial bombardment, his body recovered from the rubble of a command bunker beneath Tehran's northern suburbs. Markets had anticipated conflict. They had not anticipated decapitation.
Brent crude, trading at $72.48 per barrel at market close on February 27, surged past $120 within seventy-two hours. By March 19, Dubai crude reached $166 per barrel, an all-time record. California gasoline exceeded $5 per gallon.

Kristalina Georgieva, Managing Director of the International Monetary Fund, stood before cameras in Washington on April 9, 2026. "All roads now lead to higher prices and slower growth," she declared. Her institution had just slashed global growth projections to 3.1 percent, down from 3.4 percent anticipated before the first missiles launched. "Had it not been for this shock, we would have been upgrading global growth." Instead, the Fund warned of a "severe scenario" where global growth collapses to 2.0 percent, brushing against the technical definition of worldwide recession - a threshold breached only four times since the Second World War. "This would mean a close call for a global recession," the World Economic Outlook stated.

Donald Trump, returned to the presidency for a second non-consecutive term, addressed the nation from the Oval Office on August 20, 2026. "Any country that allows its financial institutions, businesses, airports, or government entities to provide any type of lifeline to Iran will itself face tremendous economic consequences," he warned, announcing what he termed "the toughest sanctions in history." Earlier, he had posted an image on social media showing the Strait of Hormuz crudely labeled as "New US Territory," a digital annexation that sent tremors through diplomatic channels. His administration's Operation Economic Fury sought to complete what Operation Epic Fury had begun. "To the ordinary soldiers supporting this regime," Trump addressed Iranian conscripts directly, "as more and more of your paychecks stop or are supposedly just delayed, ask whether your commanders are leading your country to triumph or to ruin."

Jerome Powell, in his final months as Federal Reserve Chair, confronted the economic paradox that would define 2026. At a Harvard forum on March 30, he admitted the central bank's predicament with uncharacteristic candor. "Nobody knows," he stated, referring to the war's ultimate economic impact, while acknowledging that "you can be confident that an inflationary shock will fade, but have very little idea how long it will take." The Fed's March 18 decision to hold interest rates steady - projecting only a single rate cut for the year despite inflation spiking to 3.3 percent - represented a capitulation to uncertainty. Powell's institution projected higher inflation, steady unemployment, and minimal monetary relief.

Nouriel Roubini, the economist whose prescient warnings preceded the 2008 financial collapse, offered scenarios in May 2026 that chilled institutional investors. "Oil prices could spike past $200 a barrel in the worst-case scenario," he predicted, describing a return to "1970s stagflation." Mohamed El-Erian, former Pimco chief and now Chief Economic Advisor at Allianz, tweeted his assessment of the IMF's April report: "Reading between the lines, the message of today's IMF flagship report is sobering: Virtually every challenge facing the global economy is poised to intensify due to the fallout of the Middle East War."

The World Bank's June 11, 2026 Global Economic Prospects report confirmed these apprehensions. Global growth would slow to 2.5 percent in 2026, the weakest expansion since the COVID-19 pandemic. For developing and emerging markets, the forecast plummeted to 3.6 percent. Iran's economy contracted by 6.1 percent, with the Bank noting that "real GDP is projected to contract by 6.4 percent in 2026, reflecting the collapse in tourism, weaker consumption, disrupted supply chains, heightened insecurity, and prolonged displacement." Qatar and Kuwait faced potential GDP contractions of 14 percent. The Institute for Economics and Peace calculated that a resumption of full-scale hostilities would deliver a $2.2 trillion hit to the world economy.

Economic Impact Projections by Institution, 2026 Institution Global Growth Forecast Inflation Projection Severe Scenario Oil Price Assumption IMF (April 2026) 3.1% (down from 3.4%) 4.4% 2.0% growth, 5.4% inflation $100/bbl (reference), $140+ (adverse) World Bank (June 2026) 2.5% (down from 2.9%) 4.0% 2.0% or below $120/bbl average OECD (March 2026) 2.7% 3.2% US, 3.0% Eurozone Technical recession in energy-intensive economies $90-110/bbl range Oxford Economics 2.8% 4.2% 1.5% growth if Hormuz closed 3+ months $140/bbl threshold for demand destruction Regional GDP Contraction Projections, 2026 Economy Pre-War Forecast Post-War Projection Revision Primary Transmission Channel Iran +1.1% -6.1% to -6.4% -7.2 pp Infrastructure destruction, sanctions Qatar +3.2% -14.0% -17.2 pp LNG export disruption, Hormuz closure Kuwait +2.8% -14.0% -16.8 pp Oil export cessation Iraq +2.1% -8.5% -10.6 pp Supply chain fracture, refugee costs Bahrain +1.9% -6.8% -8.7 pp Financial sector exposure Saudi Arabia +3.5% -3.0% -6.5 pp Reduced oil volumes, price volatility UAE +3.8% -5.0% -8.8 pp Trade finance disruption Eurozone +1.2% +0.8% -0.4 pp Energy import costs, manufacturing United States +2.1% +1.8% -0.3 pp Gasoline prices, consumer sentiment Oil Market Disruption Metrics, February-September 2026 Metric Pre-War (Feb 27) Peak Crisis (Mar 19) Recovery Phase (Jun 24) Current (Sep 30) Brent Crude ($/barrel) $72.48 $166.00 (Dubai) $72.24 $73.23-$97.00 Daily Oil Flow via Hormuz (mbpd) 21.0 0.5 8.2 14.5 Strategic Reserve Drawdown (US, mb) 0 180 120 85 Gasoline Price California ($/gal) $4.12 $5.08+ $4.45 $4.28 LNG Force Majeure Declarations 0 12 (QatarEnergy) 3 0

Beneath these statistics lies a more troubling reality. Global debt reached $348 trillion in 2025, according to the Institute of International Finance, expanding by nearly $29 trillion in that single year. By mid-2026, estimates placed the figure above $365 trillion. This edifice of obligation, constructed during fifteen years of central bank suppression of interest rates, now faces a refinancing crisis as monetary authorities maintain elevated borrowing costs to combat inflation. The OECD's Global Debt Report 2026 warned of "increasing pressures from sustained fiscal deficits, rising interest costs and investment needs, a structural decline in long-term demand, and growing refinancing risks as the maturity of issuance shortens."

Small and medium enterprises find themselves particularly exposed. S&P Global's 2026 banking risk analysis noted that SMEs "have thinner capital buffers and proportionately more floating-rate exposure," rendering them acutely vulnerable to the higher interest costs that the Iran war's inflationary impact necessitates. When the Federal Reserve chose steady rates over relief in March 2026, these businesses absorbed the blow directly.

The weaponization of the dollar has generated blowback that Washington's Treasury Department struggles to contain. China's Cross-Border Interbank Payment System (CIPS), processing the equivalent of $245 trillion in yuan-denominated transactions in 2025, has emerged as a functional alternative to SWIFT. By January 2026, CIPS linked 1,467 indirect participants across 119 countries, connecting 4,800 banks in 185 nations. While still smaller than SWIFT, its trajectory suggests a fragmentation of monetary infrastructure that the Iran conflict has only accelerated.

The petrodollar system faces unprecedented stress. Russia and Saudi Arabia, the two largest oil producers, generated "essentially zero petrodollars" in 2025 according to Wright Research analysis, having shifted to yuan-denominated settlements. Iran, excluded from dollar markets since 1979, pioneered this transition. Now the template spreads. BRICS nations conducted an estimated 90% of intra-bloc transactions in local currencies by 2025.

This matters profoundly for American fiscal sustainability. Foreign holdings of U.S. Treasury securities have plateaued as central banks diversify reserves. The dollar's share of global foreign exchange reserves declined from 73% in 2001 to approximately 54% in 2025, per IMF data. Each percentage point shift represents hundreds of billions in reduced demand for dollar-denominated assets, increasing the interest premium Washington must pay to finance its $34.6 trillion national debt.

The Iran war operates as an accelerant upon these pre-existing trends. When Trump threatened "crushing economic warfare" in August 2026, he extended a sanctions regime that had already demonstrated diminishing returns. Iran's economy, while battered by 6.4 percent contraction and currency collapse, had developed sophisticated evasion mechanisms through shadow banking networks and cryptocurrency channels. The Islamic Republic's oil smuggling to China, estimated at 1.2 million barrels daily despite sanctions, continued through "dark fleet" tankers operating with disabled transponders.

European Central Bank President Christine Lagarde, in deliberations that postponed planned rate cuts on March 19, 2026, confronted the dilemma that would define transatlantic economic divergence. Energy-intensive European economies faced technical recession risks if the Hormuz maritime blockade persisted. German manufacturing, already weakened by the cessation of Russian natural gas supplies following the Ukraine conflict, confronted additional input cost shocks. The ECB raised its 2026 inflation forecast while slashing growth projections.

Japan's position proved equally precarious. As the world's largest liquefied natural gas importer, Tokyo faced energy security vulnerabilities that the Iran war exposed with brutal clarity. QatarEnergy's declaration of force majeure on LNG exports during the March 2026 Hormuz closure sent Japanese utilities scrambling for alternative suppliers at premium prices. The yen, already depreciating against the dollar amid interest rate differentials, faced additional pressure as import costs surged.

China's strategic calculus shifted in response. While publicly advocating de-escalation, Beijing accelerated yuan internationalization through energy purchase agreements denominated in renminbi. Saudi Arabia's 2024 decision to allow yuan-settled oil sales, followed by similar arrangements with Iraq and the UAE, created the infrastructure for a parallel monetary order. The Iran war's disruption of dollar-denominated energy flows provided practical demonstration of the vulnerabilities inherent to single-currency dependence.

India's position illustrated the impossible choices facing emerging economies. As the third-largest oil importer, New Delhi faced inflationary pressures that threatened the Modi government's economic credibility. Yet India's strategic partnership with the United States constrained options for evading American sanctions on Iranian oil. The result: higher import bills, currency depreciation, and postponed infrastructure spending as fiscal resources diverted to energy subsidies.

The banking sector's exposure to these stresses remains imperfectly understood. Commercial real estate loans, particularly those financing office properties in urban centers hollowed out by remote work trends, carry default risks that energy price shocks amplify. Regional banks in the United States, having faced depositor flight in the 2023 Silicon Valley Bank collapse, now confront renewed pressure as bond portfolios lose value amid interest rate volatility. The $1.5 to $2.1 trillion private credit market operates with opacity that systemic risk assessments struggle to penetrate.

Corporate debt maturities in 2026-2027 present a refinancing cliff of historic proportions. Companies that borrowed at near-zero rates during the quantitative easing era must now roll obligations at 6-8 percent interest, if markets remain open to them at all. The "zombie firm" phenomenon - enterprises kept operational only through continuous debt refinancing rather than operational profitability - threatens mass insolvency if credit conditions tighten further.

Agricultural markets compound these vulnerabilities. Wheat and corn prices, already elevated by Ukraine conflict disruptions and climate anomalies, face additional pressure from energy-intensive fertilizer production costs. Natural gas, the primary feedstock for nitrogen fertilizer manufacturing, saw European prices spike 300% during the March 2026 Hormuz closure. The transmission to food prices operates with inevitable lag but equal certainty.

Humanitarian consequences extend beyond abstract statistics. Iran's population of 87 million faces food insecurity as sanctions disrupt import financing and currency collapse destroys purchasing power. The rial's depreciation against the dollar, exceeding 80% since 2021, has rendered imported medicines unaffordable for ordinary families. Brain drain accelerates as professionals emigrate to Dubai, Istanbul, and European capitals.

Israel's economy, despite receiving $14.3 billion in American military aid during 2026, faces its own contradictions. The Bank of Israel slashed growth prospects as the war's toll mounted, with defense spending consuming resources that might otherwise support social services. Military mobilization of reservists disrupted technology sector productivity, while tourism revenues collapsed amid security concerns.

The United States enters the final quarter of 2026 with economic indicators that defy simple categorization. Unemployment remains near historic lows at 4.1%, yet labor force participation among prime-age males continues declining. GDP growth, projected at 1.8% for the year, masks distributional shifts that concentrate gains in asset-owning classes while wage workers confront eroded purchasing power. The Federal Reserve's preferred inflation metric, core PCE, hovers above target at 3.3%, constraining monetary policy flexibility.

Presidential rhetoric in this environment oscillates between triumphalism and threat. Trump's August 2026 declaration that Iran "outsmarted themselves" over Hormuz control, accompanied by social media posts depicting the waterway as American territory, suggests a transactional approach to territorial sovereignty that unsettles international law. His simultaneous threats against nations maintaining economic ties to Tehran create compliance dilemmas for allies whose strategic interests diverge from Washington's.

The configuration of military confrontation, monetary stress, and debt fragility creates conditions for systemic stress that would exceed the 2008 financial crisis in scope. Not through single catastrophic event but through cascading failures that compound across interconnected systems. An oil price spike above $200 per barrel, as Roubini warned, would trigger demand destruction in transport sectors that eliminates millions of jobs. Corporate defaults in energy-intensive industries would cascade through credit default swap markets that remain opaque to regulators. Sovereign debt crises in emerging markets would force IMF interventions that impose austerity conditions, generating political instability that feeds further conflict.

The dollar's reserve currency status faces its most credible challenge since Bretton Woods. Not because rivals possess superior alternatives - the yuan remains non-convertible, the euro fragmented - but because Washington's weaponization of financial infrastructure has created irresistible incentives for diversification. Each sanctions round against Iran accelerates this process. Each threat of secondary sanctions against allies hastens the construction of parallel systems.

The optimistic scenario, increasingly dismissed by market participants, envisions negotiated settlement by early 2027, Hormuz reopening, and gradual price normalization. Even this outcome, Georgieva emphasized, leaves "permanent scarring" on growth trajectories. Output levels in 2030 will remain 2% below pre-war trends according to IMF projections. The opportunity cost of military confrontation - the infrastructure unbuilt, the research unfunded, the human potential unrealized - accumulates across decades.

The pessimistic scenario defies precise modeling because its variables interact non-linearly. Oil at $200 per barrel simultaneously triggers recession and accelerates energy transition investments that strand fossil fuel assets. Banking crises in vulnerable jurisdictions propagate through derivatives exposures that regulatory stress tests failed to capture. Political radicalization, fed by economic desperation, produces leadership incapable of crisis management.

Historical analogies offer limited guidance. The 1973 oil shock occurred within a Bretton Woods framework that no longer exists. The 2008 financial crisis, while demonstrating interconnected fragility, benefited from coordinated central bank responses that current geopolitical polarization may preclude.

What distinguishes the present moment is the convergence of multiple stressors upon a system already operating near capacity. Global debt at $365 trillion represents claims that cannot all be satisfied simultaneously. The Iran war's energy price shock applies pressure to this leveraged structure in ways that individual components - sovereign borrowers, corporate issuers, financial intermediaries - may withstand in isolation but cannot survive collectively.

The Strait of Hormuz, that narrow channel through which one-fifth of global petroleum flows, embodies this vulnerability. Twenty-one million barrels daily transit waters barely twenty-one miles wide at their narrowest point. Iranian missile batteries, mines, and fast attack craft can interdict this flow with minimal warning. American carrier groups can suppress such threats at enormous cost but cannot eliminate them entirely.

Trump's social media annexation of Hormuz as "New US Territory" in August 2026, however rhetorical, signaled an American willingness to assert direct territorial control over international waterways that precedent has long treated as global commons. Such assertions, if operationalized, would encounter resistance not merely from Iran but from China, Russia, and regional powers whose energy security depends upon unimpeded navigation.

Economic warfare, as practiced against Iran in 2026, operates through mechanisms that escape traditional accounting. The exclusion of Iranian banks from SWIFT messaging does not merely inconvenience; it severs commercial relationships built over decades. The secondary sanctions threatening foreign entities that transact with Iran force impossible choices upon multinational corporations between American market access and Iranian commercial relationships. The cumulative effect is a fragmentation of global commerce into competing blocs that reduces overall efficiency and prosperity.

The BRICS bloc's expansion in 2024 to include major oil producers Iran, Saudi Arabia, and the UAE created an organizational framework for this monetary diversification. While the proposed common BRICS currency remains technically distant, the infrastructure for reduced dollar dependence develops apace.

For American households, these macroeconomic abstractions translate into concrete hardships. Gasoline prices above $5 per gallon, as experienced in California during March 2026, reduce discretionary spending that drives consumer-dependent growth. Home heating costs surge in northern winters. Food prices, transported by diesel-powered logistics networks, follow energy costs upward. The Federal Reserve's interest rate restraint, maintained despite these pressures to combat underlying inflation, keeps mortgage rates elevated and housing affordability diminished.

The political economy of these stresses generates feedback loops that complicate resolution. Populist movements, fed by economic grievance, demand more aggressive confrontation with perceived adversaries rather than diplomatic compromise. Interest groups benefiting from military expenditure lobby for sustained confrontation. Media ecosystems amplify threat perception, reducing the political space for negotiation.

Iran's leadership, despite decapitation and economic devastation, maintains negotiating positions that reflect their assessment of American political constraints. They observe the American electoral cycle, the influence of pro-Israel constituencies, and the transactional nature of Trump's diplomacy. Their strategy of brinkmanship - escalating to de-escalate - assumes that Washington's pain threshold, while higher than Tehran's, remains finite.

The September 2026 ceasefire, brokered through Qatari intermediation, paused direct military confrontation but resolved nothing. Iranian nuclear facilities, though damaged, remain operational at undeclared sites. Israeli security guarantees, demanded as condition for permanent settlement, exceed what Tehran's fractured leadership can deliver. American troops remain deployed across the region in configurations vulnerable to proxy attack.

Economic forecasts for 2027 diverge based upon assumptions about this unresolved confrontation. The IMF's reference scenario assumes short-lived conflict with gradual normalization, projecting 3.1% global growth recovery. Its adverse scenario, increasingly probable as negotiations stall, envisions 2.5% growth with 5.4% inflation. The severe scenario - 2.0% growth brushing recession - requires only modest additional escalation: Hormuz closure persisting beyond three months, Iranian missile strikes on Saudi infrastructure, or Israeli expansion of operations into Lebanon and Syria.

Each of these triggers remains plausible. Iranian Revolutionary Guard factions, empowered by Khamenei's death and competing for succession influence, may calculate that renewed confrontation serves domestic political purposes. Israeli leadership, facing domestic pressure for decisive security solutions, may authorize strikes that previous restraint avoided. American electoral considerations in the approach to 2028 may incentivize foreign policy aggression that rallies domestic support.

The debt dimension compounds these risks. Sovereign borrowers facing recessionary revenue shortfalls and inflationary expenditure increases encounter debt servicing requirements that crowd out productive investment. Corporate issuers with 2027 maturities confront rollover costs that render previously viable enterprises insolvent. Financial intermediaries, holding claims upon these borrowers, face capital constraints that restrict new lending. The resulting credit contraction amplifies recessionary dynamics.

Central banks, having deployed extraordinary measures during the COVID-19 pandemic, possess diminished capacity for repetition. Balance sheets already swollen with asset purchases offer limited room for additional expansion. Interest rates, while above zero, remain below inflation in real terms, constraining traditional monetary policy space. Fiscal authorities, confronting debt burdens that limit countercyclical spending, face political resistance to deficit expansion.

A system that requires 3%+ growth to service $365 trillion debt will struggle to maintain stability at 2% growth without structural adjustment that political processes resist. The Iran war, by reducing growth and increasing inflation simultaneously, forces this adjustment upon unwilling participants. Whether through negotiated settlement that restores energy flows and reduces risk premiums, or through continued confrontation that amplifies systemic stress, adjustment will occur.

The form it takes - gradual normalization or sudden rupture - remains the variable that will define economic experience for the decade ahead. Current trajectory favors rupture: unresolved confrontation, accumulating sanctions, escalating rhetoric, and structural fragility that compound across months rather than years. The optimistic scenario requires not merely ceasefire but durable settlement, not merely sanctions relief but economic reconstruction, not merely diplomatic engagement but fundamental reassessment of regional order.

Such reassessment appears improbable given current leadership configurations. Trump approaches his final term's conclusion with incentive to cement confrontational legacy rather than compromise. Iranian factions compete for succession advantage through nationalist positioning rather than pragmatic accommodation. Israeli security establishment, validated by apparent military success, resists territorial concessions that might address underlying grievances.

The economic consequences of this political configuration will unfold across quarters and years with accumulating damage. Growth forecasts will revise downward repeatedly. Inflation projections will revise upward. Debt sustainability assessments will deteriorate. Financial market volatility will increase. Each revision, each deterioration, each increase reduces the margin for error that prevents systemic crisis.

The Iran war has demonstrated that geopolitical confrontation can impose economic costs that exceed the combatants' calculations. Those costs, interacting with pre-existing vulnerabilities in global debt and monetary architecture, create conditions for crisis that policy instruments cannot readily address. Whether this crisis arrives in 2026, 2027, or beyond matters less than its likelihood given current trajectory.

Markets, having priced some risk premium, may remain complacent until rupture occurs. Policymakers, having normalized extraordinary measures, may discover their exhaustion only in crisis. Populations, having accommodated gradual deterioration, may confront sudden deprivation with inadequate social infrastructure. The Iran war's ultimate economic legacy may prove not the direct costs of military confrontation but the revelation that global economic integration, assumed permanent, rests upon political foundations more fragile than understood.

Tyler Durden Thu, 10/01/2026 - 20:55

The $40 Billion Minerals Gamble: Can Trump Break China's Chokehold Before The West's Rearmament Hits A Wall?

The $40 Billion Minerals Gamble: Can Trump Break China's Chokehold Before The West's Rearmament Hits A Wall?

The Trump administration has committed billions of dollars to rebuild conflict-free critical materials supply chains outside China. The question remains whether these supply chains will be up and running in time for the West's rearmament cycle, which desperately needs missiles, bombs, drones, fighter jets, submarines, and even night-vision equipment.

Bloomberg Intelligence analysts published a note today titled "Defense-Critical Mineral Capital Moves Downstream," analyzing whether more than $40 billion in announced support will translate into reliable near-term supplies and improve defense readiness.

"Execution, not government support alone, will determine if US critical-minerals policy translates into durable revenue and stronger defense readiness," the analysts wrote.

They continued, "Policy is moving beyond grants toward equity, price floors, loans, offtake and stockpiles designed to preserve capacity through commodity cycles."

Adding, "MP Materials and ATALCO offer the clearest near-term links to magnets and gallium, while IperionX and Perpetua provide targeted titanium and antimony exposure. Defense-grade output, customer qualification and contracted volume still need to follow announced capacity."

Beyond the mining aspect of rejiggering critical materials supply chains, refining and downstream production remain critically important, including heavy-rare-earth separation, manufacturing yields, customer qualification, and reliable deliveries.

These high-grade critical materials are essential for missiles, drones, satellites, and undersea platforms. The F-35 alone requires more than 900 pounds of rare-earth materials, the analysts noted.

Breaking China's "quasi-monopolistic position" in critical materials is unlikely to be a this-decade story. Christian Keller, Barclays' global head of economics research, recently pointed out that mining and refining of these critical materials will persist through 2030. 

Stifel aerospace and defense analyst Jonathan Siegmann wrote in a note last week that investors want to "own the bottlenecks" in the critical materials space, mainly the producers that can deliver today. 

Siegmann's most important chart in the report was the near-depletion of US tungsten reserves. 

Adrien Rabier, Bernstein's equity analyst covering European aerospace and defense, put a timeline on the EU's defense rearmament supercycle, which is already ramping up and will last through 2030.

Bloomberg Intelligence analysts added that the Trump administration's Project Vault, intended to rebuild the nation's critical materials stockpiles, provides another buffer by financing inventories for civilian and dual-use manufacturers can draw down and replenish. It complements the National Defense Stockpile but does not replace its emergency role or guarantee that material will be available in military-qualified form.

The only problem is that new mining projects take years to commission, while refining supply chains also take time to come online, as this shortage of critical materials collides with a rearmament supercycle in the West. As for tungsten, Jefferies, Goldman, and Stifel favor this miner, which is set to become the West's largest ex-China supplier. 

Tyler Durden Thu, 10/01/2026 - 20:30

3 Huge Storms Will Combine Over The Central United States To Form A Gigantic "Hybrid Storm" That Will Cause Widespread Flooding

3 Huge Storms Will Combine Over The Central United States To Form A Gigantic "Hybrid Storm" That Will Cause Widespread Flooding

Authored by Michael Snyder via End Of The American Dream,

We are about to witness something extremely rare. At the same time that a historic financial storm is brewing on Wall Street as bond yields go wild, a historic weather event threatens to dump trillions of gallons of rain over the middle of the country. Meteorologists are telling us that 3 enormous storms will combine to create an absolutely colossal "hybrid storm" that will cause "considerable" flooding over large stretches of the nation. We have never seen anything quite like this before, and it appears that this disaster will be significantly worse than the experts were originally anticipating.

The remnants of Hurricane Polo are about to merge with the remnants of Hurricane Odalys and an upper level low that will be funneling massive amounts of moisture from the Gulf of Mexico to form "a new, hybrid storm" which will be very dangerous...

A soggy, potentially dangerous week is ahead for a "huge" section of the central United States, forecasters warned, as the remnants of Hurricane Polo interact with a separate, sprawling weather system to bring days of rain and possible flooding.

"As these features combine into a new, hybrid storm, the influx of moisture spreading across the central United States will pose the risk for flash flooding," AccuWeather meteorologist Alyssa Glenny said.

The National Weather Service explained that tropical moisture from the remnants of Hurricane Odalys and Hurricane Polo will surge over the Southwest into the central U.S. this week with several days of heavy to excessive rainfall, which may bring limited to "considerable" flooding. The threat area is "huge," the weather service said in an online forecast.

This wasn't supposed to happen.

But it is happening.

Even if the remnants of Hurricane Polo and Hurricane Odalys were not an issue, the upper level low which is about to move into the center of the nation "would still be a heavy rain and flood threat"...

In addition to the moisture from Polo, the other system, known as an upper-level low, or trough, will be moving into the central U.S. from the West, Marc Chenard, a meteorologist with NOAA's Weather Prediction Center, told USA TODAY.

That low will help funnel plentiful moisture northward from the Gulf, he said. "This will produce a widespread area of heavy rainfall."

"Even if we didn't have Polo," there would still be a heavy rain and flood threat in the central U.S. this week, Chenard told USA TODAY.

It is very unusual to see three major systems come together like this.

On Tuesday, flood watches were issued in 10 different states, and we are being warned that this is just the beginning...

Flood watches have been issued in ten states Tuesday morning as meteorologists warn that the widespread effects of Hurricane Polo are merging with leftover moisture from Hurricane Odalys and a dip in the natural jet stream running across the US to create one massive storm.

This 'triple flood' is expected to bring the heaviest rainfall to Arizona, Colorado, New Mexico, Kansas, Oklahoma and Texas on Tuesday, but the storm threat will continue throughout the entire week.

To say that the worst hit areas will get a lot of rain is a major understatement.

According to Accuweather, there are a few isolated locations that could see up to 18 inches of rainfall...

AccuWeather's latest forecast has warned that as much as eight inches of rain could flood parts of Colorado, Iowa, Kansas, Missouri, Nebraska, New Mexico, Oklahoma and Texas this week.

However, the weather service's worst-case scenario noted up to 18 inches of rain could fall in isolated areas.

If you live in an area that is prone to flooding, you may want to brace for the worst.

We are being told that in some parts of New Mexico this could be "the most dangerous flash flooding risk in the last 5 years or more"...

"In some places, especially in New Mexico, this may be the most dangerous flash flooding risk in the last 5 years or more," AccuWeather Chief Meteorologist Jon Porter said.

Accuweather is normally very conservative in their forecasts, and so I would take this warning very seriously.

Even if you do not live in one of the danger zones, that doesn't mean that you won't get rain.

In fact, Accuweather is projecting that 30 U.S. states will receive at least one inch of rain this week...

There are many parts of the nation that could desperately use some rain.

But we didn't want to get it all at once.

Hopefully the flooding will not be quite as bad as they are currently forecasting.

There is one other thing that I wanted to mention in this article.

An extremely vast "Kelvin wave" will soon bring "an untold amount of warm water" to the west coast...

Concerns are mounting about an ocean phenomenon known as a Kelvin wave that could raise sea levels along the California coastline by up to a foot, as scientists say El Niño is supercharging the threat of storm surges and flooding in the coming months.
As an incredibly strong El Niño continues to develop in the Pacific, the phenomenon brings with it a strange shift in the ocean. The Kelvin wave phenomenon is created when trade winds that usually blow from South America towards Asia die down or reverse in El Niño years, setting off a massive, slow-moving slosh of water.
Kelvin waves are not like crashing waves at the beach. They are planetary in scale, spanning thousands of miles. And when a Kelvin wave kicks off, it brings with it an untold amount of warm water that slowly moves from the western Pacific, along the equator, towards South, Central and North America.

This "Kelvin wave" hit South America late last month, and now it is traveling north toward California...

"You can follow them along ... we see the higher sea levels along the equator, and when the wave reaches the coast of South America, it cannot continue to go eastward," Severine Fournier, a research scientist studying ocean circulation at Nasa's Jet Propulsion Laboratory, said. "So it goes north and south."

One such wave hit the northern tip of South America in late August and has begun moving up towards the west coast of the US. That wave could reach California shores within days, and when it does, ocean scientists say it may raise sea levels by up to a foot for months as El Niño lingers and keeps that warm water trapped along the coast.

Ocean levels along the west coast will rise significantly.

But that is only temporary.

Of much greater importance is what all of this warm water will mean for storms that approach the California coastline.

Normally, very cool water along the California coastline causes tropical storms and hurricanes to fizzle out as they approach.

But now conditions will be ideal for a tropical storm or a hurricane to come slamming right into the state.

The Super El Niño that is causing this to occur will be sticking around for quite a while, and so this is a story that is not going to go away any time soon.

Tyler Durden Thu, 10/01/2026 - 20:05

Pages