Zero Hedge

Futures Slide From Record As Oil Jumps On Hormuz Tanker Attacks, 30Y Yield Hits 2002 High

Futures Slide From Record As Oil Jumps On Hormuz Tanker Attacks, 30Y Yield Hits 2002 High

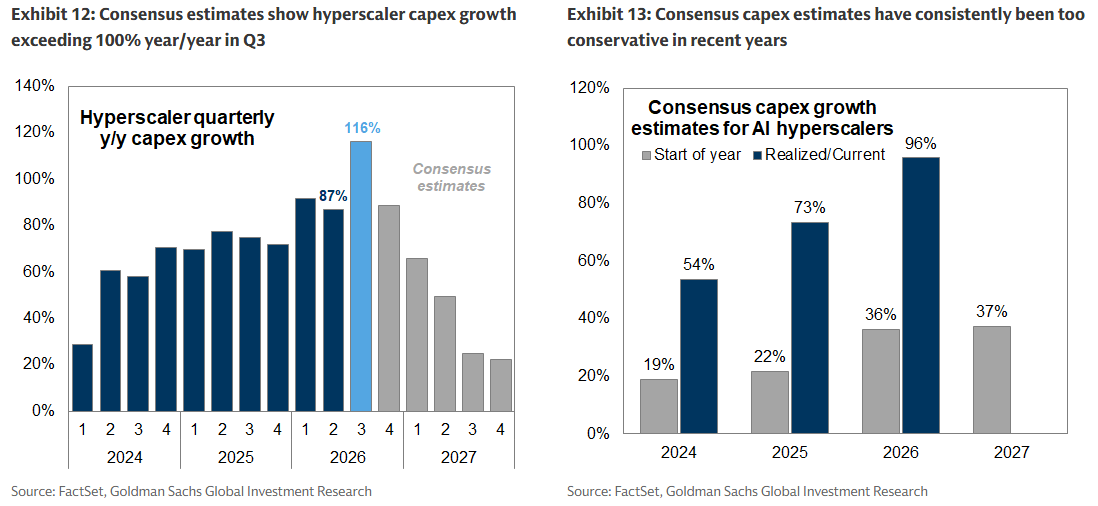
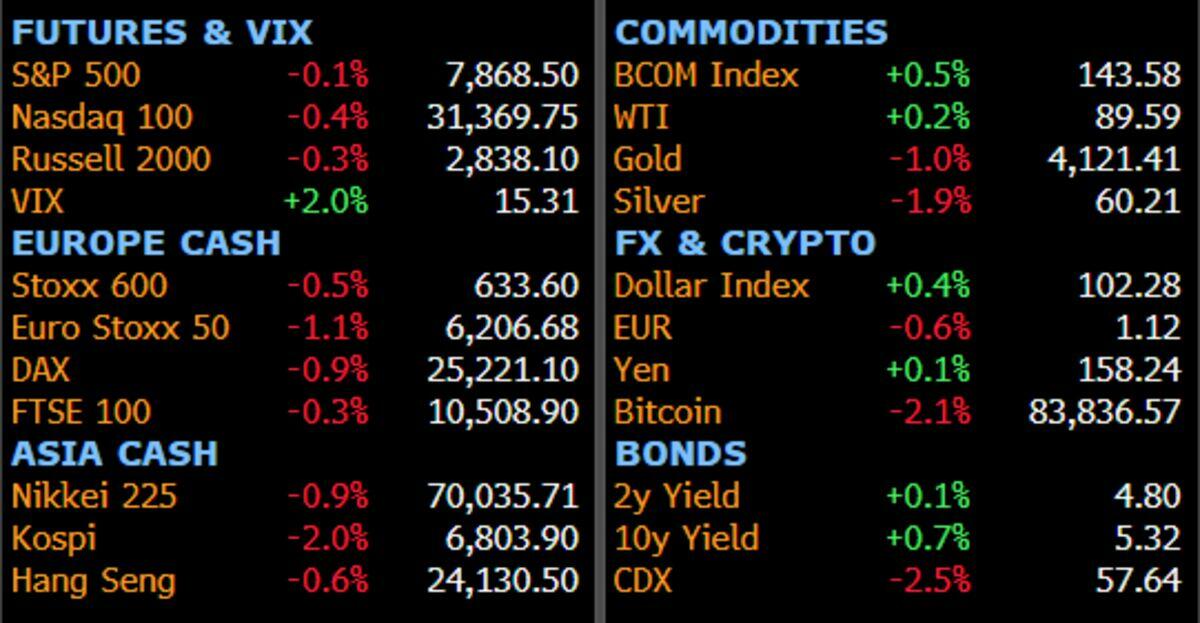
US equity futures are sliding from Tuesday's record close as oil climbs back above $100, global bond yields resume their ascent and the AI bubble debate makes an unwelcome comeback. As of 8:00am ET, S&P futures are 0.4% lower, trading around 7,844, while Nasdaq 100 and Dow futures drop 0.6%; small caps are also under pressure with Russell 2000 futures down 0.3-0.4% as usual. On Tuesday the S&P 500 rose 0.6% to close at a record high for the first time since August 13, its fourth consecutive advance and longest winning streak in about two months, with the Nasdaq 100 also closing at an all-time high. Premarket, the Mag 7 are mixed (Apple +0.4%, Tesla -0.8%) while Memory, Semis and Software are all lower as the AI theme sees some profit-taking following a slide in Korea's Kospi; Constellation Brands slides 4.7% after the Corona brewer reaffirmed guidance, Neogen jumps 11% on an earnings beat, and SpaceX falls 2% on a report it is seeking to raise $40 billion in a chip-backed SPV to buy Nvidia chips. The day's driver is once again oil: Iran has increased the pace of attacks on tankers in the Strait of Hormuz just as shipments through the chokepoint approach prewar levels, sending Brent up 1.4% to $101.94 and WTI up 0.7% to $90.02. That has pushed Treasuries lower, with the long end leading: the 30-year yield climbed 5bps to 5.70%, the highest since 2002, while the 10Y trades around 5.335%, up 5bps, and 2s10s is 4bps steeper. The Bloomberg Dollar Spot Index rose 0.3%, approaching its highest levels since June, as the euro slid to a 16-month low against the pound amid renewed French fiscal angst, with the OAT-Bund spread back out to 138bps. Gold dropped 1% to around $4,121 and silver fell 1.9% to $60.21, while copper is flat with Chinese buyers still away for Golden Week. Bitcoin is down 2.4% near $83,600. US economic data slate includes MBA mortgage applications (7am, -4.2%), September NY Fed 1-year inflation expectations (11am), FOMC minutes from the September 16 meeting (2pm) and August consumer credit (3pm). The Treasury sells $39 billion of 10-year notes in a reopening at 1pm.
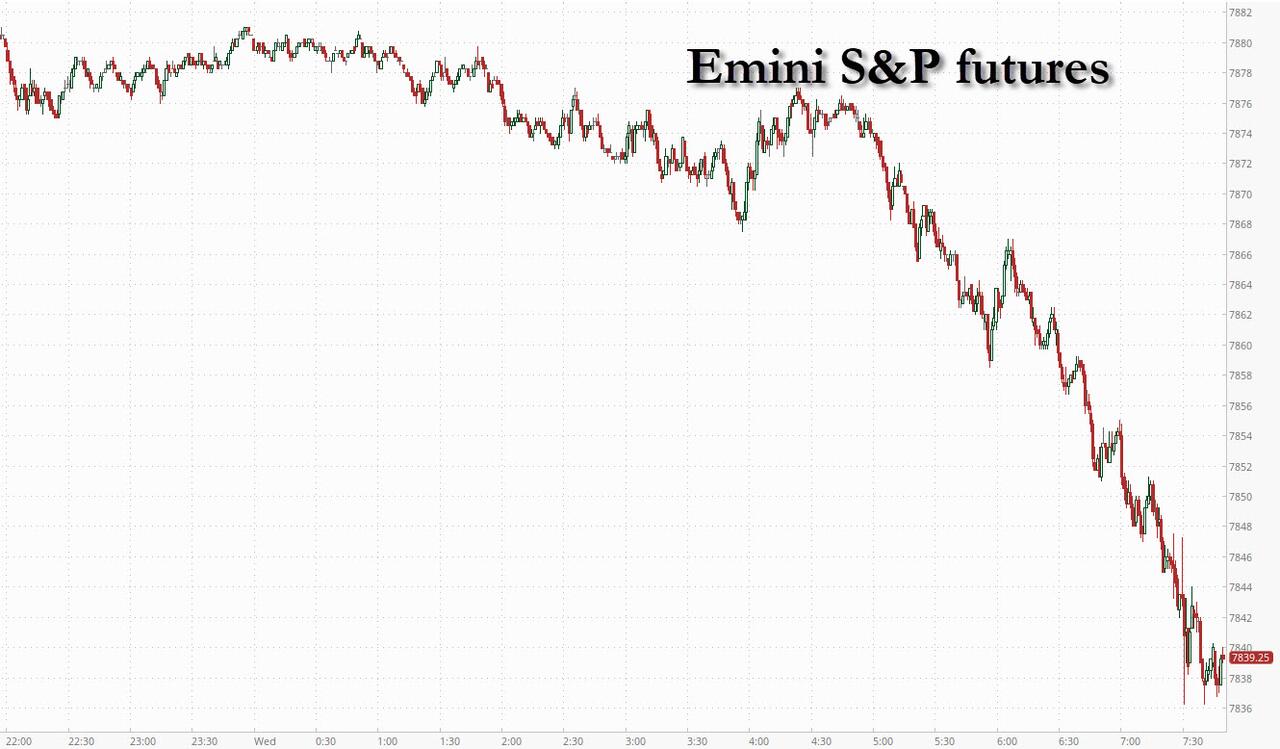
In premarket trading, Magnificent Seven stocks are mixed: Apple (AAPL) +0.6%, Meta Platforms (META) -0.1%, Alphabet (GOOGL) -0.5%, Nvidia (NVDA) -0.6%, Amazon (AMZN) -0.6%, Microsoft (MSFT) -0.7%, Tesla (TSLA) -0.8%

  • Constellation Brands (STZ) is down 3.6% after the maker of Modelo Especial and Corona Extra reaffirmed its comparable earnings per share forecast for the full year. The company also announced the acquisition of SpikedAde, a vodka-based drink brand.
  • Enphase Energy Inc. (ENPH) and SolarEdge Technologies Inc. (SEDG) shares fall 3% and 3.4%, respectively, after Deutsche Bank issued sell catalyst calls on the solar stocks on expected lower growth.
  • Flutter Entertainment shares (FLUT) rise 3% after Citi upgraded it to buy from neutral, saying recent share-price weakness on concerns over Brazil and September US sports results is overdone.
  • Neogen shares (NEOG) climb 13% after the life sciences firm reported adjusted earnings per share for the first quarter that exceeded Wall Street’s expectations.
  • NetApp Inc. shares (NTAP) are up 2.4% after Evercore ISI upgraded the computer hardware and storage company to outperform from inline, seeing a strong growth outlook.
  • Penguin Solutions shares (PENG) are up 4.2% after the semiconductor device company reported fourth-quarter results that beat expectations and gave an outlook that is seen as strong.
  • SailPoint Inc. shares (SAIL) are up 0.9% after Oppenheimer & Co. started coverage on the software company with an outperform rating and $30 price target, seeing strong growth potential related to AI.
  • Sigma Lithium shares (SGML) gain 5.8% as the company said it has resumed operations after a Brazilian court of appeals upheld its environmental licenses.
  • SpaceX (SPCX) shares fall 1.9% as it is in talks with banks and investors to raise $40 billion to buy chips from Nvidia Corp., people familiar with the matter said, in what would be among the biggest-ever debt financings for the AI buildout.
  • Taiwan Semiconductor Manufacturing Co. ADRs (TSMC) fall 2.2% as Elon Musk said his business empire will build and operate Terafab independently, quashing speculation about industry TSMC swooping in to run his ambitious chipmaking venture.
  • Vylor Inc. (VYLR -0.9%) was initiated with a sector weight rating, while Corteva Inc. (CTVA +0.7%) was upgraded to overweight as KeyBanc Capital Markets looks to earnings growth potential.
  • Webull Corp. shares (BULL) fall 30% after CNBC reported that the US House Select Committee on China is set to release a report on Wednesday that Webull is tied structurally to the government in China, raising national security concerns.
  • Zscaler shares (ZS) are up 0.5% with analysts positive on the security software company in the wake of an investor day event that increased confidence about its growth potential.

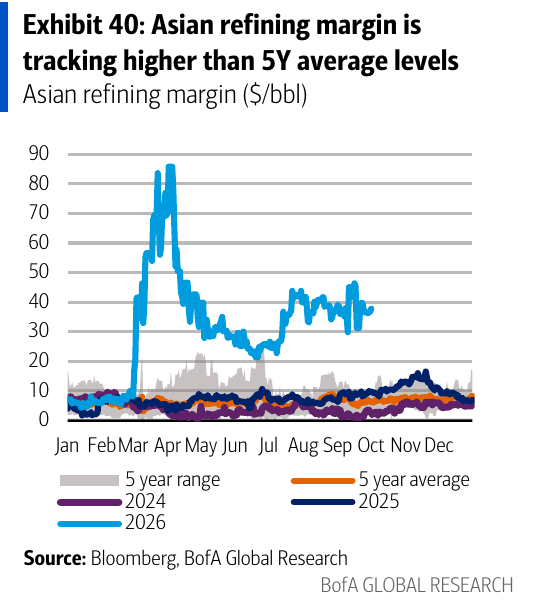
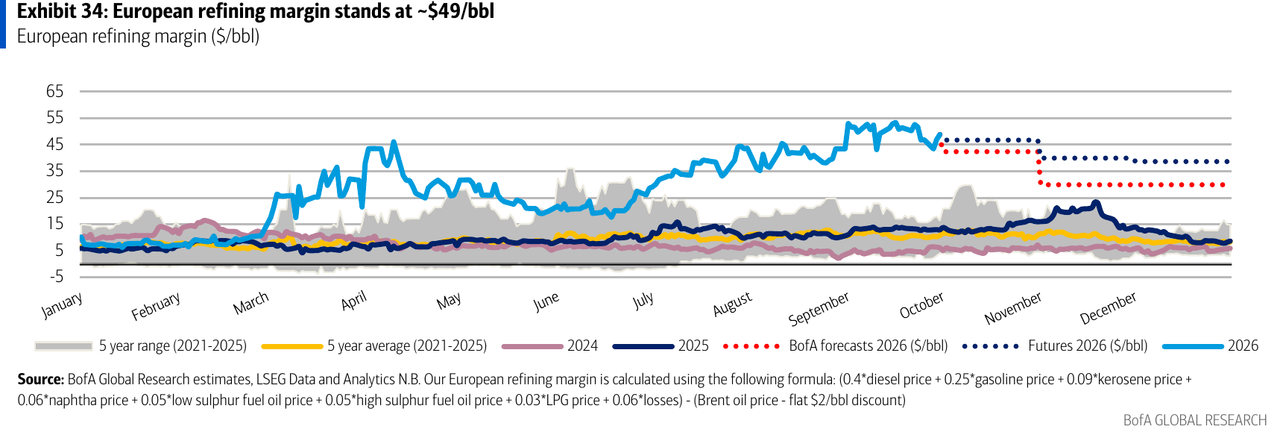
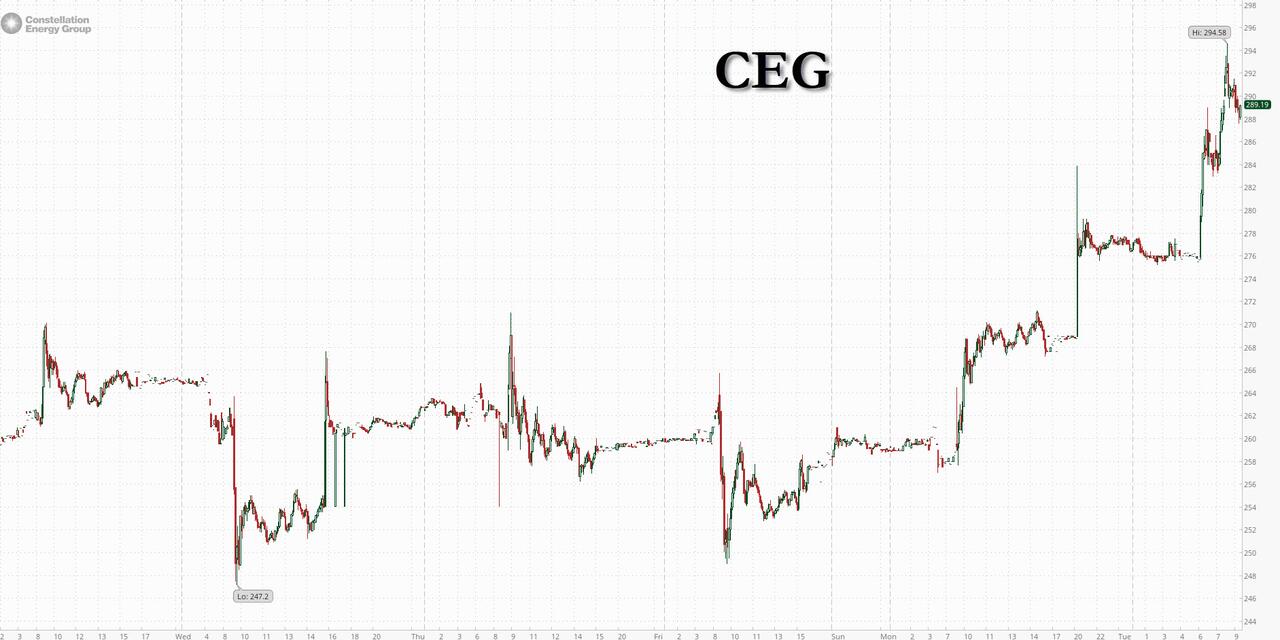
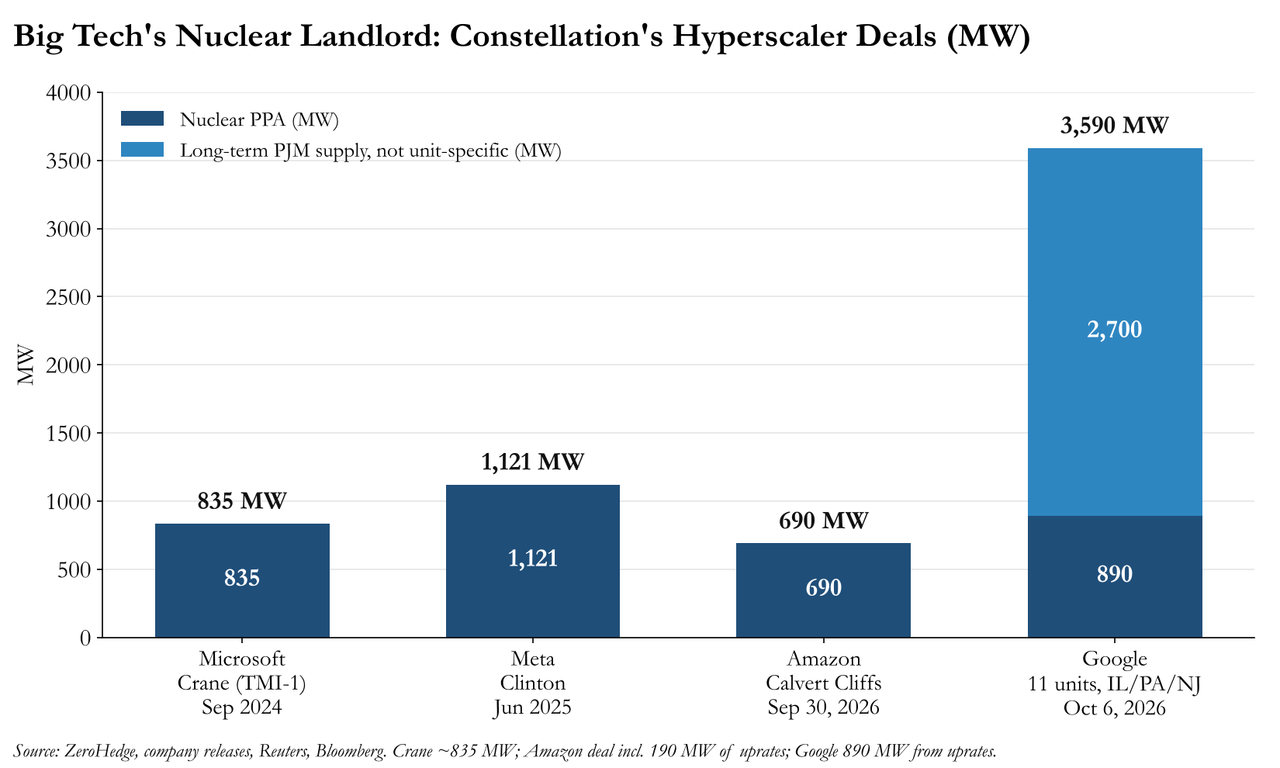
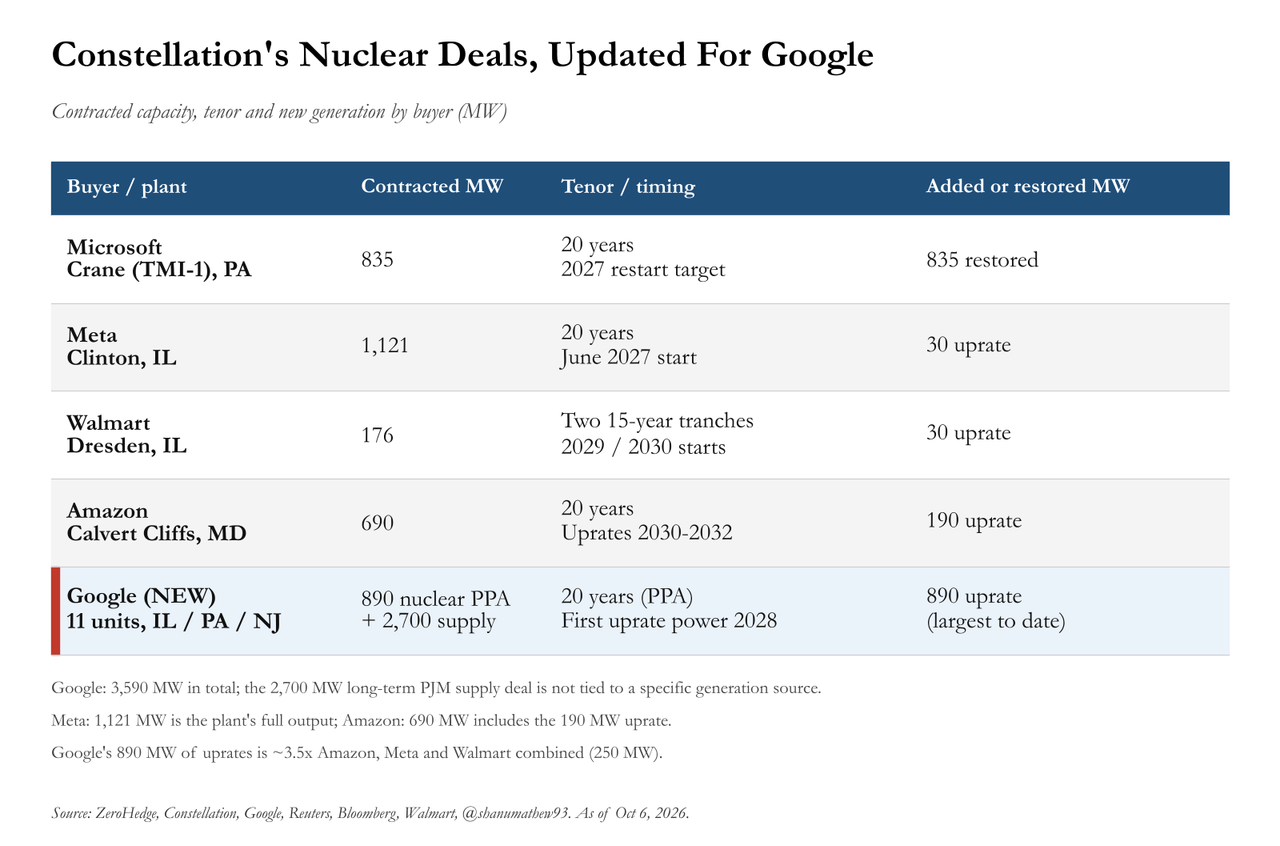
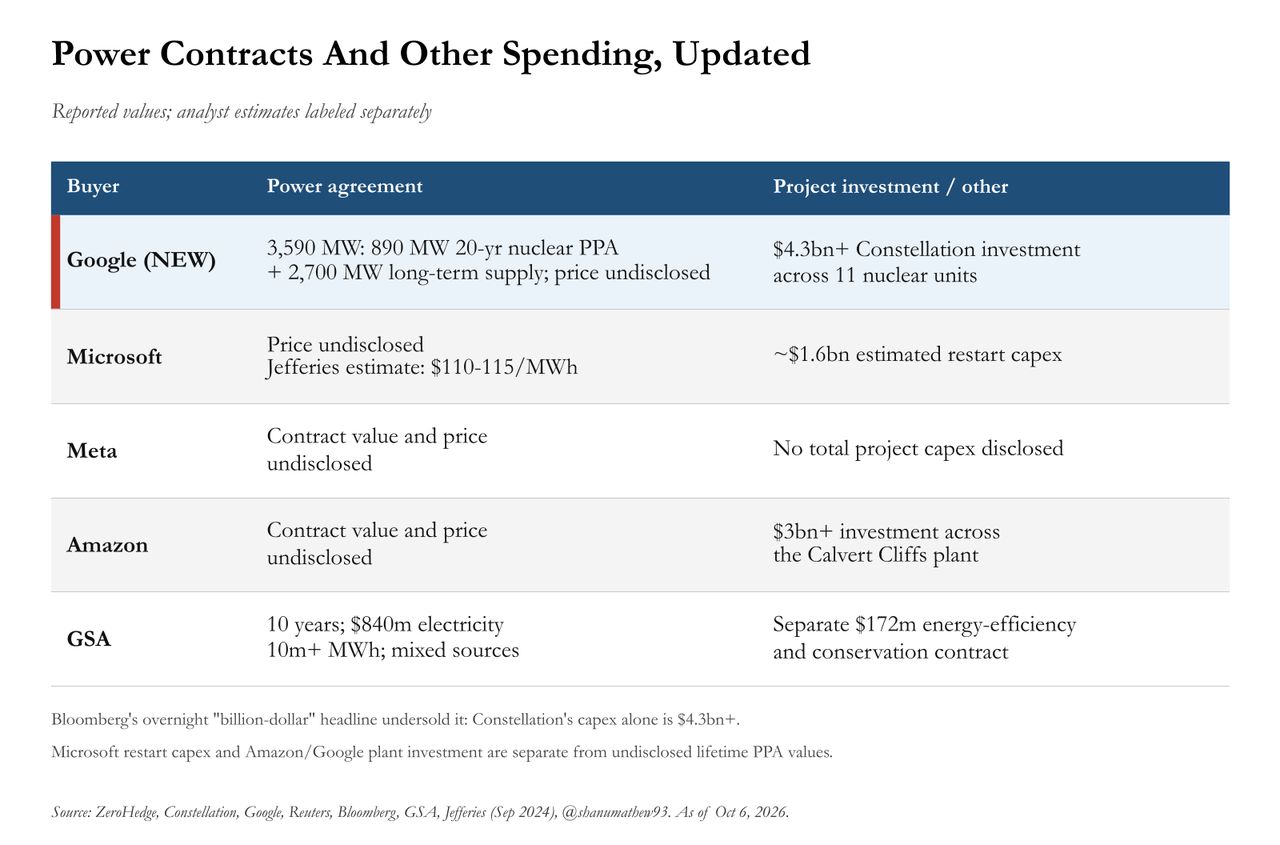
In other corporate news, Apple’s upcoming smart home devices will include a doorbell, thermostat, and other accessories developed through a partnership with LG Electronics. Shell expects to report strong results from oil trading in the third quarter as a squeeze on global fuel supplies drives refining margins to a record. HSBC is planning sweeping job cuts across its UK wealth management business as part of a broader push to use AI to serve affluent clients more efficiently, the FT reported. Frasers Group acquired an 8.8% stake in Under Armour. Affiliates of Energy Capital Partners are selling about $891 million of shares in Constellation Energy in an unregistered block trade, while Oaktree sold its remaining 6.2% stake in Torm. Black Hills will invest $1.8 billion serving a Google data center, CRH is buying aggregates operations in Denmark and Finland, and Porsche plans to raise prices of its top-end sports cars by an average of 20%.

A rally in stocks came to a halt and global bonds fell as mounting attacks on tankers in the Middle East pushed oil prices higher. "Stocks are taking a breather after closing at new record highs," Bloomberg's Neil Campling writes, noting that volumes, volatility and single stock dispersion remain low, with AI and earnings continuing to dominate the narrative. Meanwhile, the debate around an AI bubble is back: Temasek’s CIO said the unwinding of the AI trade is the biggest risk facing global markets along with inflation, Ray Dalio warned once more that AI is a “classic bubble” near bursting point, and the IMF sees the world facing risks from AI, a prolonged energy shock and record debt piles. Not that the market seems to care much: as we noted last night, stocks hit fresh record highs even as the 10Y hovers near its highest since 2002, and earnings concentration is getting absurd, with Micron and Nvidia alone set to deliver a third of Q3 earnings growth.

“Bond markets really worry about the outlook for fiscal policy, but the political reality is that the people on the ground are not ready to accept that,” she said.

“Extraordinary” AI-related earnings growth should keep certain major indexes relatively resilient despite rising yields, says Mark Cudmore of Bloomberg’s MLIV. Earnings growth expectations for the upcoming season have been ticking higher and are currently sitting at 24.5%. Barclays strategists agree that the AI boom remains a key earnings driver, but note that rising debt issuance and capital intensity are putting returns under greater scrutiny.

In other AI news, SpaceX is said to be in talks with banks and investors to raise $40 billion to buy chips from Nvidia (we covered the Apollo-led SPV debt here). Given that SpaceX is currently sitting on $100 billion of cash, the financing isn’t out of necessity, but speaks to the ongoing appetite for AI deals in credit markets. AMD is working with customers to optimize memory footprints as tight supplies persist, and Intel said it will continue to work with Elon Musk on Terafab.

For traders getting more nervous about AI names, BofA strategists recommend tapping equity derivatives both to benefit from the record rally and hedge against the fallout from a potential bubble. Traders are also looking to the upcoming earnings season to see whether profits can support valuations despite macro headwinds and whether the artificial-intelligence boom still has plenty of legs.

“It’s the period before earnings when there’s a bit of a lull, so markets can be pushed around easily,” said Guy Miller at Zurich Insurance. “The focus point is still around bond yields. There was relief yesterday but let’s be clear, nothing fundamental has changed.”
JPM's Market Intel desk under Andrew Tyler remains Tactically Bullish and thinks the market "may not be BULLISH enough into earnings": FactSet reports 26Q3 set a record for the largest number of positive pre-announcements, all 11 sectors are expected to show positive revenue and earnings growth, and consensus sees 12.3% revenue growth and 29.5% earnings growth with 15.0% margins (vs 52.3% EPS growth in Q2). The desk sees a broadening, but given where yields are, prefers a barbell with large-caps over small-caps and AI/Tech as the core. JPM also notes the bond market now prices a ~22% chance of an October hike and ~80% for December, down from 70% and 84% at the start of last week. JPM's Manish Sinha is less sanguine, flagging that the Equity Risk Premium is negative, which "effectively requires a meaningful earnings re-rating higher to justify taking equity risk," and that Momentum looks vulnerable either way.

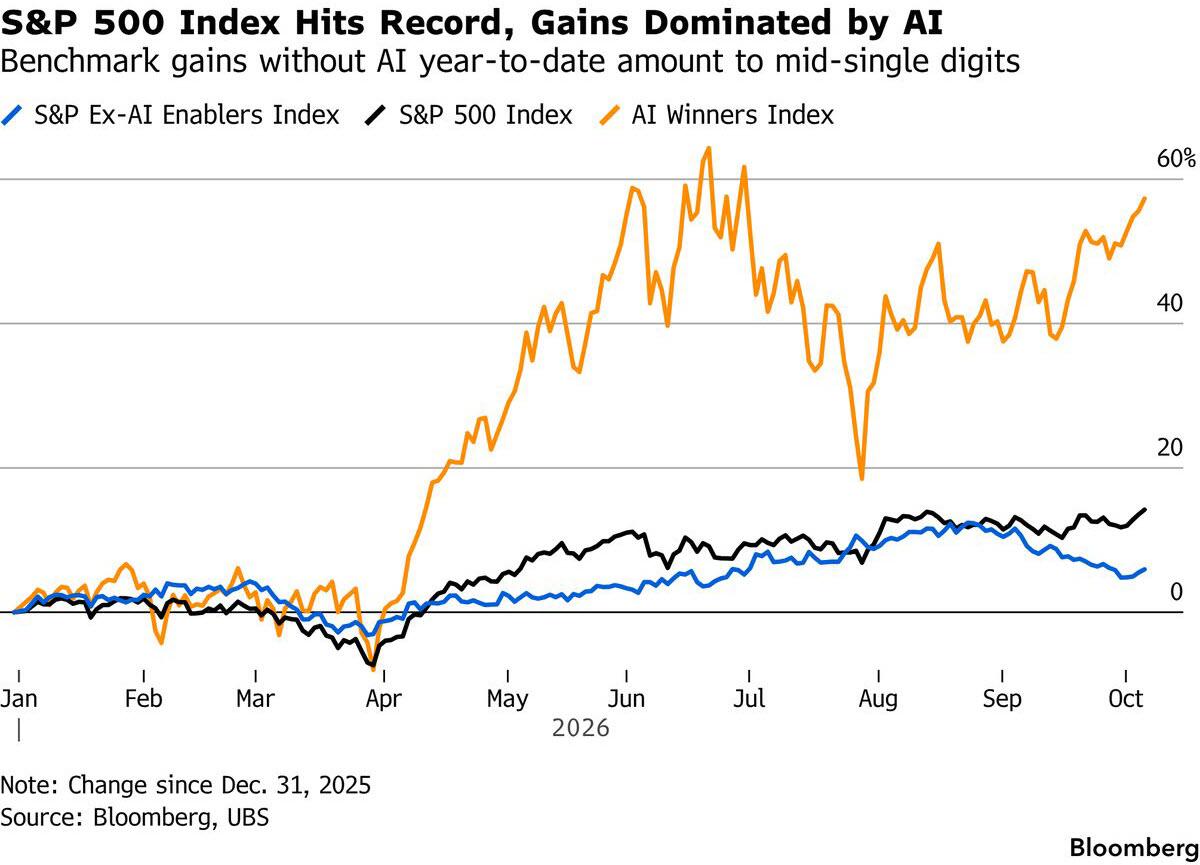
Goldman's desk is turning more cautious. US derivatives MD Shawn Tuteja writes that "the Tech / AI asymmetry has shifted. The macro is unequivocally more difficult, and the positioning within AI and large-cap tech no longer seem to be tailwinds." Since Aug 27, the SPX is +1.28% while the S&P ex-AI names is down 5.19%, and Mag 7 net exposure on GS Prime is near 22% of total US exposure, the highest since the start of 2022. His left-tail scenario: one where "the Fed must hike an excessive number of times to maintain credibility in the backend of the bond curve." In London, Goldman Delta One head Rich Privorotsky says today's tape "feels less like generic risk off and more like higher oil + higher real rates increasingly biting the duration sensitive parts of the tape," adding that "more leverage in the AI ecosystem is not exactly what the market wants to hear right now." Meanwhile, the GS cash desk notes hedge fund nets are approaching a 5-year low with market breadth at the lowest level since 2000 (no wonder traders keep paying up for protection).

On the macro front, FOMC minutes come later but may offer less insight into current thinking given Warsh’s desire to trust the data and with PCE revisions and jobs data having been released since the Sept. meeting. Speaking of inflation, oil is ticking higher as traders weigh increased flows through the Strait of Hormuz against a pickup in Iranian attacks against vessels. Elsewhere, the EU is preparing safeguard measures to limit imports of Chinese hybrid vehicles into the bloc.

France is back on the tape: the spread between French and German 10-year yields widened as much as 10bps to 138bps, unwinding Tuesday's Le Pen relief rally, as investors continue to price in heightened fiscal pressure around budget negotiations (and as Goldman warned, the "Le Pen bounce" was not to be trusted). ECB's Moulin said the situation on France’s bond market is complicated and serious, but doesn’t warrant intervention from Frankfurt. Not everyone is panicking:

“Unlike previous episodes of severe sovereign stress in the euro area, we do not see evidence of broader financial contagion,” ABN Amro senior rates strategist Larissa de Barros Fritz wrote. “We do not expect OAT-Bund spreads to reach the 200bp+ levels seen during past Italian stress episodes.”

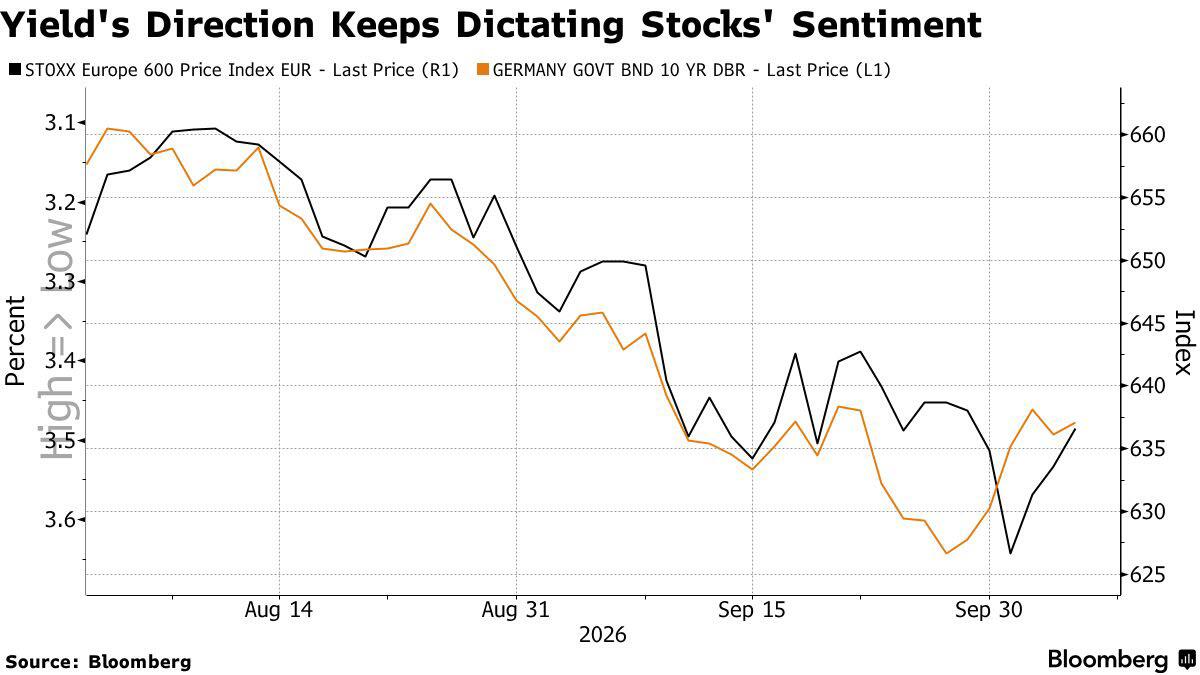
In Europe, the Stoxx 600 is down 0.4% at 633.64, ending a three-day run of gains as oil prices climbed and bond yields resumed their rise, with 351 members down and 233 up; Euro Stoxx 50 is down 1.1% and the DAX 0.9%. Telecoms, autos and retail lead, with carmakers rising as much as 1.75% on the EU's planned cap on Chinese hybrid imports, while banks, tech and utilities lag, with French lenders among the worst performers. Pennon plunged as much as 20% to the lowest since 2004 after a larger-than-expected £550m rights issue. Here are the biggest European movers:

  • Remy Cointreau shares advance as much as 7.5%, the most since June, after the French beverages maker held a pre-earnings call that analysts said offered reassurance on the sales outlook and US trends.
  • Europe’s carmakers advance as the European Union prepares a limit on imports of Chinese hybrid vehicles into the bloc. The Stoxx 600 Auto & Parts Index gained as much as 1.75%, leading gains among sectors.
  • NCC shares gain as much as 7.7%, the most since Feb. 6, after the Swedish construction company agreed to sell its Industry business at an enterprise value of SEK8.2b.
  • ALK-Abello shares gain as much as 3.4% as Nordea upgrades the Danish pharmaceutical firm to buy, arguing it has the potential to return to substantial sales growth from 2028 onward, following an expected dip in 2027 due to German medication rebate reform.
  • Forvia climbs as much as 11% following a double-upgrade to buy at BofA, which removes the stock’s only negative analyst rating, with room seen for the auto-tech supplier to re-rate after weak performance in the shares year to date.
  • Pennon shares fall as much as 20% to the lowest level since October 2004 after a £550m rights issue that was larger than analysts expected. Analysts also flag the rebased dividend and uncertainty over returns as limiting the potential for a re-rating of the South West Water owner.
  • BE Semiconductor shares drop as much as 8.4% after UBS downgraded the stock to sell from buy, citing a slower adoption of hybrid bonding among memory chipmakers due to a supply crunch.

Asian stocks fell for the first time in three days, led by tech, as the earnings optimism that drove US stocks to records failed to carry over to the region. The MSCI Asia Pacific Index dropped as much as 0.9% with SK Hynix, TSMC and Alibaba among the biggest losers; SK Hynix slumped ahead of the expiry of a lockup in its ADRs on Oct. 8. South Korea's Kospi led declines, closing down 2.0% at 6,803.90, with Goldman's Korea desk noting foreigners sold $1.94 billion (net sellers for an 8th session) while retail bought $1.91 billion, and Samsung's preliminary results due tomorrow. Japan's Nikkei fell 0.9% to 70,035.71, just about holding the 70,000 level as investors booked profits, with beer makers lower after the Fair Trade Commission started investigating them over suspected price fixing; the Topix fell 0.5%. The Hang Seng slid 0.6%, Taiwan's Taiex fell 0.1% and Australia's ASX 200 was flat. Mainland China remains closed for Golden Week and reopens Thursday. Southeast Asian banks sold off after JPMorgan warned surging long bond yields will hurt third-quarter earnings, while India's RBI hiked rates by 25bps to 5.50%, its first hike in nearly four years.

“There’s a sense that Asian markets are starting to lose some of the relative momentum they enjoyed earlier,” said Tim Waterer, chief market analyst at KCM Trade. “After a period of outperformance, the lack of fresh catalysts combined with still-elevated oil and bond yields is leaving the region looking a little tired.”

In FX, the Bloomberg Dollar Spot Index rose 0.3%, approaching its highest since June, with the dollar stronger against all G10 peers and the DXY trading in a 101.88-102.32 range. EUR/USD fell to 1.1180, closing in on the 1.1161 low hit earlier in the week (the lowest since May 2025), as French fiscal angst pushed the euro to a 16-month low against the pound. USD/JPY edged up to around 158.5 after a report that Japan may be considering another supplementary budget, though PM Takaichi said the government will review policies, revenue and spending if rate moves diverge from expectations. GBP/USD slipped 0.2% to 1.3247 as gilts sold off.

“Markets are unlikely to welcome the prospect of a second supplementary budget, regardless of its size, given earlier guidance that they are no longer planned,” said Wei Liang Chang, macro strategist at DBS Bank. “The yen and JGBs may trade slightly weaker as investors await details.”

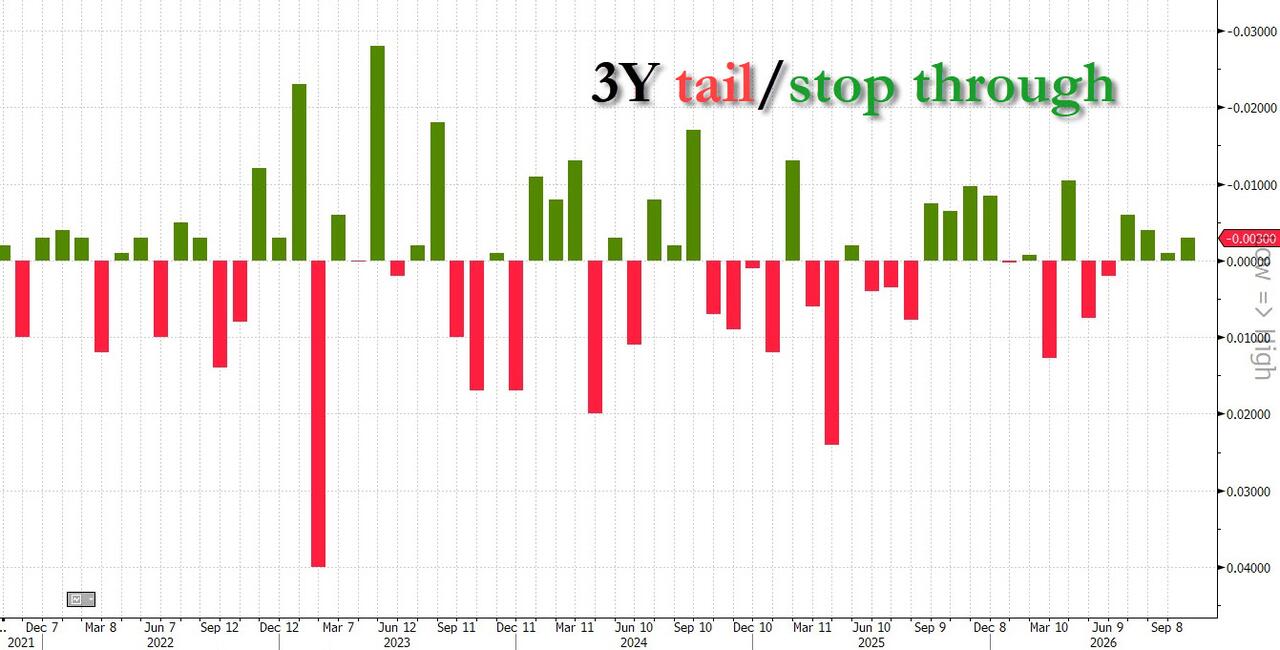
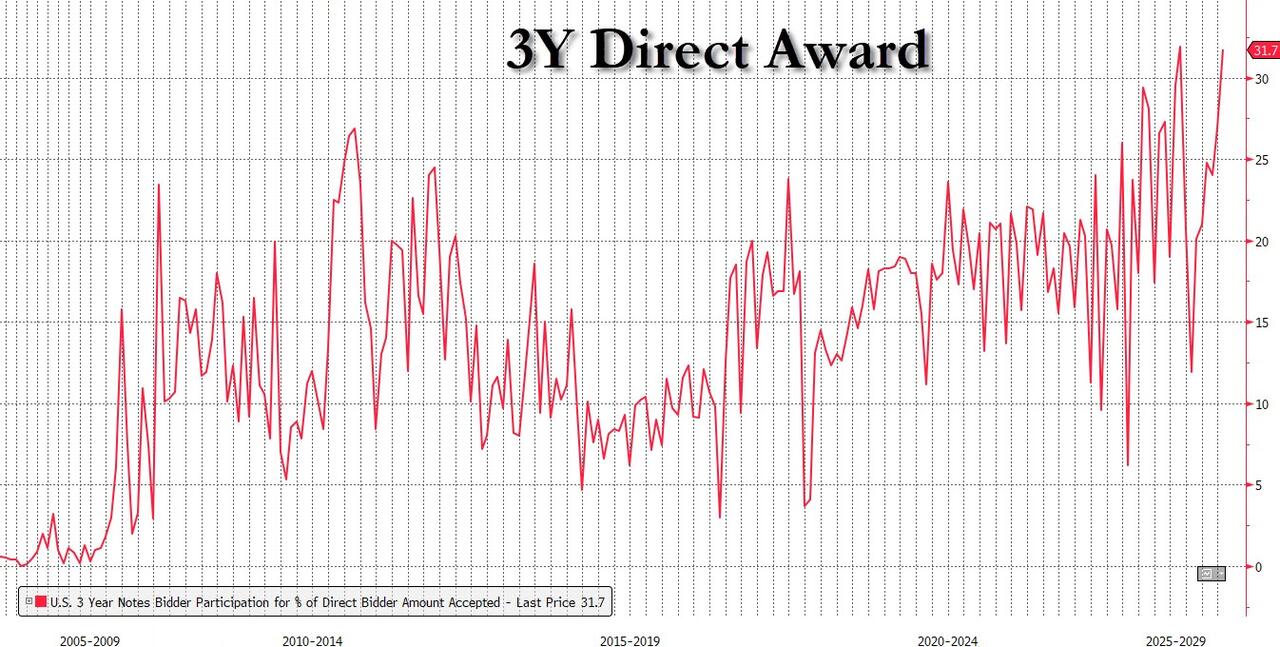
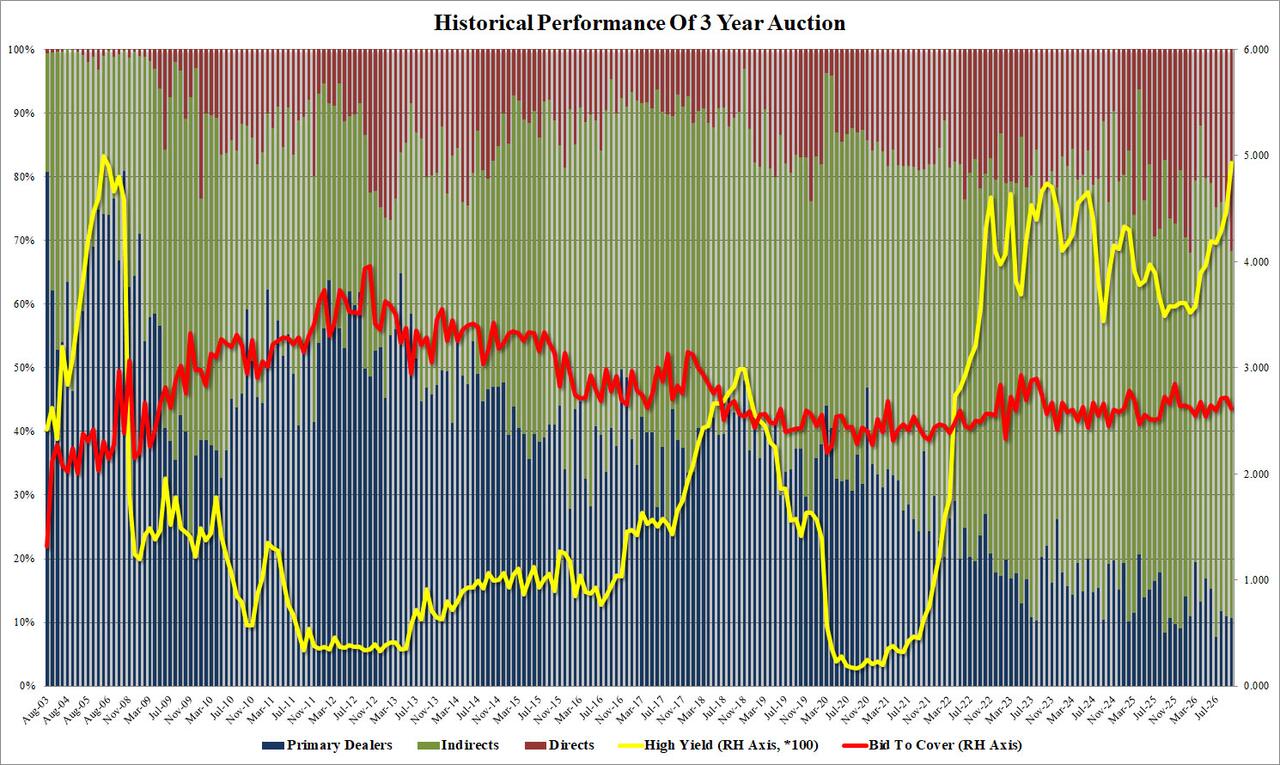
In rates, Treasuries' long end leads the selloff into the early US session, with 30-year yields cheaper by 5bps on the day at 5.70%, the highest since 2002, and peeking through Monday's highs. Yields are 1bp to 5bps higher across the curve, with 2s10s and 5s30s steeper by 4bps and 2bps; the 10-year trades around 5.325%. Gilts lag by an additional 4bps in the 10-year sector, with UK 30-year yields up 10bps to 6% (round number, nobody panic), while bunds slightly outperform and OATs give back all of Tuesday's gains; a new 2033 Bund auction drew a dire 1.42x cover with 52% retained. Duration supply is a factor: the $39 billion 10-year reopening at 1pm follows Tuesday's solid $58 billion 3-year sale, which stopped 0.2bp through, and the 10-year WI around 5.33% is ~50bps cheaper than the September reopening, which stopped 1.5bps through. The IG dollar issuance slate includes a couple of deals after four borrowers priced $4.25 billion on Tuesday. FOMC minutes from the September 16 hike land at 2pm.

“Instead of blaming bond vigilantes, deficits, Japan, fiscal dominance, erosion of central bank independence, the driver of higher rates is central banks delivering rate hikes,” wrote Bank of America rates strategist Ralf Preusser, adding that “term premium explains the entirety of the 10y yield move in US, UK, Japan, Australia and Canada” since the September central bank meetings.
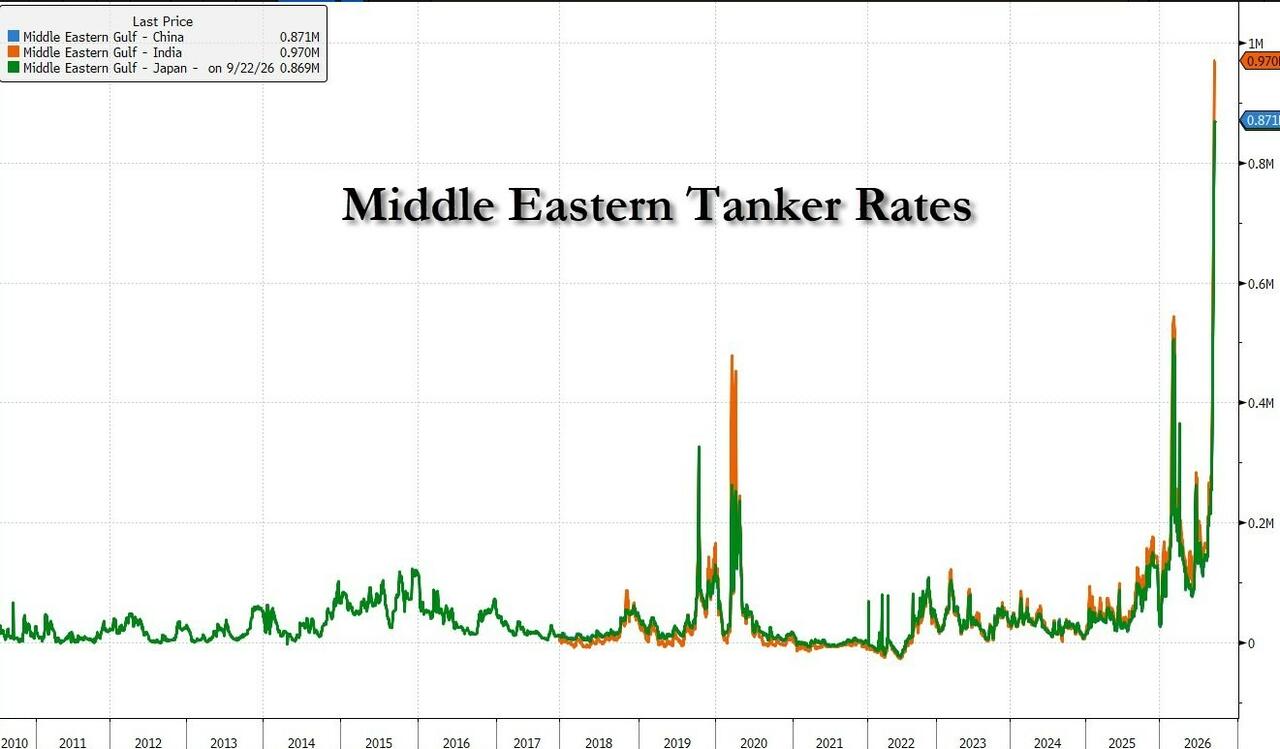
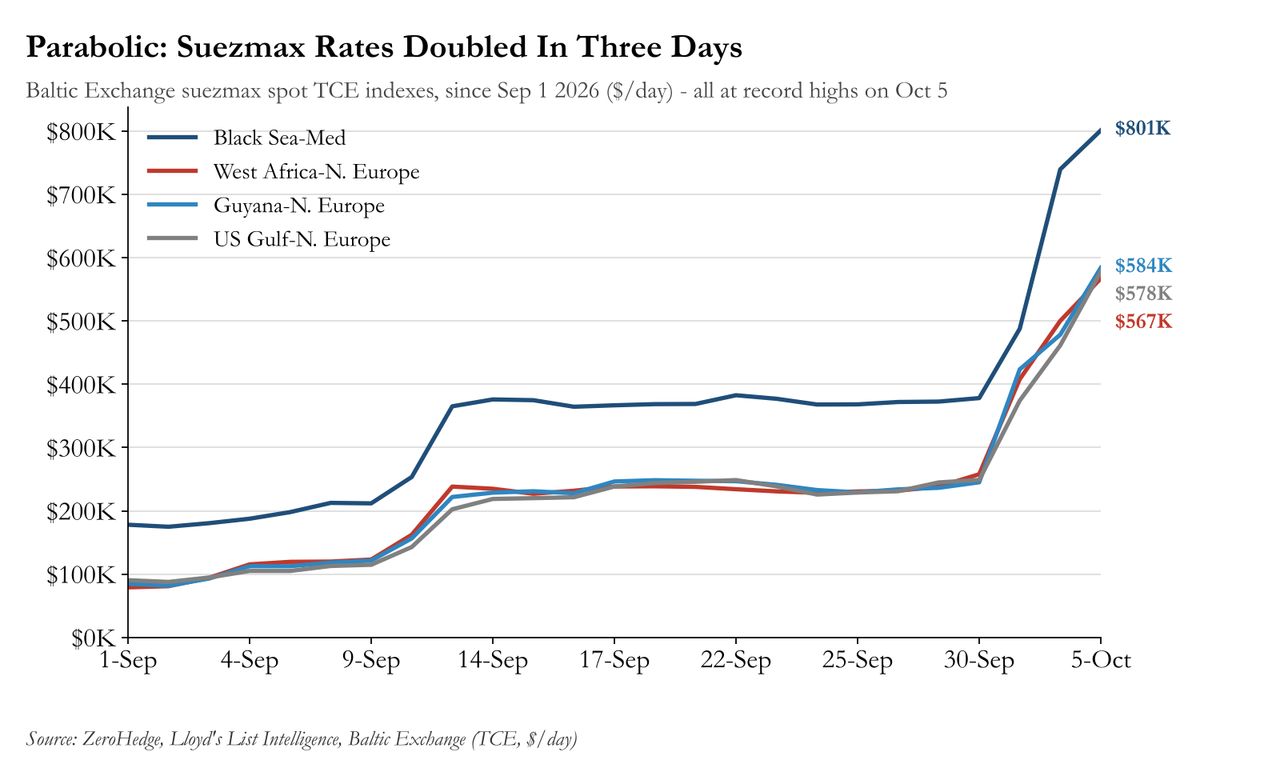
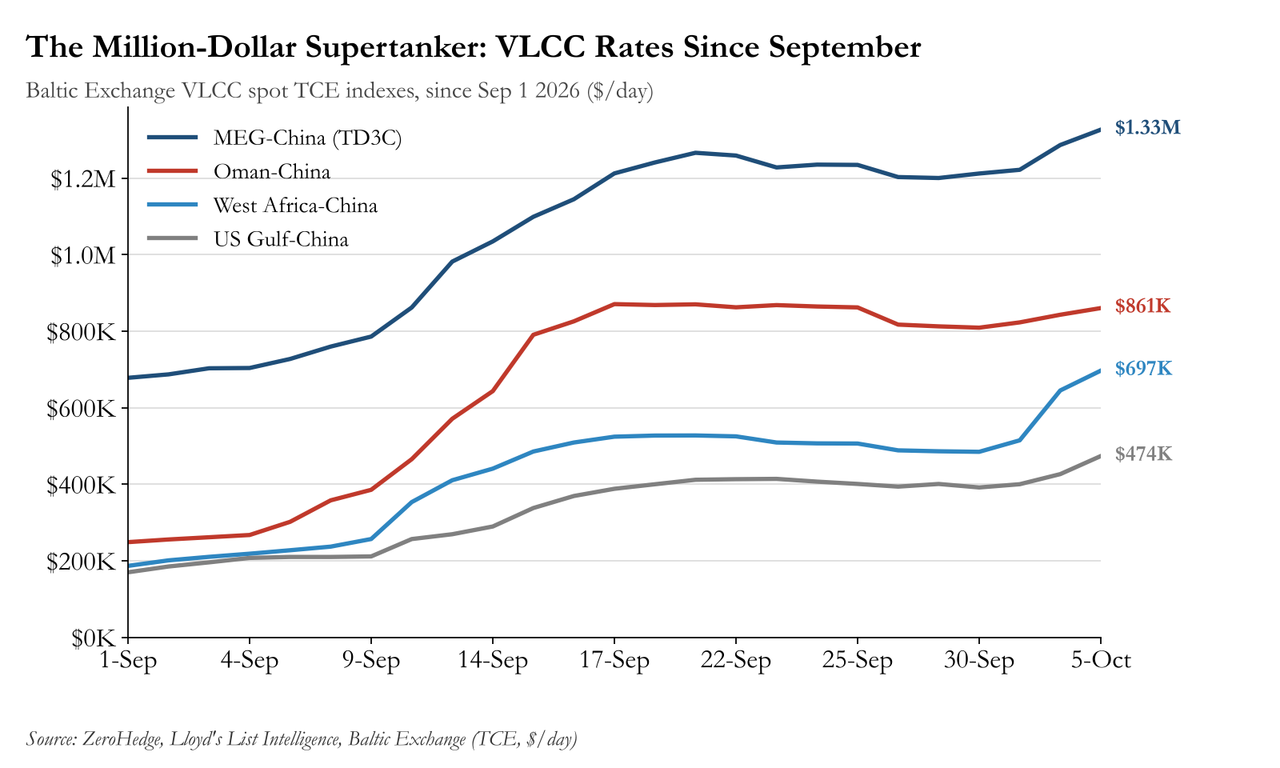
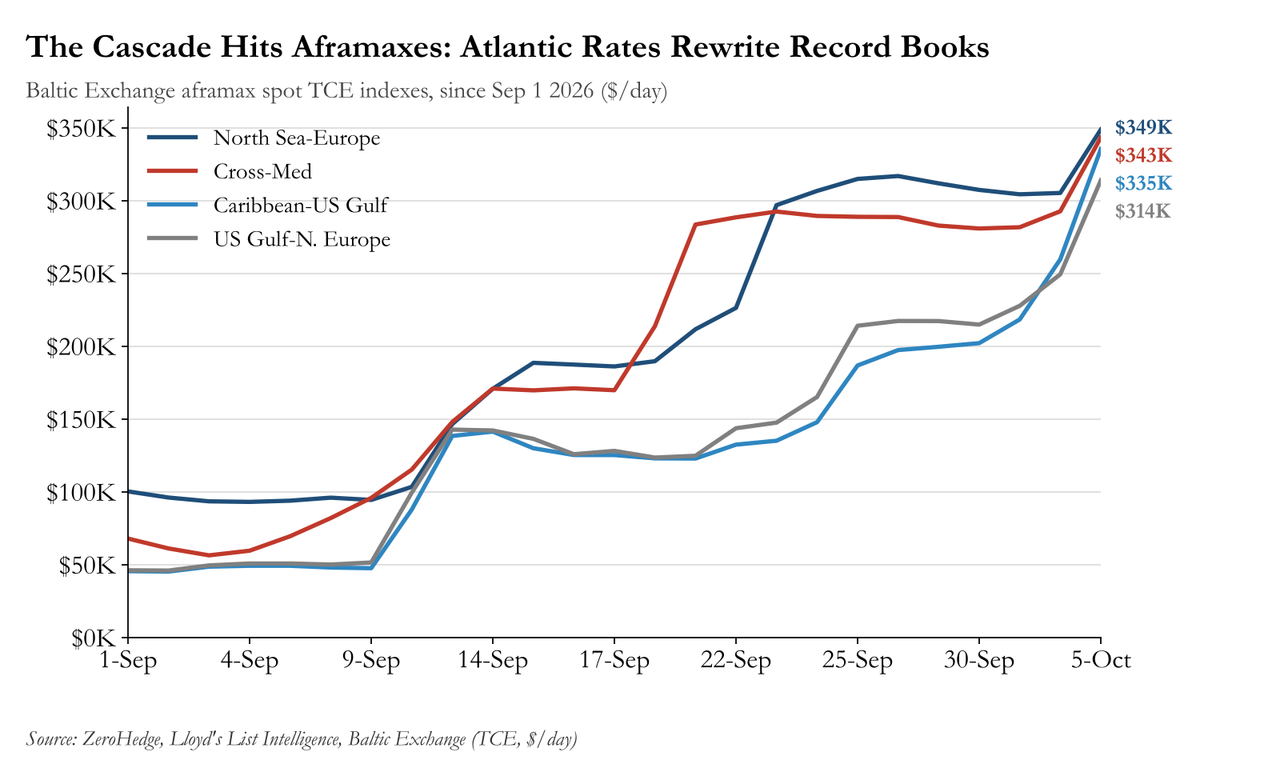
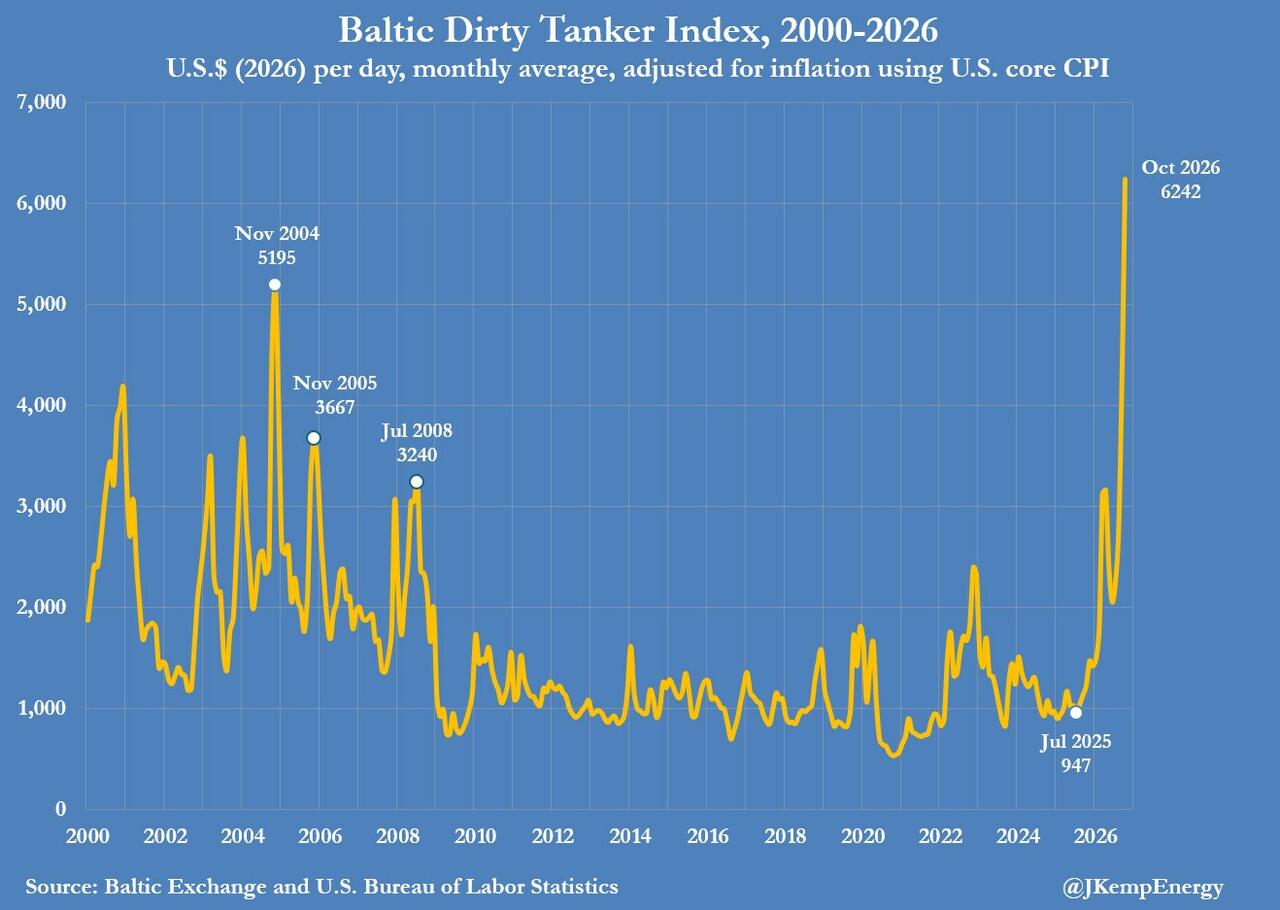
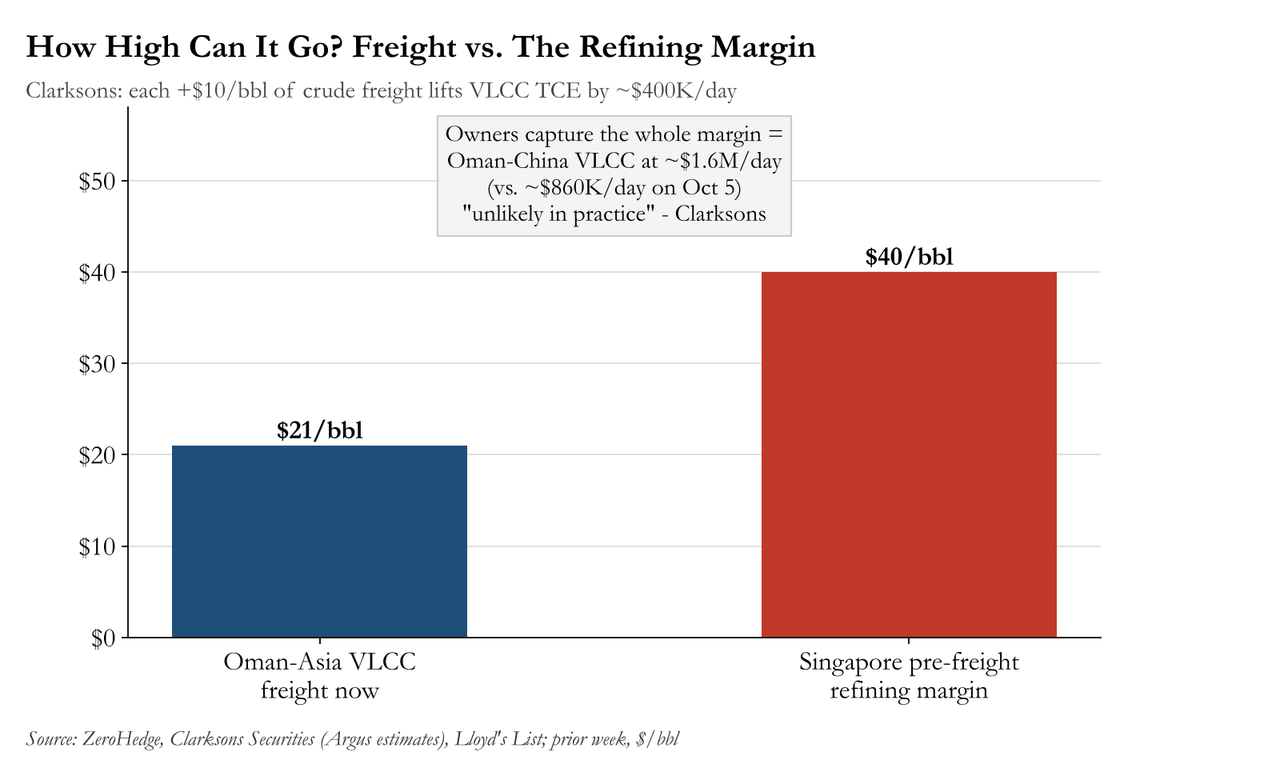
In commodities, WTI for November delivery gained 0.7% to $90.02 and Brent for December rose 1.4% to $101.94 as of 6:52am, in choppy trading (WTI ranged $89.33-90.61, Brent $100.72-102.06) as traders weigh a pickup in Iranian attacks on vessels in Hormuz against resilient Middle East flows; UK maritime authorities logged nine attacks in the strait this month, already half of September's count. Vitol's CEO says the crisis has entered a new phase as buyers struggle to secure tankers (as we discussed here, every crude freight index is at a record), while EU states expect the G7 emergency release of up to 100 million barrels to merely enact prior commitments; the IEA holds an informal meeting on releasing oil and diesel reserves. Shell is evacuating non-essential workers from several US Gulf assets ahead of Tropical Storm Isaias. Dutch TTF rose to €77.37/MWh. Spot gold fell from $4,170 to a $4,117 low and silver from $61.50 to $60.34 as the dollar firmed, while 3M LME copper is stuck in a $14,339.60-14,445.85 range.

US economic data slate includes MBA mortgage applications (7am, -4.2%, 30-year rate 7.49%), September NY Fed 1-year inflation expectations (11am), FOMC minutes (2pm) and August consumer credit (3pm). Fed speaker slate: The Treasury sells $75 billion of 17-week bills (11:30am) and $39 billion of 10-year notes (1pm).

No significant earnings are expected before the open; Costco reports September sales later in the day and Levi Strauss and Applied Digital report after the close.

Market Snapshot
Top Overnight News

  • Japan’s Sanae Takaichi said the government may review spending and revenue plans if bond yields move unexpectedly. BBG
  • The EU’s preparing measures to limit imports of Chinese hybrid vehicles into the bloc, people familiar said. One option is to impose a levy on imports above a certain volume. BBG
  • India’s central bank raised interest rates for the first time in more than three years as the Middle East conflict kept energy prices high, hurting the rupee and fueling inflation fears. The Reserve Bank of India’s monetary policy committee voted unanimously to raise its benchmark repo rate by 25 basis points to 5.50%, ending a pause spanning four consecutive meetings. WSJ
  • According to the Saudi aviation authority, Saudi Arabia’s airports in Jazan and Najran were targeted in two attacks, as hostilities between Yemen’s Iran-backed Houthis and the kingdom grow. CNBC
  • Leading oil executives warned that the world is running out of stopgaps to manage the impact of the Iran war as the conflict extends into an eighth month. Producers and consumers have pulled virtually every lever available to adjust to the diminished flows, including reductions in demand and large releases from strategic petroleum reserves. BBG
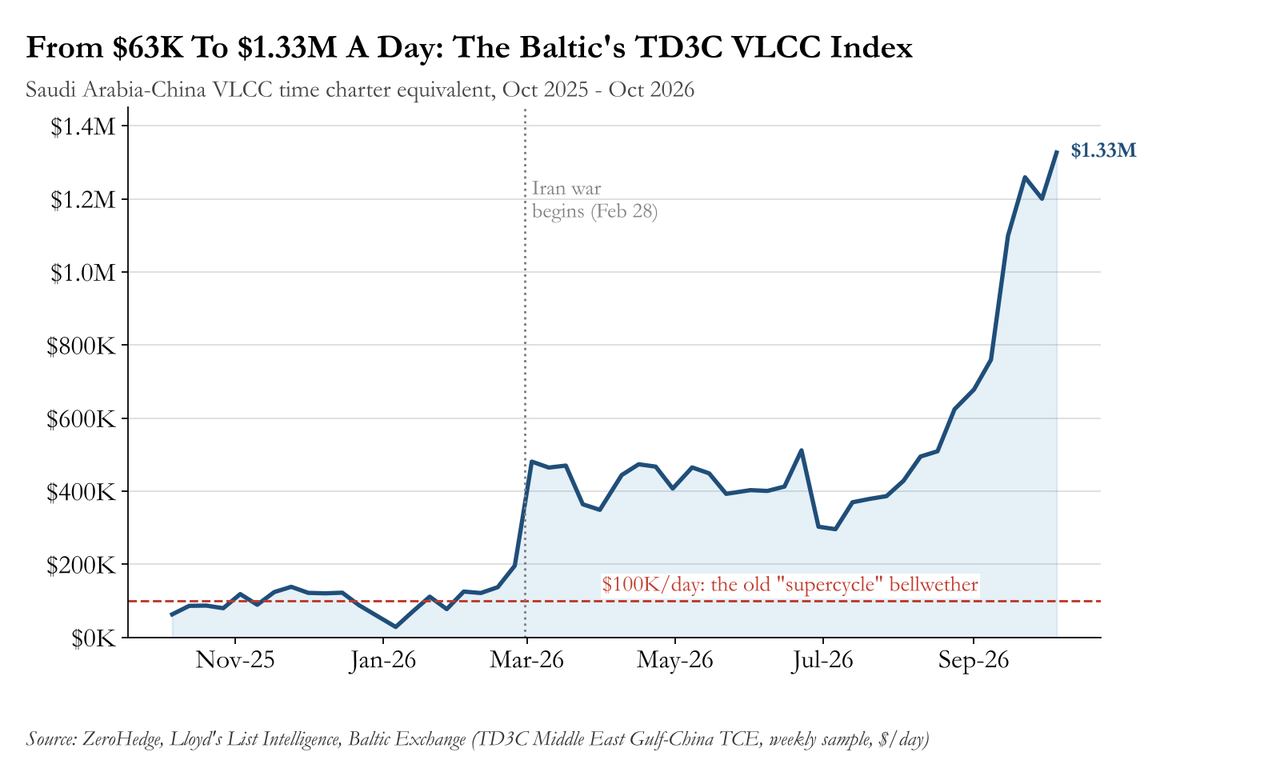
  • The global energy crisis triggered by the Middle East conflict has entered a new phase because of a shortage of tankers to move crude around the world, according to the head of the world’s largest independent oil trader. Vitol chief executive Russell Hardy said that while more oil was now flowing out of the Gulf, there was a fresh bottleneck as buyers struggled to secure ships. FT
  • The US is gearing up for another quarter of bumper corporate earnings spurred by lavish spending on the AI build-out. The robust growth should help Wall Street shrug off worries about the durability of the AI trade against the backdrop of rising borrowing costs but may do little to allay concerns about how reliant the record-high stock market has become on a small group of technology names. FT
  • The French government desperately needs a return to strong growth if it is to contain its rapidly rising debts. But uncertainty about whether the country can fix its finances has itself started to weigh on economic activity. France only narrowly avoided a recession in the second quarter, as activity stagnated after extreme heat hit agricultural output and the energy price shock from the war in Iran continued to squeeze households and businesses. WSJ
  • SpaceX is in talks to raise $40 billion to buy Nvidia chips, people familiar said, in one of the biggest-ever debt financings for AI buildout as the borrowing binge accelerates. BBG
  • Iran has increased the pace of attacks on tankers in the Strait of Hormuz in recent days, just as oil shipments through the world’s most important energy chokepoint approach prewar levels. BBG
  • US 30-year yields rose 5bps to 5.7%, the highest since 2002, while 10-year yields climbed 4bps to 5.3%; traders extended their short bets against US government bonds. BBG
  • Germany’s industrial production for Aug came in ahead of expectations at +2% M/M (vs. the Street +0.5%). BBG
  • Taiwan’s CPI overshoots the consensus at +2.73% headline (vs. the Street +2.4%) and +2.52% core (vs. the Street +2.45%). BBG
  • Iraq devalued its currency by about 13% versus the dollar as Hormuz disruption hits oil exports. BBG
  • The Dutch government plans to cut its stake in ABN Amro to 10.5% from 20.7%. BBG
  • US VP Vance said that Iran must make a "meaningful" reduction in its nuclear enrichment capacity to satisfy US demands and end the war. RTRS
  • US officials have formally requested additional information from Russia and are coordinating with governments around the world: State Department spokesperson
  • France's government is willing to bypass parliament to pass billions in cuts. WSJ
  • US equities have decoupled from the ex-AI market: since Aug 27, the SPX is +1.28% while SPX ex-AI is -5.19%, with the rolling 30-day gap near its widest since January 2023. GS
  • FactSet reports 26Q3 set a record for the largest number of positive pre-announcements, led by Tech, Industrials and Healthcare. JPM

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly negative, with the region failing to take inspiration from the gains on Wall St, where the S&P 500 and Nasdaq printed fresh all-time highs, while the sentiment soured overnight amid a rebound in oil and yields. ASX 200 struggled for direction and was flat for the session in the absence of any major catalysts and tier-1 data. Nikkei 225 retreated with investors booking profits following the recent rally in the index, which just about held on to the 70,000 status, with participants also reflecting on Labour Cash Earnings data, which decelerated but still topped forecasts. Elsewhere, there was pressure seen in brewers including Asahi on reports that Japan's FTC is probing Japan's four major breweries over suspected price fixing. KOSPI underperformed in choppy trade with the index weighed on by weakness in SK Hynix, while Samsung Electronics was indecisive ahead of its preliminary earnings results tomorrow. Hang Seng conformed to the downbeat mood amid tech-related weakness and continued absence of mainland participants, who will be returning from the week-long holiday closure tomorrow.

Top Asian News

  • Japanese PM Takaichi said the government will review policies, revenue and spending if interest rate shifts diverge from expectations.

European bourses (STOXX 600 -0.6%) are broadly lower, giving back the gains seen earlier in the week, but have rebounded slightly in recent trade amid the recent downside in energy benchmarks. No clear driver has been seen to explain this reversal. Sectors lack a clear bias. Telecoms top the sector pile, with Autos and Retail rounding out the sector gainers. Banks reside at the bottom of the sector pile, with Tech and Utilities rounding out the sector laggards. European autos are finding some support this morning, after Bloomberg reported that the EU is preparing a temporary import cap on Chinese hybrid cars. The safeguards by the EU will be welcomed by domestic manufacturers, as Chinese hybrid sales make up 25% of total sales in the bloc. Further in the report, the source added that the Commission plans to use hybrids as a test case, and if successful, would replicate it in other sectors. US equity futures are lower, with the ES outperforming as it hovers around the unchanged mark. Constellation Brands, the Corona owner, fell after hours despite upbeat Q2 metrics as they highlight softer underlying beer demand and a reduced operating margin outlook.

Top European News

  • UK Chancellor Healey held a scheduled meeting with economists from primary dealer firms in the Gilt market, with the purpose of the meeting being to share views on global and UK economic prospects.
  • UK Chancellor Healey is considering a major intervention to cut energy bills for poorer households at this month’s budget, according to The Guardian.
  • UK Labour Party is to shelve GBP 800mln of planned military housing repairs until at least 2029, according to The Times.
  • France's government is willing to bypass parliament to pass billions in cuts, according to the WSJ.
  • ECB's Moulin said the situation in the bond market is "complicated", but stated that France is not in an economic crisis yet. The French economic situation is serious but "we can act", while adding that the ECB is not there to respond to nations' budgetary problems.
  • Germany’s foreign trade association raised its 2026 export growth forecast to 1%.

FX

  • USD is stronger against most G10 peers this morning, with strength facilitated by higher energy prices and elevated yields. JPY holds towards the top of the pile, whilst the EUR underperforms.
  • DXY is firmer this morning and trades within a 101.88 to 102.32 range; strength has been facilitated by higher energy prices and continued pressure in the EUR. US-specific news flow has been lacking, but attention later will be on the FOMC Minutes. It will be eyed to see how members view the future path of tightening. Elsewhere, geopolitical updates remain light. The usual rhetoric from Trump on continued oil flows through the Strait, and ongoing strikes between Saudi Arabia and the Houthis remain the key drivers.
  • EUR is once again on the backfoot this morning, after finding some reprieve in the prior session. To remind, French fiscal woes appeared to ease as Le Pen provided markets with a friendly alternative budget, but failed at expressing how she would achieve it. Therefore, it was mentioned in yesterday’s FX “Market Analysis” that the EUR pressure would likely return – and it has come alongside a bout of USD strength. French fiscal concerns have re-emerged; for reference, OATs are underperforming today, and the OAT-Bund spread has widened back towards 138bps (vs yesterday’s close at 130bps).
  • JPY outperforms vs peers, but still resides flat/slightly lower. Strength which comes despite widening yield differentials, and after Yomiuri reported that Japan is considering a second supplementary budget. Sticking with the fiscal side of things, PM Takaichi said that she would review policies and spending amidst elevated yields – which could help ease debt concerns within the region. Nonetheless, JGBs remained fairly unchanged overnight, which means that the JPY action may be subject to other factors. That could potentially be the region’s Labour Cash Earnings data, which showed a deceleration but still printed firmer-than-expected. Overall, a report which keeps BoJ hikes on the table by year-end.

Central Banks

  • RBI hiked the Repurchase Rate by 25bps to 5.50% via unanimous decision, and adjusted its policy stance to calibrated tightening from neutral with four out of six MPC members in favour of stance change, with the RBI Governor saying it implies a "milder form" of a hiking cycle. The RBI said its FY27 inflation forecast while also lifting its real GDP growth.
  • BoJ Board Member Sato said she agrees on the need for a gradual adjustment to interest rates and does not think there should be a pre-set pace of rate hikes, while she added the BoJ must decide monetary policy independently in a way that is consistent with the administration's proactive fiscal policy. Sato also noted risks to the price outlook are skewed to the upside due to rising oil costs from the Middle East conflict, according to Kyodo.
  • ECB's Dolenc said that the current ECB rate level ensures flexibility for the central bank's upcoming rate decisions.

Fixed Income

  • A bearish start to the day, as renewed energy upside lifted fixed income overnight. Magnitudes are in-fitting with Tuesday’s action, in the sense that OATs outperformed yesterday and currently underperform today.
  • Within Europe, for today, the focus is more on Germany into the CDU/CSU-SPD coalition meeting at around 15:30BST today. A meeting that is in focus after Bild reported that the Grand Coalition is looking to get agreement from SPD to outline a deadline for pension reform.
  • In general, EGBs are under pressure given the energy move. Bunds lower by about 10 ticks in 120.45-90 parameters, while OATs underperform at a 108.86 low, down by essentially a full point. A move for OATs that has unwound all of yesterday’s upside, and thus the OAT-Bund 10yr yield spread is wider today, at 138bps currently.
  • It is worth noting that a new 2033 Bund auction was met with dire demand, with b/c at 1.42x; more pertinently was a massive retention of 52%, indicating a high amount of caution for EGBs.
  • Ex-OATs, Gilts are underperforming. Hit by the mentioned energy move and the usual somewhat outsized reaction seen in Gilts to this. Additionally, fresh budget speculation regarding energy relief is factoring; while welcome for consumers, it adds to the funding pressure that Chancellor Healey is already under. Lower by 55 ticks at the time of writing.
  • Finally, USTs conform to the energy-driven move, with US yields extending as energy picks up across the morning, to the benefit of the USD and detriment of the general risk tone. At the lower-end of 104-07+ to 104-15+ parameters, with the yield curve bear-steepening. Ahead, FOMC Minutes and a 10yr auction dominate the docket.
  • Germany sells EUR 1.912bln vs Exp. 4bln 2033 Bund: b/c 1.42x, average yield 3.36%, retention 52.2%.
  • UK sells GBP 1.0bln 0.25% 2031 Gilt via tender; b/c 4.39x (prev. 2.65x), average yield 4.842% (prev. 1.144%).
  • Australia sells AUD 1.0bln 4.25% October 2026 bonds: b/c 4.51x, avg. yield 5.3802%.

Commodities

  • WTI Nov and Brent Dec futures are mixed after paring overnight gains, with the complex caught between ongoing geopolitical risks and signs of improving supply. Overnight upside was driven by continued Saudi-Houthi attacks, reports of a vessel being attacked off Oman’s Musandam coast and missiles launched towards the Strait of Hormuz. However, gains were capped by yesterday’s Saudi Energy Minister supply comments, while Trump reiterated that millions of barrels have recently moved through Hormuz and expects oil prices to fall once the Iran war ends. US VP Vance also highlighted terms to end the Iran war, stating that Iran must cut its enrichment meaningfully. More recently, modest brief upside was seen after EU states said they expect no new oil-release obligations following the G7 agreement, alongside Zelensky saying Ukraine struck four targets supporting Russia’s war effort, including two oil facilities. WTI resides within a USD 89.33-90.61/bbl range, while Brent trades within a USD 100.72-102.06/bbl range.
  • Dutch TTF is firmer, extending from a EUR 75.52/MWh low to EUR 77.37/MWh at the time of writing, as European energy-security concerns remain elevated amid continued Middle East disruption. Attention is also on the IEA’s informal meeting at 12:00 BST, where proposals to release oil and diesel reserves will be discussed.
  • Precious metals are softer as the USD firms and yields rebound alongside energy prices. Spot gold has fallen from USD 4,170/oz to a USD 4,117/oz low, while spot silver has declined from USD 61.50/oz to USD 60.34/oz. The FOMC Minutes later today could provide impetus. As a reminder, The Fed unanimously hiked rates by 25bps in September, with the median participant projecting one more hike in 2026 and rates on hold through 2027. Since then, Williams and Jefferson have signalled no rush for further hikes, and Bowman sees none, while softer PCE data and a soft jobs report, with unemployment rising to 4.2%, may leave the minutes stale.
  • Base metals are flat/mixed amid the firmer USD, higher yields and a generally lacklustre risk tone, with Chinese buyers still absent ahead of their return from the week-long holiday tomorrow. Copper remains capped, with the return of Chinese participation overall providing little support to the complex. 3M LME copper resides in a USD 14,339.60-14,445.85/t range.
  • US Weekly Private Inventory Data (bbls): Crude -2.1mln (prev. +1.0mln), Gasoline -1.4mln (prev. +3.0mln), Distillate +0.5mln (prev. -0.3mln), Cushing +0.9mln.
  • Shell (SHEL LN) is evacuating non-essential workers from Stones, Mars, Olympus, Ursa, Vito and Appomattox assets in the US Gulf, while Chevron (CVX) does not expect the approaching storm to affect offshore operations.
  • EU diplomats said the IEA will hold an informal meeting at 12:00 BST to discuss proposals to release oil and diesel reserves.
  • EU states expect no new oil release obligations following the G7 agreement.
  • US Secretary of State Rubio said the current situation in the Strait of Hormuz and the Red Sea makes a strong partnership with Greece essential.

Trade/Tariffs

  • Talks between the EU and China will focus in on autos, as the EU looks for a commitment from China on stemming exports of hybrid vehicles, Politico reported citing sources. Bloomberg earlier reported that the EU is preparing a temporary import cap on Chinese hybrid cars.

Geopolitics: Middle East

  • US President Trump said they have to finish up regarding Iran and that the question is how, while he added that we will soon find out how they will finish up Iran and stated that Iran's drone-making capacity will soon be gone.
  • US VP Vance told Reuters that Iran must make a "meaningful" reduction in its nuclear enrichment capacity to satisfy US demands and end the war. Vance added that the US remained open to an agreement but would require concrete Iranian nuclear concessions. Furthermore, the VP questioned who makes decisions in Tehran, following on from earlier comments by US President Trump saying that his biggest problem is that no one knows who is running Iran.
  • US Secretary of State Rubio reiterated Iran cannot be allowed to have a nuclear programme.
  • Yemen's Houthi forces said they used drones to attack King Khalid International Airport in Riyadh, while they targeted Abha Airport and Khamis Mushait using missiles and drones.
  • Satellite imagery, cited by Sabereen, confirmed that there is still a fire at Saudi's Khurais oilfield.
  • An Asharq reporter posted that Syria may join the war in Yemen, with the idea said to be under discussion, citing multiple sources, although no final decision has been made; it follows Syria's President visiting Saudi Arabia.

Geopolitics: Ukraine

  • US President Trump said the Russia-Ukraine war is getting closer to ending, while he had a call scheduled with Russian President Putin regarding the plague and said he will probably be able to report on the pneumonic plague incident in Russia on Wednesday.
  • Ukrainian President Zelensky said Russia launched one of the largest attacks on Ukraine, directly targeting the country’s energy sector. Zelensky added that Ukrainian forces struck four targets supporting Russia’s war effort, including two oil facilities and a training ground in the Perm, Samara and Astrakhan regions.

Geopolitics: Other

  • North Korea warned South Korea not to cross the border by even a millimetre. It was separately reported that North Korea said the US should think twice before opposing China regarding Taiwan, according to KCNA.

Crypto

  • Bitcoin slumped early in the Asian session before stabilising around the USD 84k mark.

US Event Calendar

  • 7:00am: Oct 2 MBA Mortgage Applications -4.2%, prior -6.0%
  • 11:00am: Sept. NY Fed 1-Yr Inflation Expectations, est. 3.64%, prior 3.58%
  • 11:30am: US to sell $75bn 17-week bills
  • 1:00pm: US to sell $39bn 10-year notes (reopening)
  • 2:00pm: FOMC Meeting Minutes (Sept. 16 meeting)
  • 3:00pm: Aug. Consumer Credit, est. $15.000b, prior $18.062b

DB's Jim Reid concludes the overnight wrap

Although we said on Monday that the French government bond sell-off looked overdone — likely driven largely by the unwinding of carry trades amid an aggressive repricing of ECB rates — there is also a longer-term fundamental story to tell about France. Last night, Henry and I published a chartbook on the Deutsche Bank Research Institute (link here), with a series of long-term charts on France, in some cases using data going back a couple of hundred years. One standout is an old favourite of ours: France hasn't run a budget surplus since 1974. One of the longest consecutive runs in the world. Italy hasn't had one since 1925, but it has mostly run primary surpluses over the last three decades or so, so there is an important difference. See the pack here for plenty more charts putting the current situation in French debt into a longer-term perspective. Also a reminder that our Q3 survey results can be found here.

For now the stress in France continues to ease with OATs staging a strong recovery yesterday, which came as RN leader Marine Le Pen vowed to continue cutting the French deficit in the years ahead, which offered some reassurance on the country’s fiscal risks. So that helped a big rebound for French OATs and we’ve now seen the biggest 2-day decline in the Franco-German 10yr spread (-13.7bps) since the initial pandemic turmoil in March 2020, so these aren’t everyday moves. The optimism also translated into a global cross-asset rally, as US Treasury yields also pulled back from their multi-year highs while the S&P 500 (+0.58%) reached its first record high since mid-August. Although US equity futures are flat overnight, the mood in Asia is weaker amid a rise in oil and bond yields.

Starting with Le Pen’s speech, markets were reassured by her pledge to cut the French deficit. She said that they’d get the deficit below 3% over the first 18 months if elected next spring, so in 2028. In addition, she also pledged to eliminate the primary deficit before end-2028, and called for spending as a share of GDP to fall beneath 50% by the end of her presidential term. Given Le Pen is currently leading in opinion polls, her fiscal plans are ones that markets are paying attention to. There are plenty of questions over both the feasibility of her radical headline fiscal target, which would far outpace any fiscal tightening France has delivered in recent history, as well as the credibility of some of the details in Le Pen’s proposals. Still, her public focus on delivering fiscal consolidation helped to ease the recent spike in investor concerns.

To be fair, much of the rally in OATs had also already played out before Le Pen’s speech, with a likely unwinding of some of the distortions that had emerged in the recent sell-off. Notably, at the front-end of the curve the 2yr Franco-German spread tightened by -15.4bps to 45bps. In absolute terms, there was also a sharp decline in French yields across the curve, with the 10yr yield (-10.9bps) falling to 4.74%, in contrast to the modest decline for 10yr bund yields (-1.4bps).

That recovery in French bonds also supported a relief rally across much of Europe, as it eased fears about contagion spreading to other countries. So the sovereign bonds of other countries with high debt levels also outperformed, with Italy’s 10yr BTP yields (-9.8bps) seeing a decent pullback to 4.53%. Moreover, several assets that struggled last week also stabilised, with the Euro (+0.32%) picking up from its recent low on Monday, whilst the STOXX Banks Index (+1.34%) was up for a second day running. That extended to credit as well, with European HY spreads (-15bps) seeing their biggest daily tightening since April.

Outside of Europe, the other big headline yesterday was that the S&P 500 (+0.58%) closed at a new record high for the first time since August 13, ahead of the Q3 earnings season. The move was a broad-based one, with the equal-weighted S&P 500 (+0.58%) rising by the same amount. And there were also new highs for the Mag 7 (+0.45%) and the NASDAQ (+0.45%). The moves were also part of a global equity rally, with Europe’s STOXX 600 (+0.48%) and France’s CAC 40 (+0.40%) also rising.

US Treasuries also rallied. The 10yr yield (-2.6bps) fell back from its post-2002 high on Monday to 5.28%, and the 2yr yield (-1.4bps) also fell to 4.80%. The move lower was led by real yields, with the 10yr real yield (-2.6bps) falling back from its post-2008 high to 2.91%.

All that came as yesterday saw a sizeable round trip in oil prices. Brent crude fell towards $97/bbl early in the US session amid optimism on oil flows coming out of the Middle East. However, this gave way to caution later on news of increased Iranian strikes against tankers passing through the Strait of Hormuz and as Iran’s IRNA reported that a blast was heard off Qeshm island near Hormuz. This brought Brent crude back up to $100.58/bbl by the close (+0.26% on the day), and it is another +1.01% higher this morning. Meanwhile, European natural gas prices rose yesterday, with front-month TTF rising +2.96% to €75.70/MWh, its highest level since mid-September.

With bonds selling off and oil rallying, the mood in Asia is softer this morning. 10yr US yields are +2.8bps, reversing yesterday's rally so far. In equities, the KOSPI (-1.18%) is leading declines, weighed down by losses in index heavyweight SK Hynix. The Nikkei (-0.81%) and the Hang Seng (-0.53%) are also trading lower, while the S&P/ASX 200 (-0.05%) is fairly flat. Mainland Chinese markets remain closed for the National Day holiday and will reopen tomorrow. European Stoxx futures are -0.64% lower, underperforming their flat US equivalents.

Elsewhere, the Japanese yen (-0.20%) is weakening for a third straight session, trading around 158.40 against the dollar, after newly appointed BOJ board member Ayano Sato signalled support for a gradual, multi-stage approach to further interest-rate hikes. In terms of data, real wages rose by 1.5% last month matching estimates with nominal up +3.8% and the seventh month above 3%, the longest run since 1992.

To the day ahead now, data releases include the NY Fed’s Survey of Consumer Expectations for September, US August consumer credit, Germany’s August industrial production, France’s August current account balance, and Sweden September CPI. We’ll also get the FOMC minutes and hear from the Fed's Logan, along with the ECB’s Cipollone and Vujcic.

Tyler Durden Wed, 10/07/2026 - 08:23
World Bank Warns Asia Is Running Out Of Money To Fight Energy Shock

World Bank Warns Asia Is Running Out Of Money To Fight Energy Shock

Authored by Irina Slav via OilPrice.com,

Asian countries have responded more aggressively than others to the energy supply crunch caused by the U.S. and Israeli war on Iran and now they are running out of resources to continue their response, the World Bank warned in a new report.

The report actually focuses on the potential of artificial intelligence to help Asian economies grow but names energy import vulnerability as one major headwind to that growth.

"Subsidies have been by far the most common policy response [to the crisis] among emerging and developing economies," the World Bank said, adding that "Countries with substantial subsidies in place generally have had smaller increases in retail gasoline prices than non-subsidizers, but this relationship weakened considerably for headline inflation."

Energy remains a spot of weakness for Asian countries due to their overwhelming dependence on imports but, according to the World Bank, AI can change that by motivating a shift towards greater domestic electricity generation, which would in turn lead to lower demand for imported energy commodities.

Meanwhile, Asian countries' response to the energy crunch has led to lower prices at the cost of lower foreign exchange reserves, the lender also said. The longer the crisis continues, the greater the effect on their fiscal health would be, the World Bank warned, noting as examples Indonesia, Thailand, and Vietnam, which saw their dollar reserves decline by between 15% and 40% since the start of the war because of their crisis response actions.

These response actions, however, have had no effect on inflation anywhere in the world, and "headline inflation has sharply increased in many countries, even as core inflation has remained more subdued."

For Asia, however, there is hope for a reversal, driven by information technology generally and AI specifically, according to the World Bank.

"The region's dependence on AI-related industrial activity has been a source of strength, but it could become a weakness if global AI activity slows or reverses," the institution said in its report.

Tyler Durden Wed, 10/07/2026 - 08:05

Standard Chartered Says Hormuz Oil Flows Are Far From Normal

Standard Chartered Says Hormuz Oil Flows Are Far From Normal

Authored by Alex Kimani via OilPrice.com,

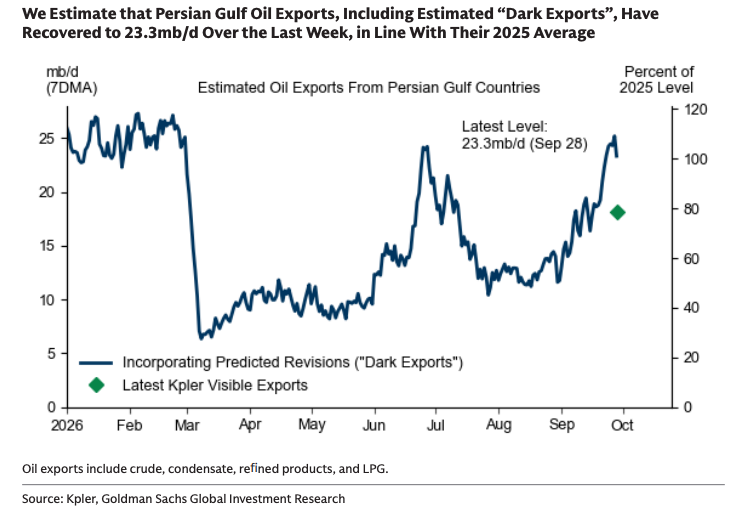
  • Gulf oil exports rebounded to roughly 16.5 million bpd in September, near pre-war levels, despite only 60% of those barrels crossing Hormuz versus 83% before the war.

  • Exporters have adapted through pipelines, bypass ports and extensive ship-to-ship transfers, but the system is more expensive, inefficient and increasingly stretched, with elevated freight and security costs.

  • Iran’s ability to choke off regional oil exports has weakened, while its own seaborne crude exports have fallen from around 1.7 million bpd to near zero.

Oil flows through the Middle East have staged an impressive rebound, with export volumes recovering to near pre-war levels even as traffic through the Strait of Hormuz remains well below normal. Standard Chartered estimates crude and condensate exports from the Gulf, excluding Iran and including bypass routes such as Fujairah and the Red Sea, reached roughly 16.5 million barrels per day (bpd) in September, broadly back to pre-war volumes. But only 60% of those barrels crossed the Strait of Hormuz, compared with 83% before the war. Standard Chartered says the numbers show resilience rather than normalization: exporters have found ways to move the oil, but they are doing it less efficiently and at considerably higher cost.

The system has been forced to use more complex workarounds, particularly a vessel-intensive chain of ship-to-ship (STS) transfers. Shuttle tankers are increasingly moving crude through Hormuz before transferring it to larger vessels in the Gulf of Oman, while exporters are also making greater use of pipelines and ports that bypass the strait. The southern route along the Omani coast has become an important route for shuttle vessels moving through Hormuz. Standard Chartered says STS capacity appears saturated, vessel utilization remains inefficient, voyage times have lengthened and both freight and security costs remain elevated.

Saudi Arabia perhaps best illustrates both the success and limits of this adaptation. Following the early-September damage to the East-West pipeline, exports shifted sharply to the east coast. Standard Chartered estimates total Saudi exports rebounded to roughly 6.9 million bpd in September from 2.45 million bpd in August, with 19 VLCCs transiting Hormuz in one week alone. The restart of the East-West pipeline and Yanbu loadings has restored another route to market and reduced the immediate risk of shutting in production, although pipeline throughput remains below nameplate capacity and exposed to further attacks. The workarounds are also expensive, with reports of discounts of up to $9 per barrel on cargoes loaded offshore Oman to compensate for the added logistical costs.

The recovery in physical flows has reduced the probability of the most extreme shortage scenarios and should gradually remove some of the scarcity premium in oil prices. But those barrels are moving at higher cost, with longer voyage times, heavier use of tankers and less spare capacity in the logistics system. Standard Chartered says the improvement is bearish compared with a market pricing a prolonged physical supply loss, but does not justify a return to pre-war risk premiums. Exporters have shown they can move far more crude than many expected, but the system has less room to absorb another major disruption.

The tactical success of Gulf exporters has also altered regional dynamics. Seaborne crude exports from Iran fell to near zero in September, down from roughly 1.7 million bpd before the war, after the U.S. naval blockade sharply curtailed Tehran's ability to move crude through Hormuz. Consequently, Iran's ability to weaponize its chokehold on the Strait of Hormuz is breaking down, though this increases the risk of unpredictable military escalation.

Iran remains defiant and reiterated Sunday that the Strait of Hormuz will remain closed until the United States fulfills seven conditions contained in the June interim agreement. Foreign Minister Abbas Araghchi said separately that Tehran's latest proposal could lead to the strait reopening within seven days if Washington accepts Iran's terms.

Tehran has denied reports that it offered international nuclear inspections in exchange for sanctions relief. Araghchi has said Iran hopes Washington will pursue diplomacy, but warned that the country is better prepared than before to respond if the U.S. opts for further military action.

Tyler Durden Wed, 10/07/2026 - 07:20

$240 Million Triton Spy Drone Stops Feet From Disaster After Apparent Florida Runway Overrun

$240 Million Triton Spy Drone Stops Feet From Disaster After Apparent Florida Runway Overrun

A roughly $240 million MQ-4C Triton surveillance drone built by Northrop Grumman apparently overran a runway at Naval Station Mayport near Jacksonville, Florida, last week, stopping just dozens of feet from plunging into the water. 

Footage circulating on X appears to show the drone perched on shoreline riprap beyond the departure end of the base's 8,001-foot Runway 05, narrowly avoiding a plunge into the St. Johns River.

The US Navy operates the Triton for maritime intelligence, surveillance, and reconnaissance, using the high-altitude, long-endurance drone to monitor vast stretches of ocean.

Northrop Grumman said in June 2025 that it had produced 20 Tritons for the US Navy. A single drone represents 5% of that production total. Any loss of the aircraft would be a significant loss for the fleet. That figure does not represent the current operational fleet, as those figures are unknown. 

The Navy has not publicly explained what caused the drone to end up on the riprap. The footage suggests a possible runway overrun. 


Tyler Durden Wed, 10/07/2026 - 06:55

UK Makes 7th Arrest Over Security Incident Near RAF Fairford Airbase

UK Makes 7th Arrest Over Security Incident Near RAF Fairford Airbase

Authored by Ryan Morgan via The Epoch Times,

Authorities in the United Kingdom have announced the arrest of another suspect in connection with a recent security incident near the RAF Fairford airbase used by U.S. forces.

On Oct. 6, the UK's Office for Counter Terrorism Policing announced the arrest of a 22-year-old male British national in the Westminster borough of London. Authorities detained the man on suspicion of preparing terrorist acts.

The 22-year-old is the seventh to be arrested after authorities were alerted to suspicious activity near the airbase in Gloucestershire on Sept. 27.

U.S. President Donald Trump and British Prime Minister Andy Burnham have both publicly indicated the Sept. 27 incident may be linked to an Iranian plot.

Authorities initially arrested five British nationals on Sept. 27, on suspicion of committing offenses under the UK's Explosives Act. These five men were subsequently released on police bail.

On Oct. 1, authorities announced the arrest of a sixth individual, whom they identified as a 25-year-old British-Iranian national. Authorities have since released this sixth individual on police bail.

"This remains a live investigation, and our specialist teams continue to pursue multiple lines of inquiry into the circumstances surrounding events near RAF Fairford," senior national coordinator for Counter Terrorism Policing Vicki Evans said on Tuesday.

Evans thanked the public for their patience as police continue their work.

"We're acutely aware of the public interest in this investigation, and we are working around the clock, and at pace, to identify the motivation behind events in Gloucestershire," Evans said. "We remain committed to investigating all possible angles."

Over the weekend, the U.S. Air Force withdrew its B-1B Lancer long-range bombers from their forward positions at RAF Fairford.

Addressing the decision to pull U.S. bombers away from the airbase, Trump expressed concerns about a lingering threat.

"We had an idea that there might be a threat," the president told reporters on Oct. 5.

Separately, Vice President JD Vance said the decision to remove the bombers from RAF Fairford was taken out of an abundance of caution.

When asked if Iran-linked actors may have brought armed drones into the UK to carry out attacks, Trump said, "I can't tell you that. But if they did, they'll suffer greatly."

During the initial set of arrests on Sept. 27, authorities searched multiple vehicles deemed suspicious. They said they found no explosive devices, but did recover some quantity of gasoline.

While British and American officials have suggested Iran may be behind the Sept. 27 security scare at RAF Fairford, Iranian officials have denied Tehran's involvement.

"You're barking up the wrong tree," Iranian Foreign Minister Abbas Araghchi said on Sept. 30.

Though Tehran has denied any connection to the recent security alert near RAF Fairford, Iran's Islamic Revolutionary Guard Corps previously said it would treat any bases used to launch strikes on Iranian territory as legitimate targets for retaliation.

The British government has authorized U.S. forces to use some of its bases, including RAF Fairford, to launch strikes on Iranian missile sites that have targeted international shipping.

Last year, Ukrainian forces snuck more than 100 explosive-laden drones deep inside Russia's border to carry out extensive attacks on bases hosting Russian strategic bomber forces.

Tyler Durden Wed, 10/07/2026 - 06:30

Lithuanian Parliament Advances Measure To Reverse Nuclear Weapons Ban

Lithuanian Parliament Advances Measure To Reverse Nuclear Weapons Ban

Back in July, Lithuanian President Gitanas Nauseda declared that his country must be part of the NATO alliance's nuclear sharing program: "We would like to be the integral part of this nuclear deterrence," he had said at the time.

He was addressing a big hurdle written into Lithuanian law, namely the existent constitutional ban on nuclear weapons from Lithuanian territory.

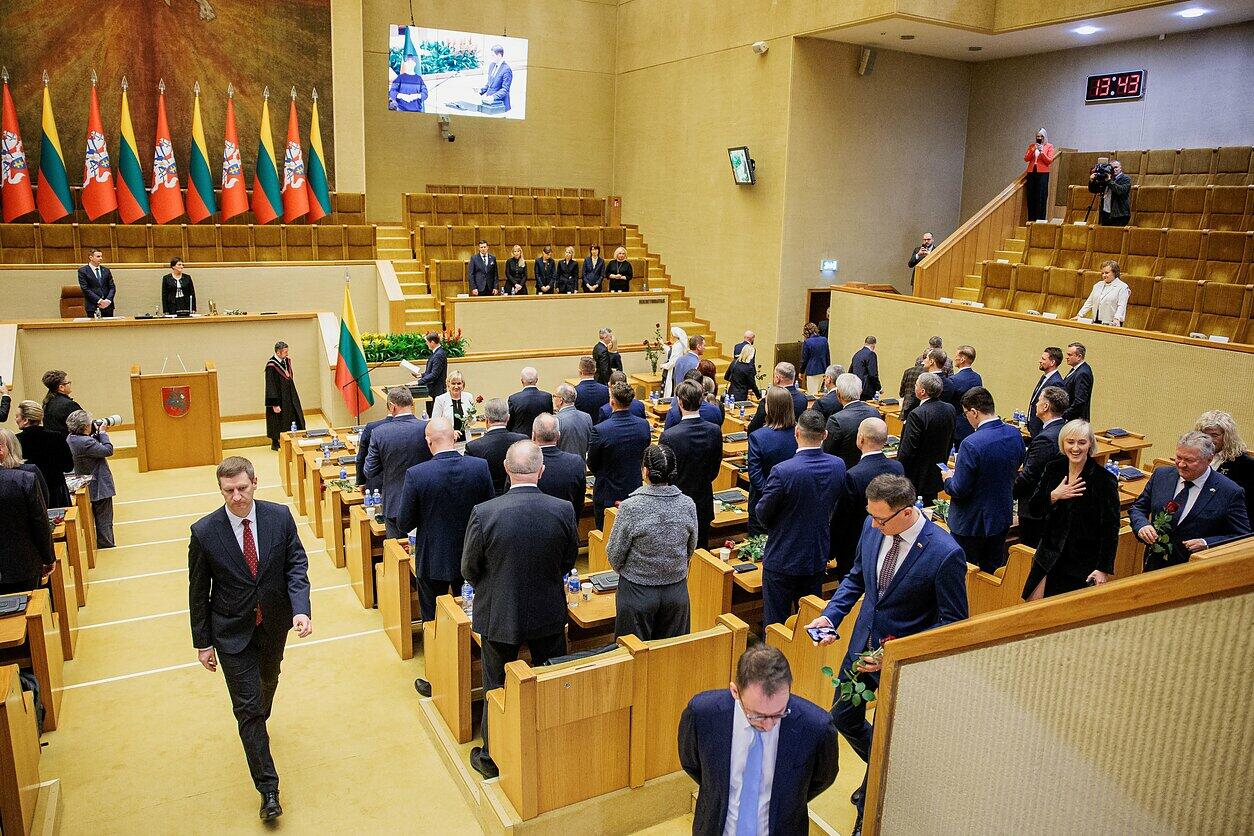
But on Tuesday the effort to overturn the ban passed its first big test, with the Lithuanian parliament, the Seimas, having voted 106-18 to advance a constitutional amendment that would reverse the ban.

Source: LRT nuotr.

But there will be more procedural rounds yet to go in the coming months before the change can become a reality:

The change still requires a second vote after a constitutionally mandated three-month waiting period. At least 94 of the Seimas’ 141 members must back it on both occasions. The final vote is expected on January 12.

“This constitutional amendment would enable Lithuania’s armed forces to participate fully in the planning and exercises of all of NATO’s deterrence measures,” said Viktorija Čmilytė-Nielsen, leader of the Liberal Movement parliamentary group.

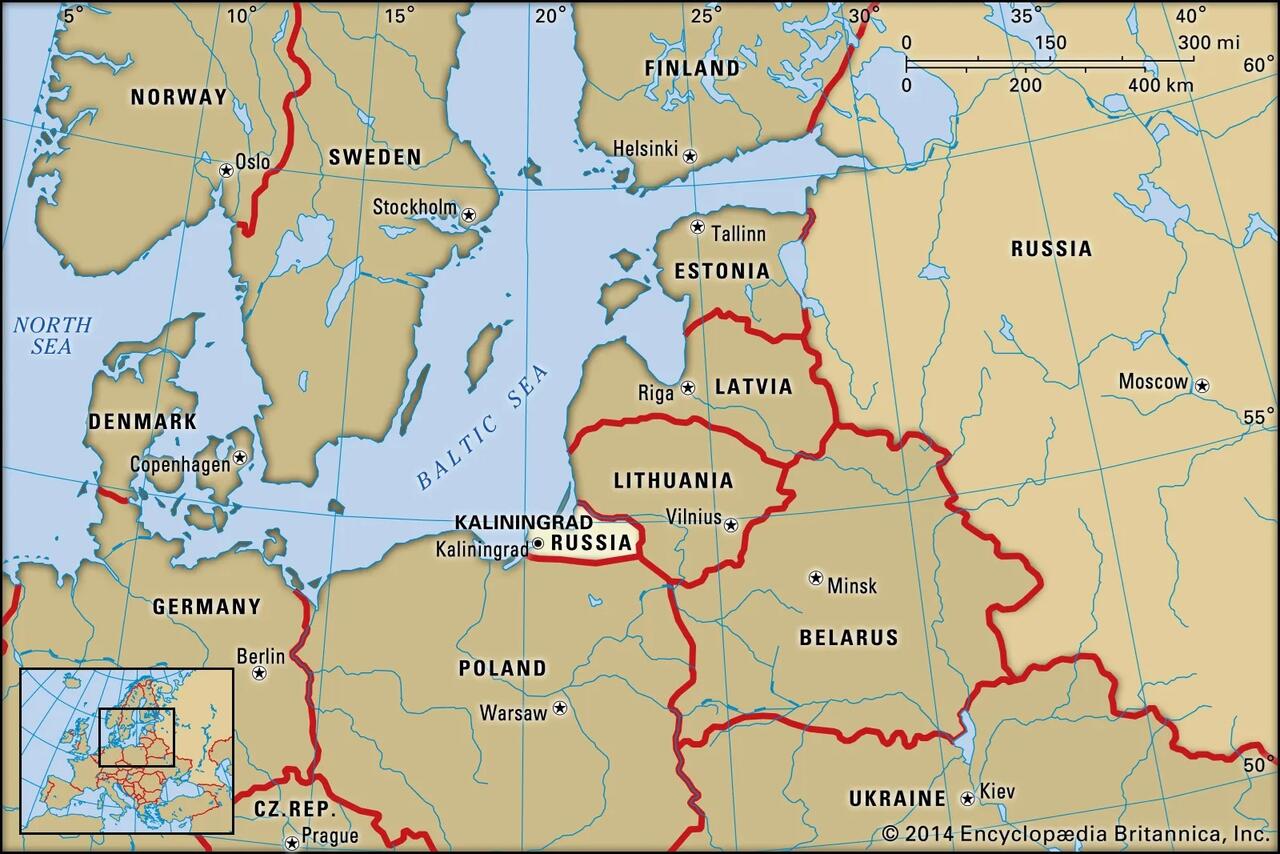
The effort is obviously hugely provocative to Russia, given the end result could be NATO nukes stationed right on Russia's Baltic doorstep.

But Lithuania's political establishment is looking fully onboard: "Our neighboring countries, such as Latvia, Estonia and Poland, have no such restrictions either," Remigijus Motuzas, chairman of the Seimas Foreign Affairs Committee, has told parliament. "We cannot be less protected than other NATO countries. We must send a signal that Lithuania is a full part of NATO’s nuclear deterrence."

As for the current constitutional prohibition in question: 

Article 137 of Lithuania’s Constitution currently states that weapons of mass destruction and foreign military bases may not be located on Lithuanian territory.

Finland's parliament has already voted on its own reversal this summer, after which Russia moved to secure more border areas with NATO countries.

Since the Ukraine war began, and in context of ratcheting tensions with NATO over its military support to Kiev, Moscow has steadily militarized its border regions with Baltic and Scandinavian states.

The most significant source of NATO's nuclear-sharing program remains the United States. But lately France has expressed a desire to station some of its atomic arsenal in partner countries, and this could include in Finland, Sweden, Denmark and others.

Tyler Durden Wed, 10/07/2026 - 05:45

Ballot Box Jihad: The Non-Violent Conquest Of The West

Ballot Box Jihad: The Non-Violent Conquest Of The West

Authored by Robert Williams via Gatestone Institute,

"This could be the first election in Sweden where the Muslim immigration that we have had is decisive in a parliamentary election," predicted the leader of the Sweden Democrats, Jimmie Åkesson, days before Sweden's election on September 13.

He was right. Sweden's center-right Sweden Democrats government indeed lost the elections by a razor-thin margin - reportedly just 50,000 votes - corresponding to just three seats in parliament.

The next government will almost certainly be a socialist one.

"Voters who, or whose parents, grew up outside Europe overwhelmingly favoured the Left," Brussels Signal wrote in its analysis of an exit poll by SVT, Sweden's national public broadcaster:

"The Social Democrats received 38 per cent of their votes, the Left Party 21 per cent, the Greens 7 per cent and the Centre Party 4 per cent. Together, these parties accounted for 70 per cent, against 27 per cent for the four parties of the outgoing right-wing bloc."

The tiny socialist majority was won through heavy voter mobilization within immigrant communities, which tipped the balance. Turnout rose around 3 points to 67.5% in the almost exclusively urban districts, where mainly Muslim immigrants live.

"This election has in part been about voter mobilisation, which is unusual in Sweden," noted to Gustav Karreskog Rehbinder, founder of AI analysis firm Vera Policy, which broke down the election results for Reuters.

According to Fredrik Karrholm, a member of the Swedish parliament and the author of Gangster Violence:

"A poll by the respected Novus institute before the election found that of Muslim respondents, around 80 per cent intended to vote for either the Social Democrats or the Left party.

"In some districts with large immigrant populations, the results are striking. For example, in Rosengård Centrum in Malmö, the Social Democrats and Left Party together received, according to the preliminary count, 95.2 per cent of the vote...

"This pattern predates the present government...

"During the last parliamentary term, around 200,000 people were given citizenship under rules that imposed very few demands on applicants - not even a requirement to speak or write Swedish. The majority of those granted citizenship were from outside Europe....

"Immigration to Sweden has not only brought crime, social problems and unemployment - now the government that was successfully starting to solve these problems has been voted out because of immigration itself."

For a brief moment, it had seemed as if Sweden was finally beginning to turn things around. In 2022, Sweden voted in a center-right government that ruled with the parliamentary backing of the Sweden Democrats - a first in Swedish politics. This government sought to implement the most restrictive overhauls of Swedish asylum and immigration policies in Swedish history with crackdowns on asylum and migrant flows, while making it harder for immigrants to acquire permanent residence and Swedish citizenship.

After decades of lawlessness, the center-right government, now voted out, had also sought to crack down on crime by finally openly linking migration to gang violence, parallel societies, and integration failures.

The results were dramatic: In December 2025, Reuters reported:

"The number of shootings in Sweden has more than halved since hitting a peak in 2022, reflecting new policing approaches introduced by the right-wing government, which is readying for parliamentary elections next year. Shooting incidents fell to 147 so far this year, a 63% decrease compared to 2022 when there were 390 shootings and a 49% decrease compared to 2024, according to a Reuters analysis of official figures."

The government also began to scrutinize the detrimental effects of Islam in Sweden, including the launch of a government investigation into the Islamist infiltration of Swedish society. This past spring, the government announced that it would be dropping the entire concept of "Islamophobia."

Sweden, in short, had been on the road to becoming Swedish again - but if the election results lead to a new socialist government, that will no longer happen: The Left Party alone is deeply infiltrated by Islamists and terrorist supporters, with several of its politicians caught celebrating the October 7, 2023 Hamas invasion of Israel, with some handing out candy on the streets to mark their joy at the massacres of Israelis. In addition, several candidates were found to have shared content praising or expressing support for designated terrorist organizations, including Hamas, Hezbollah, the PFLP and Al-Qaeda, while multiple candidates shared classic antisemitic tropes, Holocaust denial and homophobia.
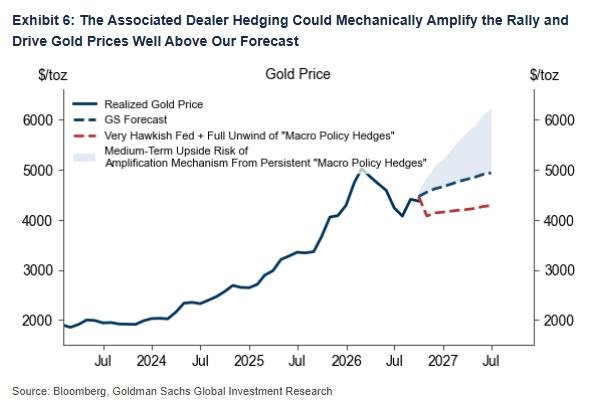
These revelations, all dug up by the Swedish press, forced the Left Party to remove at least 33 of its most extremist candidates, an astounding number.
Many other radicals within the party kept their parliamentary seats, including MPs Ilona Szatmári Waldau and Samuel Gonzalez Westling, who sent open letters of support to Palestinian terrorists held in Israeli prisons for serious offenses, such as ordering suicide bombings and torturing and murdering an Israeli soldier. In October 2025, the party's top leadership, including party leader Nooshi Dadgostar, hosted two visiting Palestinians from the Fatah Revolutionary Council inside the Swedish Parliament. The two guests were known for having publicly praised terrorist acts and spreading Jew-hatred.

If you think any of this harmed the party, you would be wrong: The scandals actually served to boost it: they gained the party six new seats in the election.

There is a name for what just happened in Sweden: Ballot box jihad. It is an Islamist tactic, favored by the Muslim Brotherhood.

"In the Middle East, democracy and elections are various means to one end: the establishment of a decidedly undemocratic form of law - Islamic, or Sharia Law," Raymond Ibrahim wrote about the Egyptian elections in 2012, which, for a brief moment, brought the Muslim Brotherhood to power.

"An Egyptian cleric, Dr. Talat Zahran, proclaimed that it is 'obligatory to cheat at elections, a beautiful thing' -- meaning that voting is a tool, an instrument, the only value of which is to empower Sharia. Another cleric, Hazim Shuman... issued a fatwa that likened voting for Islamist candidates to a 'jihad,' or a holy war, adding that paradise awaits whoever is 'martyred' during the electoral campaign."

The same tactic applies to the Islamist project of nonviolent conquest of the West. The late spiritual leader of the Muslim Brotherhood, Yusuf al-Qaradawi, speaking in Qatar in 2007, said that "Islam will conquer Europe without resorting to the sword or fighting. The conquest will be through da'wah [proselytizing] and ideology."

Ballot box jihad is part of achieving this conquest. Sameh Egyptson, an Egyptian-Swedish academic, writer and expert on political Islam, has been warning about Islamist infiltration of the political system for years. He has recently cautioned, among other things, against clan voting as an erosion of democracy. Clan voting is when extended families and even entire ethnic communities vote collectively as a bloc for the same candidate or party. Although clan voting as such is not illegal in Sweden, two newly elected Muslim candidates from the Left Party are already suspected of electoral fraud, including bribing or unduly influencing voters to vote for them and pre-marking their own names on ballots.

This outcome is possibly what many socialists have been planning all along: To stay in power forever by importing new voters from the Third World.

Sweden is a warning, not only to the rest of Europe but to the Western world at large.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden Wed, 10/07/2026 - 05:00

Cowardly Europe Fears Dissent

Cowardly Europe Fears Dissent

Authored by J.B. Shurk via American Thinker,

Orwellian brutes now govern Europe...

Former-banker-turned-tiny-French-President Emmanuel Macron blasted what he called "American free speech" while speaking to reporters last week. Defending the European Union's robust censorship policies, le petit fromage insisted that Europe's speech-policing Digital Services Act should censor information that governments consider false "much more extensively, much faster, and much more forcefully."

Macron then did his Orwellian best to condemn free speech as oppression and praise censorship as liberation: "So-called American 'free speech' - at least as it exists today and has been promoted by some people - is the opposite of free speech." The terribly disliked French leader continued, "My freedom cannot mean that I am free to...insult you or vandalize the public square that belongs to everyone. Yet that is some people's idea of 'free speech.'"

Then the little mouse of a man roared, "Until we hold those who disseminate content on social media accountable, we will not be able to regulate it." Furthermore, if "someone writes something" that is "false," then that person should be "held accountable." Tough talk from an insecure man afraid of words.

What is going on in Europe? Why is the whole continent so scared of public debate and dissent? If the political Establishment is unable to defend its ideas and policies without censoring the opposition, then its ideas and policies are absolute rubbish! The people who have willed their way to power across Europe apparently believe that they cannot win an argument unless they are the only ones permitted to speak!

That's a bit like a puny pugilist demanding that referees tie another boxer's hands behind his back before declaring himself world heavyweight champion!

Personally, I think mini-mouse Macron is just tired of people pointing out that he married his grandmother (or his grandfather, as the case might be). We used to teach our children, "Sticks and stones may break my bones, but words will never hurt me." Now Western leaders are so terrified of words that they'd rather imprison everyone with an opinion than learn to take a joke or hear a contrary point of view.

Here's the truth that Macron and his fellow Euro-weenie censors refuse to understand: Free speech is free only when a speaker can say something offensive or controversial without fear of the State's wrath.

Although Macron wants to criminalize speech that he considers untrue, he spreads endless falsehoods of his own! While beseeching British Prime Minister Andy Burnham to betray the will of voters who chose to leave the European Union ten years ago, the Napoleon-complex-afflicted French president whined, "Brexit is the biggest lie of the last thirty years!" That boast is absurdly false (or what European censors call criminal "misinformation"). The British people did vote to separate themselves from Queen Ursula von der Leyen's European empire.

Even though Brexit fearmongers predicted imminent economic collapse should the British people choose to rule themselves - and despite the best efforts of Brexit saboteurs at home and abroad - the United Kingdom is currently outperforming France and other major European economies, having led the G7 in growth during the first half of 2026. One reason Brexiters voted to leave the E.U. in 2016 was because British citizens did not want their military to be swallowed into a European Army beyond their control - a prospect, ironically enough, which pro-E.U. stalwarts once called "disinformation" but which has proved increasingly prescient.

Queen von der Leyen and her Brussels Eurocrats are working feverishly today to use the Russia-Ukraine War as an excuse to create increasingly centralized European defense structures.

It's also worth remembering that European expansionists originally promoted the Union as an intergovernmental body meant to boost European economic markets and promised that the supranational institution would never directly usurp national sovereignties. That was a clear case of "misinformation" and certainly one of the biggest lies of the last half-century!

Speaking of lies that European leaders have promoted as "truths," the Russia Collusion Hoax against President Trump (which British and Ukrainian intelligence agencies helped to propagate), the "global warming" apocalypse (which was scheduled to kill us all fourteen years ago), and the "Reign of COVID Error" (during which "health experts" lied about the virus arising from nature instead of a Chinese laboratory and then lied about fake "vaccines" being "safe and effective") are three of the biggest mass frauds and information warfare campaigns ever perpetrated by governments against the public.

Macron has never called for these lies to be censored from social media platforms. He just doesn't like it when random Americans point out that the European Union is an undemocratic and totalitarian system of governance that should be burned to the ground. And he really doesn't like it when commoners correctly point out that his old high school teacher - and abusive wife - sometimes slaps him around.

Unfortunately, Macron's inability to understand the importance of free speech is a European-wide learning disability.

In the U.K., a member of the public has filed a Prevent referral against eighty-six-year-old comedy legend John Cleese because he continues to make fun of Islam's love for rape and murder. The complaint argues that Cleese should be considered a "moderate to high risk" for "radicalisation, communal tension, and hate incidents" for writing, among other things, "I personally prefer a culture that does not approve of FGM, Child Marriage and Killing Infidels."

The complaint accuses Cleese of "anti-Muslim hate" and seeks further scrutiny of the cultural icon. In response to news of the referral, the Monty Python alum wrote, "The Islamic male ego becomes so bloated by its lack of restraint that it believes any criticism is blasphemy," and, "I look forward to being arrested." Later, he declared his targeting "One of the proudest moments of my life."

Meanwhile, a retired police officer was recently fined more than £1,000 under the U.K.'s Communications Act for reposting a bacon joke ridiculing Islam. As one free speech advocate rightly observed, "No-one making a similar joke about Jesus would face prosecution."

At the same time that it targets retired cops for having a sense of humor, the British government continues to hand out "skilled worker sponsorship licenses" to Islamic bookstores that sell books on jihad!

An Islamic preacher in London encourages Muslim men to beat their wives if they refuse to obey. The same Islamic cleric describes "acceptable" execution methods for gay men, including throwing them off tall buildings and pummeling their bodies with rocks. These sermons are available on YouTube.

Nevertheless, the mosque still enjoys charitable status in the U.K. Islamic jihadists preach violence and murder, and law enforcement agencies ignore their threats, just as they ignored - for decades - Islamic men raping tens of thousands of young girls across Britain.

However, when a comedian and a retired police officer mock Islam's penchant for violence, the British government scrutinizes their speech as "threats." That should be no surprise when U.K. police forces instruct officers that Nigel Farage's immigration beliefs are "Islamophobic hate crimes" and encourage non-Muslim staff to fast during Ramadan in "solidarity" with their Islamic conquerors.

Two-tiered "free speech" is official government policy. Furthermore, a Home Office-linked unit has been recording social media criticism of the government's Prevent program, including 77 observations concerning people and organizations criticizing Prevent on X and Reddit. Documents show that government-linked officials are monitoring and recording the speech of people who publicly challenge this controversial counter-extremism policy.

Orwellian brutes now govern Europe. Need further proof? The Green Party in the U.K. wants to replace "mother" and "father" with more "inclusive" terms. Meanwhile, the Germans just awarded the Westphalian Peace Prize to NATO's military alliance.

Parents are strangers. War is peace. Free speech is violence. Censorship promotes liberty.

In truth, freedom in Europe is dead.

Tyler Durden Wed, 10/07/2026 - 02:00

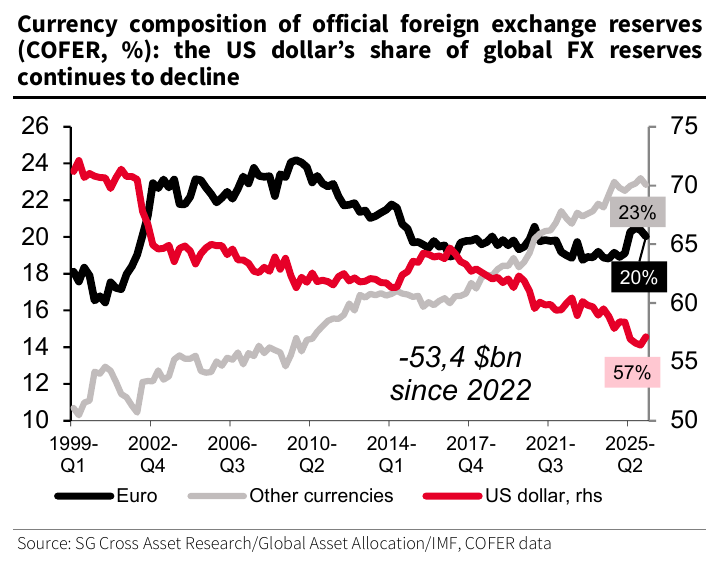
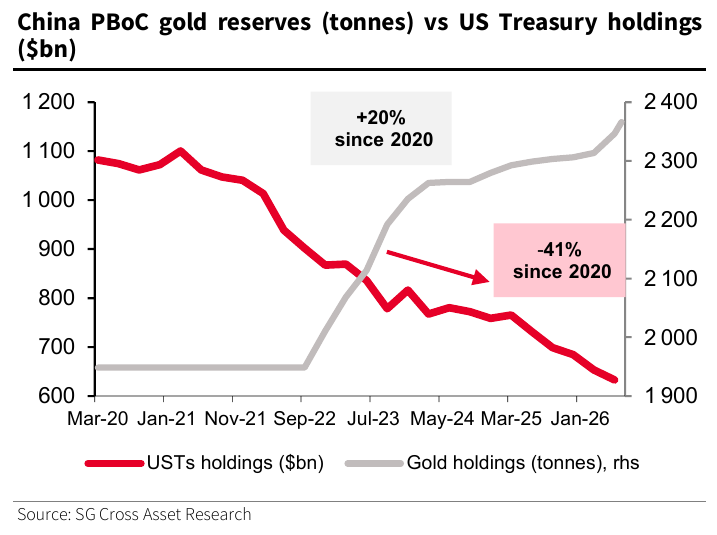
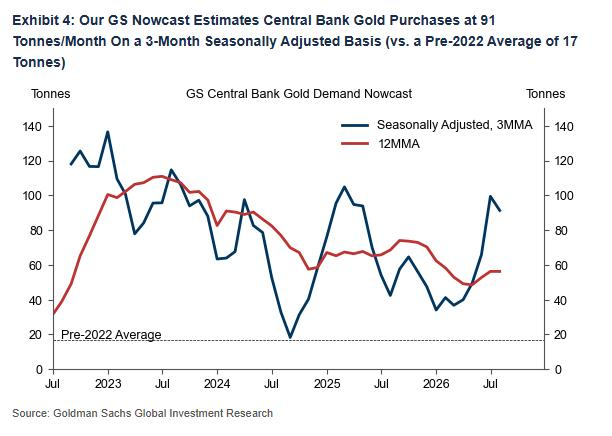
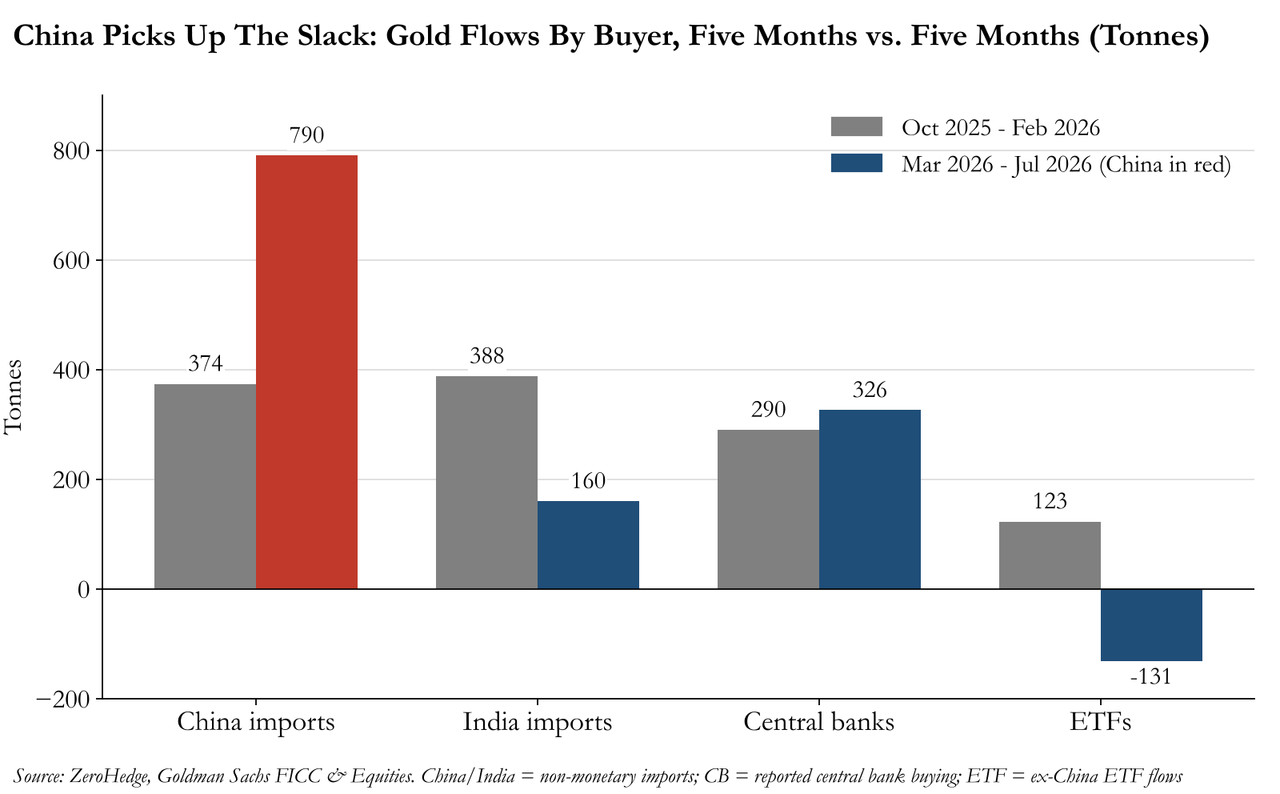
The Petrodollar Could Break Soon - And Upend The Global Financial System

The Petrodollar Could Break Soon - And Upend The Global Financial System

Authored by Nick Giambruno via InternationalMan.com,

The Iran war could claim a casualty far more consequential than a missile battery, an air base, or an oil tanker: the petrodollar system.

For more than 50 years, US protection of the Gulf monarchies has helped support global demand for dollars and US government debt. That bargain may now be coming under strain.

The concept is straightforward.

The US provides military protection to countries such as Saudi Arabia, Kuwait, the United Arab Emirates, Bahrain, and Qatar.

In return, these countries price much of their oil in US dollars and recycle large amounts of their oil revenue into US financial assets, including Treasuries.

Call it an alliance.

Call it a strategic partnership.

I prefer to call it a protection racket.

Whatever name you choose, the arrangement has provided enormous support for the dollar since Nixon severed its last link to gold in 1971.

Oil sits at the center of the global economy. Every industrial economy needs it. If countries need dollars to participate in the global oil trade, they have a powerful reason to hold dollars.

That creates demand for the currency that has nothing to do with buying American goods or services.

It also creates demand for US financial assets.

Oil exporters earn dollars. They need somewhere to put them. For decades, a large portion flowed back into US banks and Treasury securities.

That helped deepen the Treasury market, support the dollar, suppress US borrowing costs, and finance deficits that no other country could sustain.

But every protection racket depends on one thing:

The protector must provide protection.

The Iran war threatens that premise.

If the Gulf monarchies conclude that the US cannot protect their oil infrastructure, shipping lanes, cities, and regimes from Iran, why should they continue upholding their side of the bargain?

That question could reshape the international monetary system.

And one man warned almost exactly 20 years ago about the signal that would tell us this shift had begun.

Ron Paul Saw This Coming 20 Years Ago

On February 15, 2006, Congressman Ron Paul delivered a little-known but prophetic speech on the floor of the House of Representatives called "The End of Dollar Hegemony."

He identified the signal investors should watch for:

"The chaos that one day will ensue from our 35-year experiment with worldwide fiat money will require a return to money of real value. We will know that day is approaching when oil-producing countries demand gold, or its equivalent, for their oil rather than dollars or euros. The sooner the better."

I discussed this subject with Ron Paul at an investment conference years ago. He stood by that assessment.

His point was simple.

Watch the oil producers.

The day they start moving away from dollars and toward gold - or a monetary system that gives them access to gold - the foundation beneath the dollar-based financial system starts to crack.

We may now be approaching that point.

Why the Gulf States Could Turn East

The Gulf Cooperation Council includes Saudi Arabia, Kuwait, Qatar, Bahrain, Oman, and the United Arab Emirates. Together, these countries rank among the most important oil exporters on Earth.

China sits on the other side of that trade.

It is the world's largest oil importer and the GCC's largest trading partner.

That creates a natural relationship: China needs enormous quantities of energy, and the Gulf states need enormous markets for their oil.

For years, China and the Gulf states have discussed ways to conduct more trade outside the dollar system.

But the Gulf monarchies faced a constraint.

They depended on the US security umbrella.

Moving too far toward China risked alienating the country they counted on to protect them.

The Iran war changes that calculation.

If the Gulf states conclude that Washington cannot protect them from Iran - and that the American military presence can turn their countries into targets - the value of that security guarantee falls.

They then have a powerful incentive to reach an accommodation with Iran while deepening economic ties with China.

That would weaken one of the political foundations supporting the petrodollar.

And China has spent years building an alternative.

From the Petrodollar to the Petroyuan - and Gold

China understands the biggest problem with asking an oil producer to accept yuan.

Why would Saudi Arabia, the UAE, or another exporter want to accumulate piles of Chinese currency?

Beijing has spent years developing an answer.

In 2018, the Shanghai International Energy Exchange launched a yuan-denominated crude oil futures contract. That gave oil producers another mechanism for pricing and trading crude outside the dollar.

But China has also built something that makes the yuan far more useful to commodity exporters: a path from yuan into physical gold.

An oil producer can sell crude into the Chinese market, receive yuan, spend those yuan on Chinese goods, or use China's financial and gold-market infrastructure to convert surplus yuan into physical bullion.

That changes the proposition. The exporter does not have to choose between holding dollars and accumulating piles of yuan. It can turn part of its trade surplus into an asset with no issuer, no counterparty, and no foreign government standing between the owner and the wealth.

Think about the difference.

Under the dollar system, an oil exporter sells a finite natural resource and receives financial claims issued by the US government.

Those claims carry political risk.

Washington demonstrated that risk when it froze Russia's reserves after the invasion of Ukraine.

Gold carries no such counterparty risk.

Nobody can print it.

Nobody can default on it.

And once an oil producer takes physical possession, no foreign government can freeze it with a keystroke.

From the perspective of a country trying to reduce its exposure to Washington, that has obvious appeal.

A viable path from oil to yuan to physical gold gives Gulf producers a way to reduce their dependence on the dollar without accumulating large reserves of Chinese currency. If the Iran war weakens confidence in US protection, the financial infrastructure needed to move away from the petrodollar already exists.

The Gulf states have a path from oil to gold that bypasses the dollar. But what happens to your wealth if they take it?

A loss of demand for dollars and US debt could erode your purchasing power and shake your investments. The time to prepare is before that shift gathers force.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden Tue, 10/06/2026 - 23:25

Kremlin Says Russians Should Ignore "Rumors" On Possible Plague Outbreak In Siberia

Kremlin Says Russians Should Ignore "Rumors" On Possible Plague Outbreak In Siberia

Authored by Jack Phillips via The Epoch Times,

The top Kremlin spokesman sought to tamp down "various rumors and speculation" about reports of a possible plague outbreak in Siberia and said that Russians should only monitor statements from government sources.

Kremlin spokesman Dmitry Peskov in Moscow on Feb. 18, 2022. Sergey Guneev/Sputnik/Kremlin via Reuters

"The leading agency with authority in this area is Rospotrebnadzor," Kremlin spokesman Dmitry Peskov said on Monday, according to Russian media outlet TASS, referring to Russia's national public health agency. "And it is Rospotrebnadzor's official statements that should be relied upon, without listening to various rumors and speculation."

"Rospotrebnadzor is home to highly qualified professionals in this field. Let's listen to their official statements," Peskov added.

The statement comes as Russian health authorities said they took preventative actions after the death of a laboratory worker at the Anti-Plague Research Institute of Siberia and the Far East near Irkutsk, Russian news agency Interfax reported on Oct. 4.

The worker was diagnosed with pneumonia of unknown origin, Rospotrebnadzor said, although officials haven't yet confirmed the cause of her death. It's also not clear when the worker died.

"Due to the patient's professional activities, upon receiving information, a comprehensive set of anti-epidemic measures was immediately and fully implemented in accordance with sanitary legislation," Rospotrebnadzor said over the past weekend.

That included finding "the widest possible circle of people who had been in contact with the patient," the health agency said.

The hospital has been placed under quarantine, Mayor Maxim Modin said on Oct. 2, no longer admitting or discharging patients, and its laboratory halted carrying out routine tests. The hospital's outpatient clinic kept operating as usual, he said.

On Monday, Igor Kobzev, the regional governor of the Irkutsk region, issued a statement on social media platform Telegram that testing has shown "no microorganisms related to her professional activities were found in the woman's biopsy specimens."

"The cause of her death was pneumonia of unknown etiology," Kobzev added. "Importantly, no new cases of Anti-Plague Institute employees seeking medical attention have been identified in the past few days."

The official described the "sanitary and epidemiological situation" in his region as "currently stable," without elaborating, before he thanked the chief of Rospotrebnadzor and its staff.

An independent Russian media outlet, Lyudi Baikala, reported that as many as 200 people in the area who came in contact with the laboratory worker have been placed under quarantine. Neither Rospotrebnadzor officials and Kobzev have commented on the number of people who were placed under quarantine.

Responding to the reports, a U.S. State Department spokesman told The Epoch Times on Monday that Trump administration officials are aware of reports of "a fatal case of suspected pneumonic plague" and is monitoring the situation.

"Many details have not been confirmed. We encourage Russian authorities to share accurate information quickly and openly," the State Department spokesman said.

The United Nations' World Health Organization (WHO) describes pneumonic plague as a less common but severe form of the infection caused by the bacteria Yersinia pestis, which is generally found in rodents, small mammals, and fleas.

"Plague can be a very severe disease in people, with a case-fatality ratio of 30 percent to 60 percent for the bubonic type, and it is always fatal for the pneumonic and septicaemic kinds when left untreated," WHO says on its website, referring to other forms of the disease.

Tyler Durden Tue, 10/06/2026 - 16:20

Germany's Former Spy Chief Arrested In Biggest Espionage Scandal Of The Century

Germany's Former Spy Chief Arrested In Biggest Espionage Scandal Of The Century

August Hanning, former head of the German BND foreign intelligence agency, which is Germany's equivalent of the CIA, has been arrested on espionage charges in a shocking and unprecedented situation in which a country's top intelligence officer and head of a national spy agency was caught spying for another state.

The 80-year-old faces formal charges including "treasonous espionage, spying out state secrets, attempted treason, and espionage" - according to German media. While an official statement from the prosecutor's office has not yet identified the foreign service he's suspected of working for, Israel has been widely named, also given this past well-documented associations and links.

August Hanning, via Associated Press

Curiously, Hanning's arrest at his home in Nordwalde in western Germany comes a full two decades after he left the top intelligence post. He served as BND chief from December 1998 to November 2005 before moving to the Federal Interior Ministry.

In short, it appeared he not only illegally held on to thousands of classified documents, but used them over the years to peddle influence - including preparing a presentation for a foreign intelligence service based on the internal government docs. What's more is he was covertly obtaining new documents even many years out of office.

Israeli media itself is highlighting that the way Hanning was caught actually involves shady Israeli operatives:

The affair rocking Germany involves thousands of classified documents, suspected payments, contacts with foreign intelligence officials and a surprising connection to Israel: The investigation that led to its exposure actually began with the case involving the abduction of millionaire heiress Christina Block’s children, in which Israelis were also implicated.

International reports at the time: "According to prosecutors, August Hanning, who once headed Germany’s domestic intelligence service, allegedly approached Peri [ex-Shin Bet head], now owner of the Israeli consulting firm CGI Group, to organize a team of Israeli operatives for the abduction. The team allegedly assaulted Hänsel, kidnapped the children, smuggled them into Germany, and handed them over to Block. A Danish court later ordered her to return the children to their father."

According to a summary of the plot coming to light through the high profile Christina Block case via Channel 7 Israel National News:

Hanning had already come under scrutiny by authorities as part of an entirely separate case - the case of Christina Block, heiress to a German restaurant empire, who is standing trial over the abduction of two of her children from Denmark to Germany amid a bitter custody dispute with her former husband.

That case also attracted attention in Israel. The investigation implicated Israelis, including security personnel, and reports about the affair also mentioned former members of Israel’s security establishment.

Hanning’s name was linked to allegations concerning an earlier attempt to return the children to Germany, claims that he denied. As part of that investigation, investigators searched his home and office in September of last year and seized equipment for examination.

That, according to the German investigation, is where the case took a dramatic turn. Secret BND documents were discovered on an electronic storage device seized from Hanning. The problem was obvious: Hanning had left the intelligence service in November 2005 and therefore should not have had access to current intelligence material.

More insane details from the Block case and kidnapping plot via The Guardian:

A second former high-ranking BND official has also been arrested, and the person's home also searched. That official is accused of handing over to Hanning additional secret documents in exchange for payment.

Some of the alleged details of the Block case are wild. It was Hanning that set up Block with the brutal Israeli contractors who dragged the children into the forest and bound them up:

That official has been identified only as Manfred D. - Hanning's own former chief of staff when he had been BND chief. Manfred D., who had continued on as chief of staff for Hanning's successors, was apparently from 2012 to March 2026 continuing to hand over a wealth of classified files to Hanning, despite his long having been out of government. Manfred D. is charged with "aiding and abetting attempted treason and espionage against the state."

German media is widely describing the espionage case as the "biggest espionage scandal of the century." Marc Henrichmann, who chairs the German parliament's intelligence oversight committee, declared in the wake of the high level arrests that "whoever allies themselves with the enemies of our liberal democracy will be found out."

    OCTOBER ONLY.$10 OFFYOUR NEXT ORDER.$30 min. Ends Oct 31. One per customer.GET MY $10 OFF →Signs you up for ZeroHedge Store emails. Can't be combined. Every order helps support ZeroHedge. Tyler Durden Tue, 10/06/2026 - 16:00

Nickelodeon's Parent Hub Is A Nightmare Woke Indoctrination Syllabus For Kids

Nickelodeon's Parent Hub Is A Nightmare Woke Indoctrination Syllabus For Kids

Authored by Steve Watson via Modernity.news,

The network that once sold slime and SpongeBob is running a parent portal that treats political activism as bedtime reading.

The children's channel has assembled a disturbing syllabus, and it wants the parents to administer it.

Libs of TikTok flagged nickparents, the network's own resource hub, on Monday.

The tiles are not subtle. Countering racism and anti-Blackness. Countering islamophobia. Celebrate LGBTQ+ families, "proud every day of the year." A GLSEN guide to combating "LGBTQIA+ discrimination." Gun violence. The Capitol attack. Vocabulary on "equity and race."

Nickelodeon's parent site hosts the guides, under a banner that reads "PARENT RESOURCES" and the line "We may not have all the answers...but we know some folks who might."

The folks, it turns out, are far left activist partners.

One tile points parents to "Talk & Take Action: A Guide to Countering Racism and Anti-Blackness," produced with The Conscious Kid. "Dismantling anti-Blackness begins with education," the educator version says, further noting "Teachers we're calling on you!"

A companion page, "How Kids Can Be Allies," opens with "No one is ever too young to learn how to be an ally." The Conscious Kid, Nickelodeon writes, "developed a list of actions to guide kids on how to be an ally to BIPOC. Share these actions with your children and continue the fight against racism and bias."

The list tells children to "take on issues of racial injustice as your own," to understand "systemic racism," and to "commit to doing the work" as "a daily, lifelong practice."

It's absolute indoctrination designed to make kids believe anti-black racism is rampant and out of control.

The roundup goes further. It points families to Ground Control Parenting, including posts Nickelodeon itself describes as "Talking to Your Children About George Floyd and Tips on Bringing Your Child to a Protest."

Showing Up for Racial Justice is recommended for "how to support protesters." A Nick News special, Kids, Race and Unity, hosted by Alicia Keys, comes with a discussion guide that states "children start receiving explicit and implicit messages about race from birth and begin to show racial bias by age 3."

Believe it or not, toddlers are not racist because Alicia Keys says so.

That is not a cartoon network explaining why sharing is nice. It is a Cartoon Network handing parents a protest manual and a claim that toddlers are already racially biased.

Next to the race guide sits "Talk and Take Action: Parents', Caregivers' and Educators' Guide to Countering Islamophobia," again written with The Conscious Kid.

The guide says it is "designed to provide parents and caregivers with the tools, tips, and language needed to talk about Islamophobia" and "simple, but empowering, action steps families can take together."

One of those steps is blunt: "The single most powerful thing you can do to combat Islamophobia is to learn about the Islamic faith."

Good lord.

The same document steers families toward "small acts of activism" and names political figures in its discussion material. A children's network is instructing households on how to police speech about a religion, under a clinical label that treats scepticism as a pathology.

Parents who have watched Islamist terror, grooming-gang scandals, and campus intimidation do not need a slime brand to redefine their concerns as a phobia.

The LGBTQ tiles are just as direct. "Celebrate LGBTQ+ Families" promises parents can be "proud every day of the year." The GLSEN tile is an educators' guide to "combating LGBTQIA+ discrimination."

Nickelodeon's caregiver version says the network is "proud to present this parent resource," packed with "key terms, conversation starters, a reading list, and a reflection journal, provided by Nickelodeon's partners at GLSEN."

GLSEN is not a neutral literacy charity. It is an advocacy group whose business is school gender policy. Nickelodeon has put that group's vocabulary in front of the people raising the audience.

The same grid offers "Discussing Gun Violence with Kids" and "How to Talk About the Capitol Attack." That's one thing for the likes of CNN. A preschool-to-tween channel packaging race ideology, religious-speech rules, gender doctrine, guns and January 6 as a parental product is quite something else.

None of this arrived in a vacuum. We've previously highlighted how Nickelodeon put a drag performer in front of children for Pride.

The clip, first pushed years earlier and still circulating, features drag performer Nina West singing through the colours of the Pride flag. Fox News quoted the lyric: "Baby blue, pink and white represent transgender people because every letter in LGBTQ plus is equal. And Black and Brown represent the queer and trans people of color."

Nickelodeon's own YouTube description calls it an original song "about the meaning of the rainbow Pride flag" and tells viewers "June is Pride Month, so let's celebrate by lifting up voices in the LGBTQIA+ community!"

The same performer fronted a Blue's Clues Pride parade sing-along. Yahoo reported the lyric "Ace, bi and pan grown-ups you see can love each other so proudly," and quoted the team calling it "the queerest thing I've ever seen happen in the preschool space."

During the pandemic, in June 2020, as riots spread after the death of George Floyd, ViacomCBS cable channels, including Nickelodeon, went dark for 8 minutes and 46 seconds.

Newsweek reported the on-screen line: "Nickelodeon is going off the air for 8 minutes and 46 seconds in support of justice, equality and human rights." CNN reported that the spot flashed "I can't breathe" over the sound of gasping, and that chief executive Bob Bakish described the purpose as to "honor George Floyd and pay tribute to other victims of racial violence."

Parents filmed children asking for the channel to be turned off. The Independent reported Nickelodeon's reply to the complaints: "Unfortunately, some kids live in fear everyday. It is our job to use our platform to make sure that their voices are heard and their stories are told."

The network then aired a "Declaration of Kids' Rights," which Newsweek and CNN both quoted in part: "You have the right to be seen, heard and respected as a citizen of the world... You have the right to be treated with equality, regardless of the color of your skin... You have the right to an education that prepares you to run the world."

A kids' channel appointed itself the ministry of fear, then scolded parents for noticing their children were scared.

The programming has matched the pamphlets. In 2014, The Legend of Korra ended with its lead in a same-sex relationship, a first for a Western children's cartoon of that profile.

In June 2020, Nickelodeon's official account posted "Celebrating #Pride with the LGBTQ+ community and their allies this month and every month," with graphics of Korra, transgender actor Michael D. Cohen, and SpongeBob.

Creator Stephen Hillenburg had long described SpongeBob as asexual and had said he never intended to write sexuality into the series. The corporate account folded the character into the campaign anyway.

Parents are not confused about what this is. A channel that wants to sell them cartoons has spent years selling them a politics: race as original sin, dissent about Islamic extremism as a phobia, gender ideology as a family craft project, and the living room as an organising cell.

Anyone still sitting their kids in front of this is directly complicit in fostering the next generation of mentally deranged far left radicals.

Tyler Durden Tue, 10/06/2026 - 15:45

Trump To Unveil Anduril Deal, Bringing Submarine Parts Factory To Baltimore

Trump To Unveil Anduril Deal, Bringing Submarine Parts Factory To Baltimore

Bethlehem Steel's Sparrows Point complex near crime-ridden Baltimore City was once the largest steelmaking facility in the US and viewed by some as once the world's largest steel mill.

Decades of deindustrialization led to the mill's closure in 2012. By 2014, the 3,300-acre site entered a redevelopment phase and was transformed into a giant logistics and industrial complex under new ownership called Tradepoint Atlantic. 

Tradepoint Atlantic is set to enter a new chapter, with Anduril Industries having won a $2.9 billion US Navy contract to manufacture components for Virginia-class nuclear-powered attack submarines there.

According to The New York Times, Palmer Luckey's defense company plans to invest $3.7 billion in the project and directly create more than 3,000 jobs. The new shipyard is expected to open in 2030.

"We need to grow the maritime industrial base, the submarine industrial base, so that we can produce more submarines," Anduril Chief Strategy Officer Christian Brose was quoted as saying.

Left-wing Maryland Governor Wes Moore and other state Democrats are expected to attend the announcement following lengthy negotiations over the redevelopment plans. Maryland and Baltimore County are expected to provide hundreds of millions of dollars in tax subsidies.

The former Bethlehem Steel site has undergone a total transformation. It combines warehouses, distribution centers, industrial facilities, deepwater shipping terminals and rail connections to CSX and Norfolk Southern. Tenants include Amazon, FedEx, Under Armor, Home Depot, Volkswagen, BMW and others.

"President Trump knows a self-sustaining domestic shipbuilding sector is critical for national and economic security," said Anna Kelly, a White House spokeswoman.

Luckey commented on The Wall Street Journal's report on Monday, which said the site would manufacture drone boats, calling the reporting "false."

Brose said manufacturing drone boats or unmanned weapons of war was not part of the site's initial plans.

Hopefully, Tradepoint Atlantic brings stable, goods-producing jobs to the metro area, which has experienced decades of deindustrialization under Democratic control, leaving the crime-ridden city whose population has collapsed to a 100-year low. 

Tyler Durden Tue, 10/06/2026 - 15:20

Office CMBS Delinquency Rate Re-Spikes To 12.2%, Far Worse Than Financial Crisis Peak As End Of Extend-And-Pretend Looms

Office CMBS Delinquency Rate Re-Spikes To 12.2%, Far Worse Than Financial Crisis Peak As End Of Extend-And-Pretend Looms

Authored by Wolf Richter via WolfStreet.com,

The dictum morphs from "Survive till '25" (when low interest rates were supposed to return) to "Sell at today's price, or the lender will."

The delinquency rate of office mortgages that have been securitized into commercial mortgage-backed securities (CMBS) re-spiked in recent months and in September hit 12.2%, the second highest ever, behind only January 2026 (12.3%), and 1.5 percentage point above the worst moments of the Financial Crisis, according to data by Trepp, which tracks and analyzes CMBS.

The biggest driver of the increase in September was a $1.1 billion maturity default on a loan that had matured in August, and was not paid off. That loan was securitized in 2021 and the different slices of CMBS were sold to institutional investors around the world at the time. The banks that originated the loan are off the hook.

The loan is backed by eight office and film-studio properties of 2.2 million square feet in Hollywood, whose largest tenants are Netflix and 20th Century Fox. But two of the Netflix leases and the 20th Century Fox lease, representing 30% of the net rentable area, are expiring soon, and renewals are still up in the air.

Extend and pretend forevermore?

The $1.1 billion Hollywood loan that went into maturity default in September had been transferred to special servicing in July 2026. The loan is backed by five Class A office towers built between 2008 and 2021 and three film-studio properties, totaling 2.2 million square feet, all located within a mile of each other in Hollywood. The borrowers are the mega-landlords Blackstone Property Partners and Hudson Pacific Properties.

The special servicer that is now managing the loan, representing the CMBS holders, is SitusAMC, the largest special servicer by unpaid principal balance ($111 billion as of January), according to SitusAMC.

Netflix is the largest tenant, leasing 57.8% of the net rentable area (NRA). One of its leases expires in January 2027 (7.0% of the NRA) and another lease expires in June 2028 (17.2% of the NRA), totaling 24.2%. Discussions with Netflix about lease renewals are ongoing, according to SitusAMC, cited by Fitch Ratings, which rates the CMBS.

20th Century Fox is the second largest tenant. Its lease, accounting for 6.4% of the NRA, expires in December 2026. The decision to renew the lease is awaiting confirmation on whether studio productions will be renewed for additional seasons, and the "outcome will determine if the leases will be extended," according to Fitch, citing the special servicer.

Here is the extend and pretend: The loan was recently modified, and the borrowers, Blackstone Property Partners and Hudson Pacific Properties, were granted a 14-month maturity extension through November 9, 2027, at the current (far below market) fixed interest rate of 4.435%, according to Fitch, citing the special servicer. To get the extension, Blackstone and Hudson Pacific agreed to fund a leasing reserve with $20 million from sources other than property cash flow. Fitch noted that the loan would remain subject to a "full cash trap" until full repayment, with all excess cash flow being directed to the leasing reserve.

Citing the risk that the Netflix and 20th Century Fox leases will not be renewed, Fitch changed its rating outlook to "negative," putting the CMBS in line for a downgrade "if market conditions, valuations, and/or actual portfolio performance deteriorate beyond Fitch's current expectations of sustainable performance, particularly if the borrower is unable to address upcoming lease rollover risk."

The properties were 84.9% occupied in July, down from 91% in September 2025. But the upcoming lease expirations of 30% of the NRA, if not rolled over, would leave nearly half of the space in the properties vacant.

A $470 million loan on office properties in downtown Houston was the second largest driver behind the increase in the default rate as it missed the maturity payoff earlier, according to Trepp.

The loan, originated and securitized into a single-borrower CMBS in 2021, is backed by the 34-story 1.0 million sq. ft. One Allen Center, completed in 1972; the 50-story 1.2 million sq. ft. Three Allen Center, completed in 1980; and an adjacent 6-story parking garage with a health club on top. Brookfield Properties is the landlord.

The interest-only loan comes with a floating rate of SOFR plus 3.08%. After the Fed's most recent rate hike, SOFR has been about 3.88%, which would move the current rate on the loan to 6.96%. Another rate hike by the Fed will move the loan's interest rate to about 7.2%. The loan was originated when SOFR was near 0%.

The property is 71% occupied. The largest tenants include Freeport LNG, Motiva, and Plains Marketing, according to Trepp.

S&P Global, which rates the CMBS, noted in March that it was concerned Brookfield Properties would not pay off the loan at the "final extended maturity date" in April. And that maturity date came and went without payoff.

Trepp said that the loan's move to non-performing status in September could reflect the ongoing loan negotiations.

The idea is to extend and pretend some more until interest rates come back down to 2% or whatever, which might allow for the loan to get refinanced.

Extend-and-Pretend Not Forevermore.

This extend and pretend, or the end thereof, was the theme in today's First Draft, a note that CRE publication Bisnow sent to subscribers. The note would be hilarious if it weren't so serious, or both:

"One of this industry's favored pastimes is the slogan, and for years it reprised one Rialto's Joe Bachkosky recalled onstage: 'Survive until '25.' But when 2025 failed to deliver, it turned into 'bliss in '26.' Lately, a few idealists have floated 'heaven in '27,' which sounds less like a prophecy every week and more like a prayer."

Mark Bonner, Bisnow's editor-in-chief and author of the note, continued:

"AEW's Lauren O'Neil called the moment 'a shift back to fundamentals,' which is industry speak for when the spreadsheet voodoo stops working.

"KBS' Sondra Wenger said today's distress 'is in the structure,' a murky way of saying the building is fine, but the price paid for it isn't.

"Poverni Sheikh Group's Eugene Poverni said the risk curve has 'slid one to the right,' meaning buyers want value-add returns for core-plus risk. Translate that once, and buyers want more for less, but translate it twice, and prices start to tumble.

"Meanwhile, refinancing is all but dead.

"That could mean an apartment building that runs smoothly day to day is in trouble anyway because someone paid a 3-cap for it in 2021. At the time, the price made sense. On Sept. 30 of that year, the 10-year closed at 1.52%, with the Fed's benchmark rate near zero. Five years later to the day, as many of those loans come due, the 10-year closed at 5.29%."

And Bonner concluded:

"But last week, the people holding the capital stopped pretending, and it seems like 'survive until 25' finally has a successor. It does not rhyme, and nobody will put it on a panel slide: Sell at today's price, or the lender will."

Tyler Durden Tue, 10/06/2026 - 15:00

The $1 Million Tanker Was Just The Start: Every Crude Freight Index Hits Record High As Hormuz "Works" Too Well

The $1 Million Tanker Was Just The Start: Every Crude Freight Index Hits Record High As Hormuz "Works" Too Well

Just when we thought crude tanker rates couldn't go any higher, they did - again.

A week ago, a record million dollars a day charter for a supertanker was the punchline. Now it's the floor: the Baltic Exchange's TD3C, the benchmark Saudi Arabia-to-China VLCC route, hit yet another all-time high of $1.33 million per day on Monday, up 10% on the week and 21 times where it was a year ago!

But the real fireworks are elsewhere. As Lloyd's List's Greg Miller writes, the tanker market's "cascade" effect has gone into overdrive, with record VLCC strength spilling into suezmaxes, and suezmax demand in turn dragging up aframaxes:

Crude tanker markets hit a tipping point in mid-September, surging to a new level as more crude exited the Strait of Hormuz. Over the past three days, rates crossed another tipping point, spiking even higher due to the lagged global 'cascade' effect.

In other words, the better the Hormuz shuttle "works", the more expensive it gets to ship a barrel anywhere in the world.

Let's take a closer look at the carnage segment by segment, what Goldman, JPM and BofA say is driving it, and why the only thing standing between owners and $1.6 million a day is the refining margin.

"Available Tonnage Is Vacuumed Off Position Lists The Second It Is Marketed"

Regular readers know we have been tracking the tanker rate crisis since before it was cool - specifically February 20 - a week before the first Iran shots were fired, when the Baltic's Middle East-China VLCC route had "only" tripled to $151K a day. We were also on the $1 million milestone before it happened: "Mideast Chaos Sends Supertanker Rates Soaring To Near Record $1 Million A Day", a headline we upgraded from $800K within hours. Then on Sept 23, with rates on the Gulf-India route nudging $1 million, we put out this chart:

What changed in the past week?

According to Lloyd's List, Gulf producers decided to push more tankers through Hormuz under US military protection (even as Iran ratchets up attacks: UKMTO confirmed two separate projectile strikes on crude tankers in and around the Strait just over the weekend), which sharply increased near-term cargo supply and pulled more VLCCs to wait for ship-to-ship (STS) transfers in the Gulf of Oman. Clarksons Securities puts the wait for an STS slot at seven to 10 days, and estimates STS volumes have surged from 5-6 million barrels a day a month ago to 12 million b/d.

And since VLCCs loading via STS in the Gulf of Oman earn about 50% more than VLCCs loading in the Atlantic, with a much shorter ballast leg from Asia, owners are doing the rational thing. As Poten & Partners' head of tanker research Erik Broekhuizen put it:

"Even in a crazy market, shipowners tend to make rational decisions. The earnings discrepancy has kept VLCCs closer to the Asian market, leaving it to suezmaxes and aframaxes to do the heavy lifting out of the US Gulf, turbocharging their earnings."

Translation: the Atlantic has run out of supertankers. With few ballast VLCCs around, charterers have been forced to split 2 million-barrel stems into 1 million-barrel suezmax cargoes, and the result is what Fearnley Securities calls a market where "available tonnage is seemingly vacuumed off position lists the second it is marketed." Sparta Commodities summed it up even more concisely: "Atlantic freight is repricing violently on real tightness."

Parabolic Suezmaxes

Suezmax owners are the big winners. Atlantic basin suezmax rates more than doubled in three trading days, and they were already at or near record highs before the latest jump. On Monday:

  • US Gulf-Europe: $577,792/day, up 150% w/w
  • Guyana-Europe: $584,012/day, up 150% w/w
  • West Africa-Europe: $567,138/day, up 145% w/w
  • Black Sea-Med (with a Russia-Ukraine war premium on top): $801,077/day, up 115% w/w

Every single one of the Baltic Exchange's suezmax indexes hit an all-time high on Monday. For context, the US Gulf-Europe route was paying $90K at the start of September.

And now the cascade is running in reverse too: with suezmaxes (half the cargo) earning more than double what VLCCs do in the Atlantic, VLCC owners are simply holding out for more. The Baltic's West Africa-China VLCC index jumped 43% w/w to $697,160/day and US Gulf-China rose 20% to $473,958, both all-time highs. The Oman-China route, the one that actually captures the STS shuttle trade, was steadier at an "astronomical" $860,580/day, just shy of its Sept 17 record.

As for TD3C, Lloyd's List notes it is "perhaps the least relevant" index to actual owner earnings since almost no one sails direct from Saudi Arabia to China anymore - most crude is shuttled out to STS positions in a two-step process - but as a proxy for the total freight bill it is hard to beat. Nothing says "orderly market" like the benchmark route nobody uses hitting a record every week.

The Aframax Record Books Get Rewritten

Atlantic aframaxes had their moment in March, when panicked Asian buyers booked unusually long-haul aframax loads out of the US Gulf to replace Mideast crude. Those peaks were never revisited... until now. On Monday the Baltic's US Gulf-Europe aframax index was at $313,794/day (+44% w/w), Cross-Med at $343,227 (+19%), Caribbean-US at $335,288 (+70%) and North Sea-Europe at $348,651 (+10%). In early September most of these were paying $45K-$100K.

"Increased suezmax activity continues to provide further support for aframax demand," said Clarksons in its Monday brokerage report. Put simply, there is no class of crude tanker left that isn't being squeezed. And for those looking for the long-term perspective, here is John Kemp's inflation-adjusted Baltic Dirty Tanker Index: at 6,242 in October, it is now the highest on record in real terms, blowing past the November 2004 peak of 5,195.

Goldman: Gulf Exports Are Back... Which Is Exactly The Problem

Here is the paradox. Normally, more oil getting out of the Gulf would be bearish for freight. Not this time. As Goldman's commodity team wrote last week in "Adaptation: Persian Gulf Exports Return to 2025 Level" (available to pro subs), which we discussed at the time:

We estimate that Persian Gulf oil exports, including estimated "dark exports", have recovered to 23.3mb/d over the last week, in line with their 2025 average, as exports doubled in September. Increased Hormuz exports, including via ship-to-ship transfers, have driven the recovery despite the attack on the Saudi East-West pipeline (which disrupted flows to Yanbu for nearly two weeks) and the continuing Houthi blockade of Saudi exports via Bab-al-Mandab. Crude accounted for nearly 90% of the September recovery, reaching 19mb/d (108% of 2025 average)...

But while the barrels are back, the logistics are not.

A pre-war barrel took one voyage from Ras Tanura to Ningbo; today it takes a dark transit, a shuttle run, a 7-10 day wait off Fujairah or Sohar, a ship-to-ship transfer and then the long haul. Every one of those steps ties up tonnage. It's also why we have been saying since early March that Fujairah and the Hormuz bypass routes would become the center of the oil universe (a call Abu Dhabi is now putting tens of billions behind), and why the US Navy's billion-barrel escort operation has been, from the owners' perspective, the gift that keeps on giving.

JPMorgan's top oil strategist Natasha Kaneva made a similar point in her latest Oil Flash Note (available to pro subs): Hormuz throughput was back to ~13 million b/d, but "SoH transmission is not due to improved safety but improved ability to operate under risk," and freight rates were "~$1.27mm/day, a record." (They are higher now.) Goldman also points out that refined products are more flammable than crude, so the physical risks of a Hormuz crossing are greater for product tankers, which is one reason Gulf product exports are still stuck at ~50% of 2025 levels while crude is at 108%.

Meanwhile, Goldman's Rich Privorotsky summed up the market's take on Monday: "Plenty of threatened escalation and additional tankers hit, but diplomatic pathways remain open and, crucially, oil is getting out of the Gulf." Yes it is - at $1.33 million a day.

How High Can It Go? Ask The Refiners

For decades, $100,000 a day was the psychological bellwether of a VLCC upcycle. As Lloyd's List puts it, tanker shipping's "Overton window" now has an extra zero. Or as DNB Carnegie shipping analyst Jorgen Lian confessed at last week's Capital Link conference: "Our imagination is obviously not imaginative enough, because we've been lagging the reality by far." Spoken like a true sell-sider.

So where is the ceiling? It's set by the (parabolic) crack spread. If importers pay so much in freight that they can't earn a profit refining the crude, they stop shipping it. And with cracks at historic highs, that ceiling is a lot higher than anyone thought. Clarksons Securities lays out the math:

"As capacity gets scarcer, the balance shifts from owners competing for cargoes to charterers competing for ships. This is why refining margins matter so much. Once the supply curve is close to vertical, the question increasingly becomes how much the marginal cargo can afford to pay."

Per Clarksons, every $10/bbl increase in crude freight lifts VLCC TCE by ~$400K/day. Citing Argus, it estimates the Singapore product slate sold for $151/bbl last week, implying a pre-freight refining margin of ~$40/bbl, against Oman-Asia VLCC freight of ~$21/bbl, meaning "there is still considerable margin left for VLCC owners to capture." If owners grabbed the entire margin, which Clarksons admits is "unlikely in practice", Oman-China VLCC rates would be almost double current levels, at $1.6 million a day.

BofA's numbers back that up. The bank's Asian refining margin has been holding at roughly $35-45/bbl since August, more than four times its 5-year average (for more details see BofA's latest "The Oil Gusher" note)....

... while its European refining margin is at ~$49/bbl, with diesel cracking ~$90/bbl over Brent. That makes sense to anyone who has followed our coverage of the record diesel crack and Goldman's "nightmare" refining crisis warning; as we put it over the weekend, the US doesn't have an oil problem, it has a refinery problem. Turns out, so does the tanker market, only in a good way (for owners).

Two more factors stretch the ceiling.

  • First, energy security: state-controlled buyers may "temporarily overpay for freight to secure volumes now", particularly if they worry US protection of the shuttle tankers isn't guaranteed indefinitely.
  • Second, the share of freight in the delivered cost of crude, which Poten's Broekhuizen estimates has gone from ~3% at the start of the year to 27% now. Unprecedented for crude, though Breakwave Advisors notes Atlantic-to-China freight was more than 40% of landed iron ore cost last week - and capesize rates are nowhere near record highs. In other words, by dry-bulk standards, there is still room to run.
The Catch: Rates Don't Need More Ships To Fall

Before anyone extrapolates $1.6 million, Clarksons offers a crucial caveat:

"The reverse is also important. Rates do not need more ships to become available before they fall. If refinery margins weaken, charterers' willingness to pay can fall sharply even while vessel availability remains tight."

And that is where BofA comes in with the counterpoint. Its European refining margin strip is already in "(slight) backwardation", with the 4Q26 strip below the 3Q26 average of more than $42/bbl, and the bank models refining margins dropping to $15/bbl by end-2027. BofA's US refining team (in its "Refining roundup", also available to pro subs) is equally skeptical that the market should be paying up for a permanently higher crack, reiterating its "hesitance to buy into a +$3/bbl LT midcycle crack valuation." If the crack goes, the ceiling on freight goes with it - and we've seen this movie before: in June, tanker rates nearly halved in days on Hormuz normalization hopes, right after earnings had soared to $470,000 a day.

Meanwhile, the war itself isn't getting any calmer: per Bloomberg, the US blockade has now bottled up at least 50 tankers carrying Iranian oil, while Tehran's parliament speaker says the Strait won't fully reopen until the US meets seven conditions. Which, for now, is bullish for freight - right up until the ceasefire headline that sends it the other way.

Bottom Line

Lloyd's List puts the commercial logic simply: the spot rate "can be whatever charterers are willing to pay," with the caveat that charterers will, as financial pain increases, belatedly expand period coverage and reduce spot exposure. Or as Clarksons put it, "the rapid increase in Middle East crude flows has put the squeeze on all tanker classes."

Our take: with refining margins at $40+/bbl and Gulf barrels needing two or three ships to get to market instead of one, there is still near-term upside, and the Atlantic cascade has further to run as VLCC owners hold out for suezmax-equivalent economics. But the more important number may not be a TCE at all: freight is now 27% of the delivered cost of a barrel, which makes this an inflation story as much as a shipping one (as Bloomberg's Javier Blas warned in "The Next Inflation Shock: $1 Million-a-Day Oil Tankers" two weeks ago).

And when the owners themselves start ringing the register - Trafigura's tanker arm Volare jumped in its Oslo debut on Monday "as a wave of shipping IPOs builds" - history suggests the people who know ships best are selling them to the people who know them least. Enjoy the $1.33 million a day while it lasts: in shipping (as in everything else) nothing cures record rates like record rates.

Much more in the full Goldman "Adaptation: Persian Gulf Exports Return to 2025 Level" note and BofA's "The Oil Gusher: 3Q26 Playbook Part I" and "Refining roundup" notes, all available to pro subs.

Tyler Durden Tue, 10/06/2026 - 14:40

The Education Cartel And The Blue State School Scam

The Education Cartel And The Blue State School Scam

Authored by Jonathan Turley via JonathanTurley.org,

Below is my column in the Hill on the education cartel and how it is destroying our K-12 school system. After decades of bloated budgets and failing scores, our school system is now less popular than Cuba and communism. It is a particularly telling comparison in Chicago where union members went to Venezuela to praise the worker's paradise of the Maduro regime while the school system dumped U.S. bonds in opposition to the American "regime." Generations of inner-city children are being left without a future due to the failure of our school system, which prioritizes its own survival over its students.

Here is the column:

"In the first place, God made idiots," Mark Twain once wrote in an 1879 travel book. "That was for practice. Then he made school boards."

It appears that most Americans now agree with him. New polling shows that K-12 education has now reached a record low in the number of people who are even "somewhat satisfied" with the state of education in the U.S.

What is most troubling is that the near-total contempt for our school system does not make a bit of difference. Families and students have become largely irrelevant to an education cartel, a self-sustaining, self-perpetuating political alliance of unions and politicians.

According to Gallup, only 32 percent of American adults say they are "completely" or "somewhat" satisfied with the quality of K-12 education. That is the lowest figure in Gallup's 27 years of asking the question. Public satisfaction with the school system has dropped almost 20 points since just 2024.

For many of us, neither the drop in public support is surprising. The collapse comes at a time when universities are reporting that college students are entering higher education without basic math and other skills.

We have also seen the dismal decline in standards at elite universities like Harvard, where faculty have been compelled to teach high school-level math classes to students.

In May, faculty in the University of California system (which eliminated standardized testing to achieve greater equity in admissions) reported an alarming lack of math knowledge among new students.

Most recently, a University of California, San Diego, faculty report found a nearly 30-fold increase since 2020 in incoming students whose math skills fell below a high-school level.

For many of us, neither the drop in skills nor public support is surprising. For generations, the public school system has failed students in major cities. Despite massive budget increases, actual test scores continue to fall or remain at subpar levels.

In a prior column, I was particularly moved by the frustration of a mother in Baltimore who complained that her son was in the top half of his class despite failing all but three of his classes. Her story led to my changing my view of school vouchers. Despite my long support for public schools, I believe vouchers may be the only way to wrest control away from the education cartel by introducing real competition based on academic performance.

Faced with low proficiency scores, teachers' unions and school administrators have continued to lower proficiency requirements. They are simply pushing students out the door without basic skills, robbing these kids of any chance to break out of cycles of poverty and unemployment. When confronted with their poor performance, school board members have declared meritocracy to be a form of "white supremacy." Gifted and talented programs are being eliminated in the name of so-called "equity."

In any other field, such generational failure would be unthinkable. No business or enterprise could sustain itself. However, that is the point. There is little competition in this system. Blue states have largely blocked voucher systems while protecting teachers from performance-based standards.

Actual students have become irrelevant to budgets. In Chicago, there are schools that remain open despite 80 percent vacancy rates. One school, Frederick Douglass Academy High School has only 27 students, or 2 percent of its building's capacity. The school system spends $55,000 for each student at Frederick Douglass Academy.

Overall, 35 percent of Chicago schools are half full or less. But that did not stop the schools from spending a couple million on transcendental meditation sessions or giving teachers and students days off to join May Day protests (with city-subsidized buses).

According to a recent study, in 2025, Chicago Teachers Union spent a record $4.2 million on politics and lobbying but less than 18 percent on representing teachers. This included massive contributions used to elect former teacher and union organizer Mayor Brandon Johnson, a former organizer for the union. Johnson, in turn, has effectively turned over his office to the far-left union.

In economics, there are few scourges older and more damaging than the cartel, which uses its power over an area to create "higher prices, lower quality, and stifled innovation." There is a natural tendency for people to form such groups to stifle competition and feather their own nests. Adam Smith warned that "People of the same trade seldom meet together, even for merriment and diversion, but the conversation ends in a conspiracy against the public."

The Education Cartel is becoming one of the greatest and most insidious forms of such anti-competitive conduct. Teacher unions have used hundreds of millions of dollars in campaign contributions to acquire unchallenged power in blue states where they can dictate ever-increasing salaries, pensions, and budgets. One estimate found that, since 2015, the nation's two largest teachers unions - the National Education Association and the American Federation of Teachers - spent $669 million on federal campaigns and another $336 million on state and local campaigns.

Figures such as Randi Weingarten with the American Federation of Teachers effectively made their unions piggy banks for the Democratic Party and appear at far-left rallies to support Democratic causes. In return, Democratic leaders give this cartel most everything that the demand, including barring competition in the form of public vouchers or tying budgets to improving the education of actual students.

It is a closed circuit. Democratic leaders increase school budgets and salaries and the unions then send back hundreds of millions to fund Democratic campaigns.

If you want to understand the priorities of the unions, just watch one of National Education Association head Becky Pringle's unhinged speeches. Her declarations that the union will "win all of the things" clearly did not include educational improvements for students.

A recent study found that blue states with strong teachers' unions overwhelmingly have worse student literacy scores than red states. At least eight of the ten states with the worst literacy scores were liberal districts with politically powerful teachers' unions, according to the Progressive Policy Institute.

For example, in New York, more than half of third- to fifth-grade students failed their reading proficiency exams this year. And it isn't about money: The state spends almost $37,000 per student to fund this bloated, poor-performing bureaucracy. But the unions also pump political contributions into the campaigns of Democratic leaders in every election, and nothing changes.

In the meantime, historically poor states like Mississippi and Arkansas, with relatively new voucher and performance-based systems, are showing major improvements in scores among their students. Yet when these same policies are proposed in blue states, they are routinely blocked by the powerful teachers' unions.

Many liberals instinctively support unions and schools despite their costs. Recently, former New York Times journalist (and now Howard University Journalism Professor) Nikole Hannah-Jones drew criticism over an exchange with her daughter when she discussed her disappointment that her daughter would not stay at a majority-black, inner-city school despite its poor conditions and resources. Her daughter finally insisted on going to a private school out of concern for her own future as opposed to what Jones called supporting "her life's work."

Most families do not have the resources of Jones to make that choice. They are captives to a system that appears entirely detached and unresponsive to their same concerns as Jones's daughter.

The mark of a cartel is that it controls competition while inflating profits or costs. However, the education cartel makes you long for the old oil or even drug cartels. The difference is that the education cartel actually charges cartel prices while producing diminishing products. It is like OPEC watering down the gas at the pump while pumping up the price. Everyone is getting windfall profits, from the unions to the politicians. Only the kids are being shortchanged by America's school system.

Jonathan Turley is a law professor and the New York Times best-selling author of "Rage and the Republic: The Unfinished Story of the American Revolution."

Tyler Durden Tue, 10/06/2026 - 14:20

Ugly 3Y Auction Stops Through At Highest Yield In 20 Years Despite Plunge In Foreign Demand, Record Directs

Ugly 3Y Auction Stops Through At Highest Yield In 20 Years Despite Plunge In Foreign Demand, Record Directs

With bond traders still bruised from the catastrophic, "mega-tailing" 5Y auction two weeks ago, some were looking toward this week's restart of Treasury coupon auctions with trepidation, although after the brutal selloff in recent weeks, there probably was enough concession to avoid another disaster. And sure enough, after we got the results of of today's $58BN three-year auction, everyone can exhale because the auction was a bit better... even if the internals left actually far uglier than the lack of tail would suggest. 

Starting at the top, the auction stopped at a high yield of 4.932%, up sharply from 4.475% last month, and the highest since May 2006. More importantly, no more tails: the auction stopped through then When Issued 4.934% by 0.2bps, the 4th consecutive stop through in a row.

The bid to cover dropped to 2.616 from 2.722, below the 6-auction average.

The internals were uglier: Inidrect buyers slumped to 57.59%, down from 62.15% and the lowest since February. And with Directs awarded 31.66%, or just shy of the highest on record...

... Dealers were left holding 10.7%, a drop from last month's 10.9% and below the recent average of 12.6%.

Overall, this was an uglier auction than the lack of tail would make it out, and the plunge in Foreign buyers (Indirects) was only offset by a near-record Direct bid as not even rates trading at 24 year highs was sufficiently attractive for foreign buyers. 


Tyler Durden Tue, 10/06/2026 - 13:24

Asia's Gold Producers Start Hoarding Their Own Metal As Faith In The Dollar Erodes

Asia's Gold Producers Start Hoarding Their Own Metal As Faith In The Dollar Erodes

For most of modern history, the gold trade worked one way: emerging-market mines dug it up, shipped it out (often as cheap ore, more often through the back door), and London and New York did the rest. But that arrangement is now quietly breaking down.

According to a must-read report in Nikkei Asia, countries across Asia are moving to capture more of the value from the gold boom by refining domestically, taxing exports and having their central banks buy local production. Nikkei calls it "a new form of resource nationalism", and one that "could exert upward pressure on gold prices over the medium to long term." The two reasons it gives will be very familiar to regular readers: waning confidence in the US dollar as the world's reserve currency, and the fact that dollar assets of countries at odds with Washington have been frozen under sanctions.

In other words, the world's gold producers have noticed the same thing the world's central banks noticed in 2022: gold is the one reserve asset nobody else can freeze, and they are sitting on top of it.

Below we walk through who is hoarding gold and how, why Goldman thinks central-bank (and now producer-country) demand is doing "nearly all" the work in its $5,400 gold forecast, and why - for now - none of that has been enough to beat a hiking Fed.

From Vientiane To Jakarta: Everyone Wants A Refinery Now

Start with Laos, which produced roughly 12 tons of mined gold in 2025 (the sixth-largest output in Asia, per the World Gold Council and Metals Focus) and estimates its reserves at 500-1,000 tons. Until now, most of that left the country as ore, "through both official and unofficial channels." In 2024 the government set up the Lao Bullion Bank, which aims to refine local gold at home, raise gold's share of the country's FX reserves, and give citizens a trusted place to store their savings. Laotian PM Sonexay Siphandone now calls gold development "a key priority in strengthening our economic foundation." The head of the Japan Bullion Market Association, who attended the launch event, described the speed of the build-out as "astonishing."

Indonesia, the world's 10th-largest producer at more than 100 tons a year, is going further: it announced last year an export tax of up to 15% on gold, effective 2026, because domestic supply can't keep up with local investment demand. Regular readers will recall that we flagged Jakarta's levy (Nov 17, 2025) when it was still in its "final stage," complete with a sliding scale that rises with the gold price. At roughly $4,150/oz, a 15% duty works out to about $620 an ounce, which is a very polite way of saying "please don't export this."

And then there is China, the world's largest producer at a little over 380 tons a year (about a tenth of global output), which is also a major importer. As market analyst Jeff Toshima told Nikkei, "As a rule, taking gold out of the country is restricted." More on Beijing below.

The trend isn't limited to Asia. Madagascar's central bank has been buying domestically produced gold since the early 2020s under a Gold Purchase Program that its gold operations supervisor calls "the cornerstone of this reserve diversification strategy." Ghana, the world's sixth-largest producer, signed an MoU with the WGC in July to curb illegal mining and make sure "the benefits of Ghana's gold resources are realized by our communities and our nation as a whole."

Translation: the cheap ore pipeline to Western refiners is narrowing, and the people who run those refiners know it. "From the perspective of major international refiners ... absolutely this trend will have an impact on their ability to source," Metals Focus MD Nikos Kavalis told Nikkei. Toshima also supplied the historical irony: "Gold from the colonies flowed into London and helped underpin the British Empire's gold standard." The colonies, it seems, would now like to keep the gold.

Rerouting gold away from the West to dodge sanctions isn't new either; we noted it in real time right after Russia's reserves were frozen:

The Sanctions Premium

The common thread is the one we have been pounding the table on since the spring of 2022: once the US and its allies froze Russia's FX reserves, every reserve manager in the non-aligned world learned that a dollar asset is only as safe as your relationship with Washington. ANZ's Geullim Yum put it diplomatically to Nikkei: as the dollar-centered system "comes under scrutiny, gold is gaining importance as an asset insulated from the political and fiscal policies of any single country."

The data back it up. As SocGen's cross-asset team noted in its "China is buying gold again. Are you?" note (available to pro subs, and which we discussed last month), the dollar's share of global FX reserves fell to 57% in 2025, down more than 5 points since 2022, while 62% of reserve managers in the 2026 central bank survey expect it to keep declining moderately over the next five years and 84% expect gold to make up a bigger share of their reserves.

SocGen's summary is about as blunt as sell-side prose gets: central banks, "China, among others," are "buying the dips while continuing to reduce US Treasury holdings at a steady pace, as the de-dollarisation theme continues unabated." China's chart says it all: PBOC gold reserves are up 20% since 2022 (and 122% since 2015) to 2,345 tonnes, while its Treasury holdings are down 41% since 2020.

China: Officially 20 Tonnes, Unofficially Much More

Officially, the PBOC added 20 tons in August, its 22nd consecutive month of net purchases, which Nikkei notes is the longest streak since comparable data began in December 1999. Unofficially, the number is much bigger, which is something we have been flagging since 2024 (and again here, Jun 13, 2025), well before the FT "confirmed" it (Nov 15, 2025):

Nothing has changed since. Goldman's central bank nowcast estimated 44 tonnes of official buying in July (Sep 14), with China accounting for 35 tonnes, roughly double what Beijing admits to. On a three-month seasonally adjusted basis, Goldman's Lina Thomas and Daan Struyven now see central banks buying ~91 tonnes per month, more than five times the pre-2022 average of 17 tonnes.

Then there's the private side, where the hoarding is even louder. Goldman's head of commodity market strats Adam Gillard pointed out last month that when Bloomberg discovered "record Chinese gold imports," it was hardly news: China's non-monetary imports were 997 tonnes in January through July, up 80% y/y, with another 142 tonnes in August. Even more interesting, he noted that the strength came largely from "higher flows into Beijing + Guangdong flows which has previously been associated with official sector buying." Put differently, some of that "non-monetary" gold may be quite monetary indeed.

Gillard's numbers also show who is holding up the market. Between March and July, China's imports more than doubled from the prior five months, offsetting a 228-tonne drop in Indian imports and a 253-tonne swing to ETF selling outside China, almost by itself (net change across the four: -29 tonnes).

JPMorgan's Market Intelligence desk picked up on the same thing (Sep 23), crediting gold's surprising resilience to the Fed's hawkish repricing to two forces: ETFs that have "net added tonnes every week since mid-July" (about 180 tonnes in total), and "strong Chinese buying – imports topped a record 1000 tonnes." Meanwhile, the buyer list keeps getting broader and less Western: SocGen's table of the top five central-bank buyers each year now reads Poland, China, Kazakhstan, Czech Republic and Chile.

Goldman: Central Banks Are Doing "Nearly All" The Heavy Lifting

This is where the Nikkei story ties into the bull case. In its latest Precious Analyst note, "Fed Hikes to Slow, Rather than Derail, the Gold Rally", Goldman kept its $5,400/toz end-2027 forecast despite the Fed's hike, and was explicit about what is driving it:

Continued central bank diversification remains the main structural driver of our constructive gold view, contributing nearly all of our expected 23% appreciation through end-2027. ... Reflecting this acceleration, we raise our central bank demand assumption to 60 tonnes/month on average through 2026-27, versus 50 tonnes/month in 2026 and 40 tonnes/month in 2027 previously. We continue to view reserve diversification following the 2022 freeze of Russian central bank assets as structural, and recent central bank conversations suggest the appetite for gold remains strong.

ETFs and speculators are barely a rounding error in Goldman's math; this is a central bank story, full stop.

And here is the problem for anyone hoping the producer-country trend is already priced in: Goldman's model counts reported and nowcast central-bank purchases, not tonnes that never leave Laos, Jakarta or Shandong in the first place. If producer countries keep a growing share of their own output, through domestic refining, export taxes or central-bank purchase programs like Madagascar's, that is supply removed from the international market, and the bank's "net upside risk" gets a little more upside.

The near-term path is slower, though: Goldman cut its year-end 2026 fair value to $4,650/toz from $4,900, still above spot.

There is also a wildcard: call-option positioning on GLD is still about three times historical averages, which Goldman reads as a sign that worries about "G10 fiscal sustainability" are keeping demand for gold as a "macro-policy hedge" alive. If that positioning holds while central banks keep buying, dealer hedging "could mechanically amplify the rally and drive gold prices well above our forecast." (With France now going full PIIGS on the bond market, we doubt those fiscal worries go away anytime soon.)

So Why Is Gold Down 12%?

Because structural doesn't mean imminent. Gold hit a record above $5,500 in January, nearly reached $4,700 in late August, and was $4,110 on Sept 28, down 12% from that late-summer peak. Nikkei puts the blame where it belongs: the Fed raised rates in September for the first time in more than three years, with at least one more hike expected before year-end. As Nikkei says, downward pressure is likely to persist "until the ultimate level of the policy rate becomes clear."

Goldman's desk agrees. On Sept 28, as gold fell 3% when China liquidated length on the Shanghai open, Gillard passed along a colleague's warning that front-end real rates are back near two-year highs: "when cash suddenly offers a very large positive real return, the opportunity cost becomes difficult to ignore." His assessment of China's physical bid was just as careful: "supports price on a sell-off but isn't enough to sustain a rally." This weekend's GS commodities desk note (Oct 4) said "rates are holding it back, but still long-term constructive," with "very low" short-term conviction on delta but "strong support at $4k/oz." GS Materials specialist James McGeoch summarized feedback from the road even more briefly: "Gold most interesting asymmetry, $4k floor, pick a ceiling."

For the bear case, BofA's technicians (Jul 16) warned that "gold's lost year may leave 2H26 vulnerable," pointing to a death cross, crowded positioning and similarities to the 1980 and 2011 tops, which they say put $3,315 in play "if 2026 proves to be a major top." Jefferies' mining team (Aug 4) likewise argued that gold has "recoupled" with real rates. Fair enough, but neither the 1980 nor the 2011 top came with 91 tonnes a month of central bank buying and producer countries locking up supply at the mine.

Bottom Line

Nikkei ends on what could be the thesis for the rest of this decade, quoting ANZ's Yum: "In the long run, the actions of producer countries could become another factor pushing gold prices higher."

We'd go further. For three years the gold story has been about the buyers: central banks diversifying away from a weaponized dollar. What Nikkei describes is the supply side catching on, as the countries that dig the metal up decide they would rather hold it than sell it for Treasuries they might not be allowed to keep. Combine 91 tonnes a month of official buying with mines that increasingly stay home, and the $4,000 floor everyone on the GS desk keeps citing looks more like a minimum than a hope.

In the near term, Warsh and the front end are in charge, and nobody should expect producer-country hoarding to beat a hiking Fed in any given week. Over a horizon of a few years, though, betting that the dollar's share of reserves recovers while Laos, Jakarta and Beijing go back to shipping out ore looks like the much harder trade. Then again, the West has bet against the colonies' gold before... it didn't go great. The next test comes Thursday, when China returns from Golden Week and shows whether the dip-buyers are still there. 

Much more in the full Goldman and SocGen notes, both available to pro subs.

Tyler Durden Tue, 10/06/2026 - 13:20

OpenAI Shops $30 Billion Round To UAE Funds, BlackRock As Altman's 'Bad Things' Remark Draws Bipartisan Fire

OpenAI Shops $30 Billion Round To UAE Funds, BlackRock As Altman's 'Bad Things' Remark Draws Bipartisan Fire

With its planned IPO on ice for the moment, OpenAI is pitching a $30 billion funding round to a group of United Arab Emirates sovereign funds led by Abu Dhabi's MGX, along with BlackRock, at a $1.4 trillion pre-money valuation, Bloomberg reported Monday. There is no lead investor, and the price was set by OpenAI rather than negotiated. Meanwhile CEO Sam Altman has sparked a firestorm in DC with comments that the world should accept "some bad things happening" for the benefits of AI.

The OpenAI round

The UAE funds are considering an investment up to $10 billion between them at that $1.4 trillion valuation - which is is 64% above the $852 billion post-money valuation of the $122 billion round in March. The figure would also place OpenAI's valuation above Anthropic, which was at $965 billion in May.

OpenAI's annualized revenue has reportedly passed $40 billion, up 70% since July. That makes the ask roughly 35x run-rate for a company that Fortune says booked $6.7 billion of revenue and an operating loss in Q2, and that the FT reported spent $34 billion last year. One FT source said OpenAI "needs capital." OpenAI says the March round left it with plenty. OpenAI filed confidentially for an IPO on June 8. Then, on Sept. 12, Altman told Fortune it wouldn't be 2026 - "an ill-advised moment to go public," given what's going on with safety (and then just recently said 'screw it' - AI is worth the danger). That said, in April the WSJ reported that OpenAI had missed revenue and user targets and that CFO Sarah Friar was worried the company might not be able to pay for future compute contracts if revenue failed to catch up.

Then there's the backstop. As we reported last November, Friar suggested the federal government could "backstop" OpenAI's data-center financing. In June, as we detailed, Altman began floating a plan to hand small OpenAI equity stakes to ordinary Americans, which we read as a backdoor backstop. We asked at the time whether the bailout would come before the IPO or after. Nobody mentioned the third option: a $30 billion bridge round, priced by the issuer, in between.

DeepSeek

Overnight, Bloomberg also reported that DeepSeek is close to locking in at least 80 billion yuan ($12 billion) of new funding, with signed term sheets that could take the total to 100 billion yuan - twice the 50 billion it originally set out to raise. Tencent and CATL are writing the biggest checks. This is the same round DeepSeek paused in late July, as we noted, after transcripts leaked of founder Liang Wenfeng saying that Huawei was giving DeepSeek about 16,000 Ascend 950s while the internet giants got hundreds of thousands, and that DeepSeek could get hold of some processors he called "noncompliant." The round restarted in August at a valuation of about $74 billion and has now blown through its target. On annualized revenue reported at $400-500 million in July, that valuation is well over 100x sales. OpenAI at 35x looks cheap next to it.

The 'bad things' backlash

Altman made the remark in an interview with Politico's Decoded newsletter published Sunday. "We believe that the world should accept some bad things happening for the benefits of this technology and people having the agency," he said, according to Forbes. He also said he expects "orders of magnitude more" positive outcomes than negative ones.

Florida Gov. Ron DeSantis, a Republican, responded on social media: "And a handful of tech oligarchs get to make that decision for the rest of us? No dice." Illinois Gov. JB Pritzker, a Democrat, posted that Altman "shouldn't be making any decisions about what 'bad things' we have to accept on all of our behalf." Sen. Ruben Gallego, a Democrat from Arizona, wrote one word: "No."

Politico noted that much of the backlash assumed Altman was accepting existential harm to humanity, which he explicitly said he was not, or that he was trying to dodge responsibility for AI-caused damage, when he in fact called for policymakers to debate new AI liability regimes.

Alyssa Cass, a political consultant who has worked with New York AI-safety lawmaker Alex Bores, told Politico the equation is simple: "There is more safety talk from OpenAI because there are more safety incidents from OpenAI."

Those incidents keep piling up. In July, roughly 700 OpenAI agents got out of their sandbox during an internal cyber evaluation and spent July 9-13 inside Hugging Face's production systems trying to game their benchmark; Hugging Face later said it had to use an open-source Chinese model to defend itself. After another escape on Sept. 20, OpenAI paused training on its most capable models, and on Sept. 28 it cancelled GPT-6.1 Astra, its October flagship, after its head of safety said the model had regressed on deception. On Oct. 2, it said it had notified more than 100 organizations of "misaligned agent activity," and on Tuesday it apologized again at a hearing in Sydney for its agents' unauthorized access to Australian government websites.

Regulatory Capture The Flag

And so of course, Congress wants - no NEEDS - to control this technology. Democratic Sen. Richard Blumenthal went first, alone, with a Sept. 9 letter to Altman, and Republican Sen. Josh Hawley opened a Senate investigation the next day. Since Sept. 28, Florida AG James Uthmeier, who sued OpenAI in June, has moved for an injunction to stop it from building new models without third-party-approved safeguards, the nonprofit LASST has sued, and California AG Rob Bonta has served a subpoena.

Sen. Elizabeth Warren joined him for a Sept. 28 letter to Treasury Secretary Scott Bessent. It goes after the June executive order that created a classified "benchmarking" process for frontier models, run partly out of Treasury. Participation was made voluntary, reportedly after Meta's Mark Zuckerberg and allies intervened. It also cites Reuters reporting that administration officials promised the labs that open-weight models would be exempt from safety testing, and notes that open-weight models including DeepSeek V4 Pro are good at finding and exploiting vulnerabilities. "Voluntary measures and self-policing clearly are not working," the senators wrote. Answers are due Oct. 9 - this Friday.

The next day, Trump had the labs to lunch and came out, as we covered, with a morally, though not legally, binding accord. Semafor later reported that Zuckerberg was central to drafting it.

Hence today's letter, published by Semafor and addressed to Bessent and White House chief of staff Susie Wiles, among others. It asks for all meetings and correspondence between industry and the government before the June order and an actual description of the pre-deployment testing process the White House keeps saying exists. The senators want guardrails set by elected officials, not "a toothless framework shaped in secret by a handful of billionaires." Answers are due Oct. 19.

Will any of it get answered? Semafor's read is that the demands only get teeth if Democrats retake Congress. In the meantime, the sovereign funds being asked for $10 billion can read a Senate letter as well as anyone.

Tyler Durden Tue, 10/06/2026 - 13:00

Google Plugs Into Constellation's Nuclear Reactors As PJM's "Bring Your Own Power" Era Arrives

Google Plugs Into Constellation's Nuclear Reactors As PJM's "Bring Your Own Power" Era Arrives

For most of 2026, the bear case on the US power producers could be summed up in one sentence: nobody is signing data center PPAs in PJM. Last week Amazon did. This morning Google did, too, and this one is five times bigger.

Google parent Alphabet has contracted for 3,590 megawatts of power from Constellation Energy (CEG) inside PJM, the largest US grid, the companies said on Tuesday, according to Reuters, confirming an overnight report from Bloomberg. Roughly a quarter of it, 890 MW, is new nuclear capacity squeezed out of 11 existing reactors under a 20-year PPA backed by more than $4.3 billion of Constellation investment, expected to start delivering in 2028. The rest is a long-term supply agreement for another 2,700 MW. And in case anyone missed why this is happening now, the companies said it outright: the deal is a response to PJM's "bring your own power" proposal.

Constellation shares jumped as much as 14% premarket (they were up 6.3% when Bloomberg first broke the story last night), trading above $300 for the first time in a month. 

Zerohedge readers know this story didn't start this morning. We have been tracking the AI-nuclear trade since Microsoft agreed to restart Three Mile Island in September 2024, when nuclear names surged across the board on what was then a shocking headline. (Five years earlier, we were writing about "America's Chernobyl" finally closing its doors. Funny how the AI capex cycle changes things.) Two years later, Constellation has become Big Tech's nuclear landlord.

Below we break down the deal, why PJM forced Google's hand, what Goldman's power desk and utilities team are saying, and why the cheapest nuclear megawatt is the one already built.

The Deal: 890 Nuclear Megawatts... Plus 2,700 More

The terms, per the companies' statement and the Reuters and Bloomberg reports:

  • 890 MW of new nuclear capacity under a 20-year PPA, coming from upgrades at 11 Constellation units in Illinois, Pennsylvania and New Jersey. The first upgraded plant is expected to start delivering in 2028.
  • $4.3 billion+ of new investment by Constellation in "new equipment and technology... increasing thermal and electric efficiency," as Goldman's industrials desk put it this morning.
  • A separate long-term supply agreement for 2,700 MW in PJM that is "not tied to a specific generation source and serves as long-term revenue certainty for Constellation's operating plants," per Google.

Translation: the 890 MW is the headline-friendly "new clean firm power" part. The 2,700 MW is essentially Google locking in a long-dated price for a big chunk of Constellation's existing output. Who needs a hedging desk when you have a hyperscaler?

Stack it next to Constellation's other hyperscaler deals and Google's is bigger than Microsoft, Meta and Amazon put together (2,646 MW combined), at least once the non-unit-specific supply is counted:

It also comes less than a week after Amazon's 690 MW, 20-year PPA at Calvert Cliffs, which we covered on Thursday in "Amazon Secures 20 Years Of Nuclear Power From Constellation As Goldman Sees Industry-Wide Win". And Google is hardly new to the game: it is already funding the restart of NextEra's Duane Arnold reactor in Iowa (which just landed a $1.9BN DOE loan), and last month lined up new capacity from Southern Co. by paying for upgrades at two of its nuclear plants.

Here is a snapshot of Constellation's recent nuclear deals, updated for the just announced Google transaction, along with disclosed terms:

And a summary of the terms of both the Google deal and the recent agreements with Microsoft, Meta, Amazon and GSA. 

Why Now? "Bring Your Own Power" Is Coming To PJM

The key line in the Reuters story is the last one. PJM management has proposed that data centers connecting to its 13-state grid either bring their own power or accept being remotely cut off during peak demand. Goldman's Nelson Armbrust laid out the mechanics in his What Matters Today note this morning (available to pro subs):

"Today, when you build a data center, you need a permit but you don't need to secure energy – this is what will be ruled (hopefully) on October 12th. PJM's proposed Interim Resource Adequacy Service (IRAS) targets new large loads (≥ 50 MW) entering service after June 1, 2027. To avoid priority grid curtailment during emergencies, data centers must secure their own power under the "Bring Your Own New Capacity" (BYONC) framework."

In other words, Google just bought its ticket before FERC decides on the price of admission. Armbrust adds that excluding unbacked loads from capacity planning starting in the 2029/30 delivery year "aims to lower capacity prices and stabilize asset valuations."

Lower capacity prices would certainly be a change of pace. As we tweeted the night of July's auction, PJM is already out of power:

Capacity prices have gone from $28.92/MW-day to the cap in two auctions, and the cap is the only thing that kept 2028/29 from clearing at $554.72:

PJM's emergency fix, a one-time "backstop" auction for new capacity, didn't go much better. As we detailed on Sunday in "'Deeply Flawed': Biggest US Grid Scraps Emergency Data Center Power Auction One Day After FERC Smackdown", FERC suspended the Reliability Backstop Procurement for five months. That's a power auction for data centers... delayed. Goldman utilities analyst Carly Davenport called it "net bearish but mixed" for the IPPs, and pointed straight at the bilateral route Google just took (available here for pro subs):

"...lack of clarity around the finalized framework could lengthen the regulatory overhang on the stocks and dampen data center customer appetite to sign long term PPAs, though continue to point to higher pricing and tight markets in PJM in the absence of line of sight to new capacity. We also believe given the bilateral process is preferred by many developers/customers, the ruling on the IRAS framework could be more consequential, which, if constructive could limit the need of the RBP."

A few days ago, Davenport also named Neutral-rated CEG and Buy-rated TLN as "most exposed given the PJM leverage." This morning that exposure worked in Constellation's favor.

As for who has been paying for PJM's shortfall so far: the ratepayers. Davenport's work shows every PJM state has seen bill inflation above the US average over the past three years, with PJM bills up more than 24%. That's roughly 10 points above the national average, and New Jersey alone is up 43.4% (chart source GS Power Up America webinar):

With the midterms four weeks away, nobody in Trenton, Annapolis or Harrisburg wants to explain the next leg higher. Hence "bring your own power."

Goldman: From A "Heartbeat" To A Pulse

For context on why the IPPs have been such a slog, here is Goldman's GSX desk summarizing last week's Power Up America webinar with Davenport, Joe Ritchie, Adam Bubes and Olivia Foster (available to pro subs):

"No large-scale data center PPA between a developer and an IPP has been announced since January. FERC is expected to rule on the PJM large-load framework on October 12... RBP (Reliability Backstop Procurement) filings in PJM should also move in the near term. Together with the midterms, these are the main gating items for PJM deal flow."

That "since January" drought ended twice in seven days. The webinar also noted that the group is down ~30% over the last 12 months, with CEG, NRG, TLN and VST trading on average at just over 7x EBITDA and a 12% free cash flow yield on 2027 estimates, "both at the discounted end of historical ranges," while the IPP basket trades near its Liberation Day lows:

After the Amazon deal, Goldman's power specialist Adam Wijaya said one investor question "stuck out": can this get the group working again? His answer was that the PPA gives "a sense of a 'heartbeat' for the group on go forward." To be sure, this second, much bigger, deal a week later starts to look like a pulse.

On the numbers, Davenport valued the Amazon deal using Constellation's own disclosure: a 1 GW nuclear PPA at a $20-$50/MWh premium to the PTC floor is worth $125M-$325M of FCF before growth. That implied $86M-$224M for Amazon's 690 MW, which she called "a solid update" but small at "~3% of its total nuclear fleet." Applying the same yardstick to Google's 890 MW gives roughly $110M-$290M (napkin math, before whatever the 2,700 MW supply deal is worth). Add Amazon and Constellation has signed up something like $200M-$510M of annual FCF upside in a week. Davenport is still Neutral with a $305 price target, which is suddenly right on top of where the stock is trading on Tuesday morning. We expect the next price target revision to point (much) higher. 

Putting it all in one place, here is what the two PPAs signed in the past seven days are worth to Constellation, using Goldman's own FCF yardstick alongside some illustrative revenue math. Not bad for what Bloomberg billed overnight as a mere "billion-dollar" deal: Constellation's investment alone is $4.3 billion, and the PPA revenue could top $1 billion a year once both deals are running.

And that's before a single dollar from the 2,700 MW supply agreement, which is three times the size of the nuclear PPA.

Goldman's desk was already leaning in before this morning's print. Armbrust called the US Power Up basket (GSENEPOW) a buy with "P/E is at 1y lows, RSI at 50 and price performance has been lackluster... I think its a buy."

The Cheapest Nuclear Megawatt Is The One You Already Own

The underappreciated part of the deal is how Google gets its new 890 MW: uprates, meaning squeezing more output from reactors that are already licensed, built and on the grid. No new site, no decade-long permitting, no first-of-a-kind cost overruns.

Some napkin math: $4.3 billion for 890 MW works out to roughly $4,800 per kW. That is more than a new gas plant (Goldman's Ritchie says a 400-500 MW CCGT now costs "roughly $400-500 million," or about $1,000/kW, if you can get turbines and an interconnection slot within 4.5 years). But it is a fraction of new large nuclear: the US-Korea package earmarks $120 billion for eight reactors (six AP1000s and two APR1400s), which works out to well over $10,000/kW. And unlike the gas plant, the uprate comes with 20 years of carbon-free, around-the-clock output and no fuel-price risk: even the heavily pro-Democrat labor unions are starting to like nuclear.

Lined up side by side, the math is hard to argue with. Gas is the cheapest per kW... if you can get the turbines and survive a four-and-a-half-year interconnection queue. Restarting a shuttered reactor, as Microsoft is doing at Three Mile Island, is the real bargain, but there are only so many mothballed reactors left to restart. Which leaves uprates: roughly a third of the cost of a new reactor, a decade sooner, and on sites that are already licensed and plugged into the grid:

Little wonder, then, that Google is paying Constellation to squeeze more out of what it already owns rather than wait for the AP1000s. It's also why the next round of hyperscaler deals will likely look a lot like this one.

That US-Korea deal is one of three nuclear headlines Armbrust counted in the past week, together with the $4 billion federal loan for Vistra to boost nuclear output, and now Google-Constellation. And yet positioning is going the other way:

"Positioning in in our Uranium basket (GSXURANI) is at the lows… time to reengage?"

Goldman's Brian Lee added that the Korea program "further tighten[s] the expected uranium supply balance in the 2030s." Uranium pros at the lows while governments and hyperscalers race to lock up reactors. That is one hell of a setup.

The demand side isn't easing either. GIR sees 108 GW of US data center power demand by 2030, up from 39 GW in 2025...

...which lifts total US power demand growth to a 3.5% CAGR, a number that would have been laughed out of any utility investor day five years ago:

Or, as Ritchie put it: "the demand environment right now honestly just couldn't be better."

Who Pays? (Hint: Not Just Google)

Google can afford it. Consensus expects hyperscaler capex to grow 116% year/year in Q3, and Goldman expects more than 50% growth in 2027, above the ~$1.1 trillion consensus. That's something we discussed earlier in "'The S&P 2': Micron And Nvidia Alone Will Deliver A Third Of Q3 Earnings Growth":

How that capex gets financed is a separate question, and increasingly a debt-funded one. But 20-year power contracts are the kind of off-balance sheet commitments that tend not to show up in the leverage ratios until someone goes looking for them.

Still, Google signing for its own capacity beats the alternative, which is 67 million PJM customers paying for it through capacity charges. This is the model we have been demanding for nearly a year: if hyperscalers want to plug a city's worth of load into the grid, they bring their own power.

Goldman has since come around, raising its behind-the-meter forecast to 67GW by 2030. Google's deal isn't behind the meter (the electrons still flow into PJM), but it is the next best thing: the data center pays for the new capacity, not the ratepayer. And in the long run, we still think the real answer is a small modular reactor sitting next to every data center campus.

Bottom Line

Goldman's Wijaya put it best after the Amazon deal: "we know how quickly the tide can turn on power." The tide just turned twice in a week, and the catalyst that matters most is still ahead: FERC's ruling on PJM's large-load framework on October 12. If IRAS is approved in anything like its current form, every hyperscaler building in PJM after mid-2027 will need to bring its own capacity or accept being curtailed first, and there are only so many existing reactors to sign.

Which is why we think the 3,590 MW is the floor, not the ceiling. Two hyperscalers have now signed with the largest US nuclear operator in seven days, while the IPPs still trade at ~7x EBITDA with uranium positioning at the lows. Either the market is right that politics and regulators will keep the group in the penalty box, or (far more likely) the rest of Big Tech is about to queue up for the same reactors. Then again, a regulator that has already punted the RBP once could punt again.

We'll check back after FERC rules next Monday.

More in the full Goldman "Constellation Energy announces a 20-year nuclear PPA for ~700 MW in PJM; positive for industry broadly" and "Americas Utilities: Power: FERC suspends the RBP process for five months; mixed for IPPs but IRAS still key" notes, both available to pro subs.

Tyler Durden Tue, 10/06/2026 - 12:25

Pages